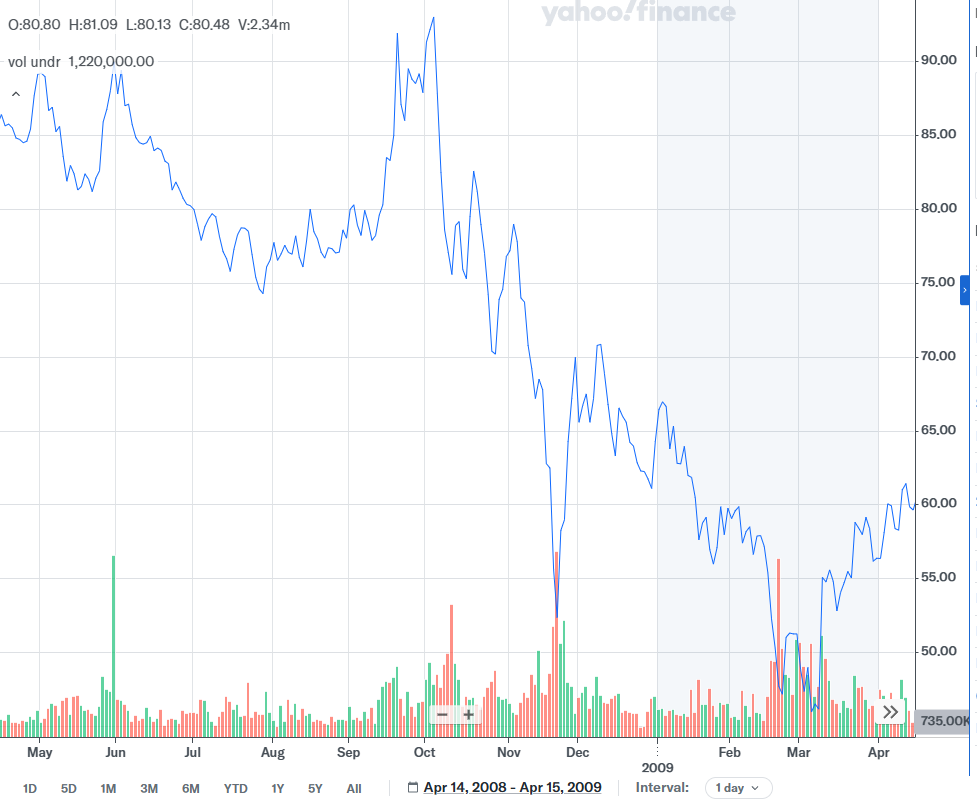
How do you make this happen during severe crisis years? For example, during the 2008 financial crisis, practically the entire market dropped by tens of percent, even so-called quality stocks. (My own well-diversified portfolio melted by tens of percent, and at the same time, I used all the small amounts of money I could find to buy mainly US stocks when the dollar was cheap and prices were low.)
Attached as an example is the share price of one true quality company, Berkshire Hathaway, over a one-year period through the crisis - as you can see, at its worst, the collapse was several tens of percent, and after the crisis subsided, it was about -30% compared to the pre-crisis period:
Personally, since that crisis, for the period 2009-2026, I have achieved a total annual return of +15.2% before taxes (i.e., +1074% for the entire period), but to achieve that return, there have been some bad years in between (the worst being -52%). So, at least in my case, excess returns (alpha) have been generated, but as a trade-off, I’ve had to accept the bad years as well.
I am interested in this because your strategy is somewhat similar to the one I have used (albeit mine is more erratic) and your return target is in the same ballpark as my actual returns.
Most of my (original) investments have been in the $1–5 billion range. I find that to be a sort of sweet spot: small enough that the market isn’t fully efficient and every detail isn’t priced into the stock, but large enough to find stable, high-quality companies + sufficient liquidity for the company’s own buybacks.
Let AerCap be an example: first purchased in early 2021. Market cap was around $18 billion, trading at 7x earnings and below book value. The company unlocked value by selling aircraft above their book value and using the proceeds to buy back its own shares below book value, such that “effectively,” for every euro on the balance sheet, AerCap bought back its own shares to be cancelled for two euros. The stock has doubled since then and is now trading… yes, still at 7x earnings, because the same mechanism is still working.
I probably don’t. In 2022, I was down nearly 40 percent, which I’ve made visible on every tab in my Excel as a reminder of the mistakes made during that investment year. Back then, of course, I didn’t invest the way I do now, but I want to remember that losses can be deep.
I don’t believe that in a severe crisis I can keep the portfolio in the black without using some kind of insurance-type option—I don’t engage in those, at least for now, so probably not. That goal of avoiding loss-making years is more of a guiding principle to always invest with a high margin of safety, especially when the market is having a sluggish year overall. If reaching a 15 percent return target required deviating from the strategy and taking excessive risks that I’m not good at, then I can lean on the goal of “don’t lose money” and accept a year of lower returns.
I was watching some old Buffett interviews and picked up the following piece of wisdom to ponder for my investment strategy:
Buffett was asked if he uses certain key ratios to analyze new investment targets. He replied that he aims to look at where the company will be in five to ten years—specifically, whether the company’s earnings will be significantly better than they are now. Of course, one cannot make precise forecasts that far ahead (or you are just fooling yourself), but you can consider the order of magnitude very roughly. Then, you compare that to the current share price and make a decision based on that. Since exact figures cannot be known, a “margin of safety” (turvamarginaali) is used, meaning there must be a margin between the current share price and the future visions.
In other words, you don’t invest based on where earnings are now, but rather consider the company’s ability to grow its earnings in the future. According to Buffett, no actual complex calculations beyond that are needed. It is enough that the company’s earnings will, with sufficient certainty, be significantly better in the future than they are today, and that the price paid for the stock is not unreasonable.
I started thinking about this. My own strategy has evolved a bit too much and probably will continue to do so; I’ve thought of it as a matter of personality. But thinking more closely, it’s not (just) that, but rather a slightly different matter.
That is, what one aims for with investing and what kind of strategy suits that. If the goal is simply to build wealth along with the market, index investing is the most sensible approach. That gives you the market return without doing anything special.
My own strategy differs very much from index investing, and the question is, why? I had to think about the answer for a bit, but maybe it could be summarized like this:
In addition to returns, I also want intellectual challenge and interest from the markets. And I want to feel comfortable with my companies, so that I’m not involved in companies I don’t believe in. I accept that my portfolio develops differently than the indices and that I run a clear risk of underperforming the market return. In other words, I live in the illusion that the companies I own might be “safer” than average investments due to their quality.
Hi everyone. I’m writing my first post on the forum.
My investment strategy is long-term fund saving. I put my so-called “extra” savings to work and aim to leave them untouched for at least the next 25 years.
The goal is low costs, low risk, and I am satisfied with a 5-7% annual return. I aim to minimize ongoing costs and diversify the portfolio sufficiently, while still keeping investing simple for myself.
My investment portfolio is with OP, naturally where my other banking services are currently located. I monthly save into the OP World Index (OP Maailma Indeksi) and make larger lump-sum purchases into the SPDR MSCI Europe Small Cap Value Weighted UCITS ETF.
The target weight for the portfolio is 80% World Index and 20% Europe ETF. This represents a “Core/satellite” model, where the world index acts as the “core” and the “satellite” ETF seeks return potential from European value companies.
Thinking about the future, I am considering a portfolio reorganization at some point. I am weighing the following points, since my goal was low ongoing costs and broad diversification:
Should I move my monthly savings to Nordnet, where I can find funds with lower management fees (0.20%) that invest similarly to the OP World Index (0.39%)?
Should the portfolio be diversified more broadly geographically and into other sectors? Currently, the world index consists heavily (approx. 70%) of American tech companies, which are now balanced by European “old economy” companies.
Regarding these points, I would love to hear your thoughts!
Thanks to everyone who has shared their strategy so far. I’ll be following along.
I’m not trying to defend OP and its bonus system, but as an owner-customer, don’t you accumulate bonuses (after taxes) roughly equal to that difference in costs? Of course, if you aren’t an owner-customer, the difference is significant, and on the other hand, I understand if you don’t want to support that particular firm.
First of all, you can withdraw them as cash to your account and then make an investment. There is also likely an automated feature where you can choose for OP to transfer the payment coming into the bonus account directly into a fund subscription.
Index funds accumulate a net bonus of 0.245%, so the effective management fee is practically 0.145%.
In my own strategy, I have still made larger lump-sum investments through ETFs, but currently, the OP-World Index (OP-Maailma indeksi) serves as my monthly investment target.
In addition, there is the OP Säästölipas (Savings Piggy Bank), where you can accumulate a chosen euro amount per debit card purchase (I have set mine to 2 euros/purchase). By setting the target limit of the Savings Piggy Bank to one euro and directing the excess into the OP Maailma (OP World) fund, you get a nice and discreet steady stream into the index.
It’s a shame that OP no longer has the 1% fee cap on ETFs, which allowed for smaller purchases for time-based diversification. Now, I continue even more fiercely growing OP’s index funds over decades through monthly savings.
That is indeed handy micro-saving; it’s also an easy way to notice that even if card purchases were 2 euros more expensive every time, it doesn’t necessarily have to be felt in one’s finances.
In my case, 1 euro goes into the Money Box from every card payment, and nearly 900 euros has accumulated in 1.5 years almost unnoticed and automatically—so I suppose I am some sort of active card user. My goal is a cash buffer of at least 5,000 euros, for which I don’t have much use, but “I’m saving since it can be done unnoticed” and a cash buffer is advertised as sensible. That sum will be reached in 7–8 years, which is a blink of an eye in adult years.
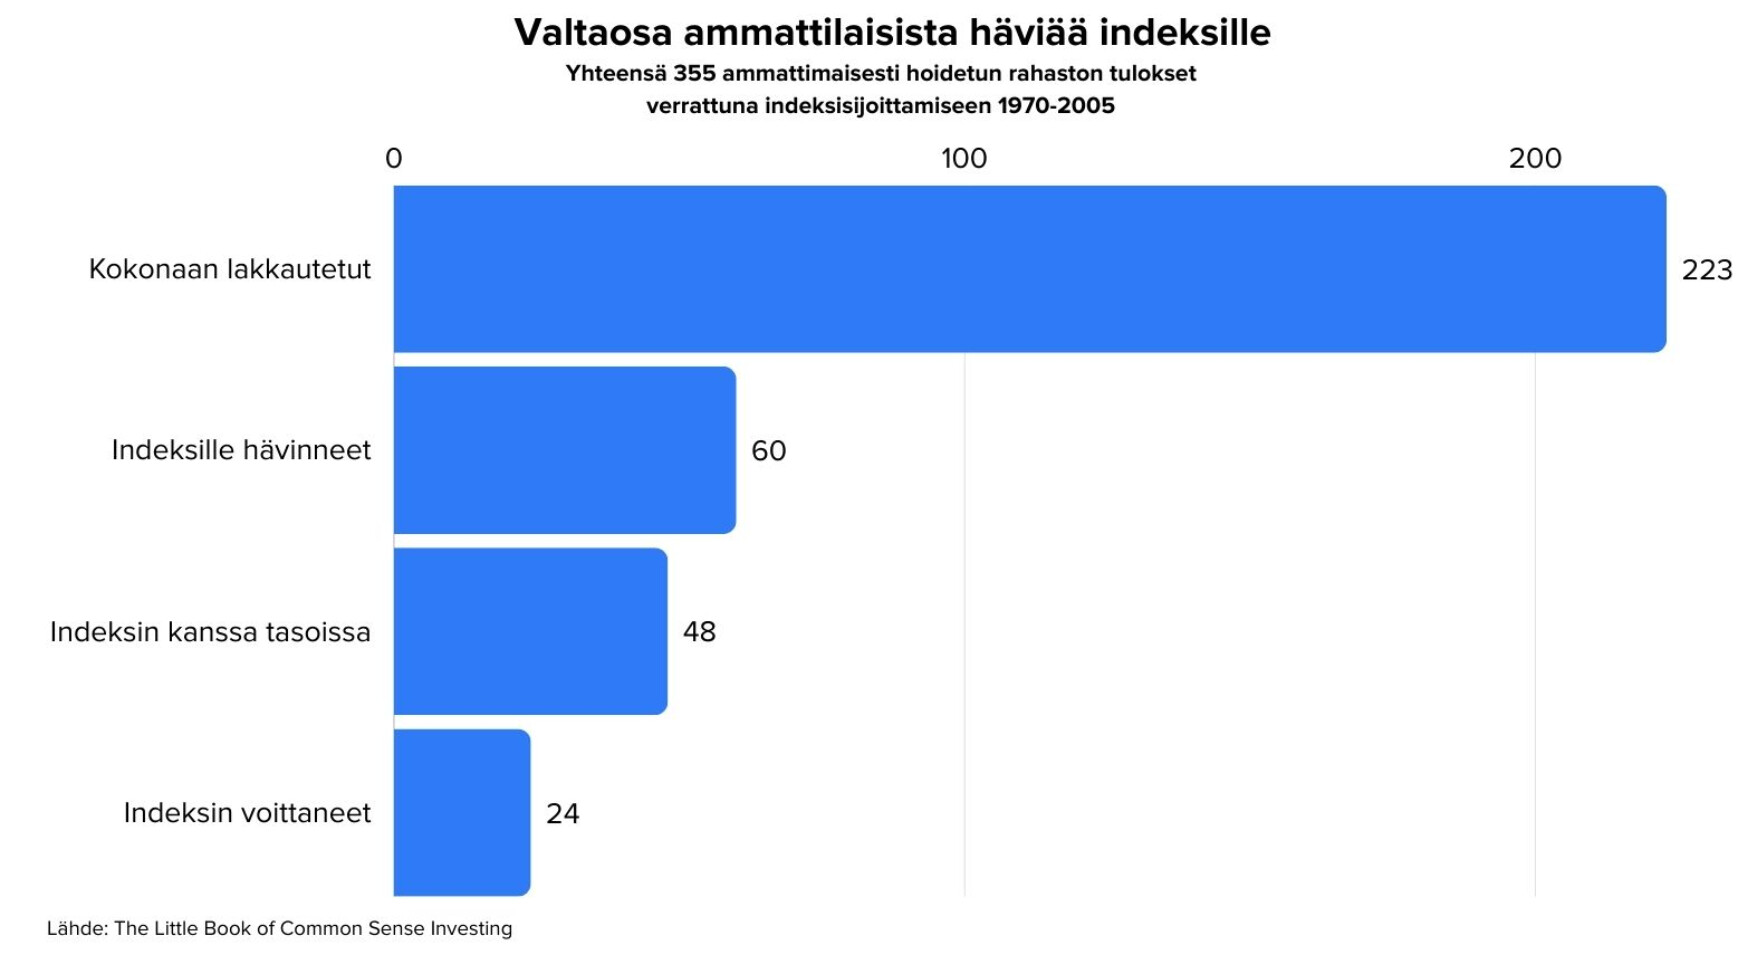
I’ll move this index vs. active stock picking discussion over to this thread. So, why be a stock picker when index investing gets you the average market return?
You can find a great article on this topic in Inderes’ articles (link at the end). This chart, in particular, was eye-opening: over a truly long term (35 years), a very small portion of actively managed investment funds beat the index.
I have been following the fund market in Finland more actively since 1998, and my own gut observations align with this. (A small side note: a surprisingly high number of poor-performing funds are shut down by merging them into better ones, which causes their poor returns to “disappear” from reports.)
Often, a certain trend performs well for a while, and funds investing according to that trend do well. But very few funds are able to beat the indices over the long haul.
6.76% of active funds outperformed the index. If that time window were extended further, that percentage would drop even lower. Stock picking is not a very good bet if the goal is to grow wealth efficiently.
I took a look at the latest Fund Report (Rahastoraportti) out of curiosity, and for instance, in the North American market, not a single active fund beat index funds over a 10-year period. It’s the same story for the Finnish market; over 10 years, not a single active fund beat index funds. In the Japanese market, at least one active fund managed to beat an index fund.
Ten years consist of 120 months during which portfolio managers have done a lot of real work, followed the markets and analyses, and executed trades. As a result of those 120 months of work (and 120 months of salary), the return received has lost to simple index funds that don’t take any active view.
Private investors have the advantage that investment fund regulations don’t apply to us. We can invest exactly how we want. I don’t know if there is any real benefit to that; for me, it has enabled many things, but at the same time, it has increased the risk level to the point where the risk-adjusted return isn’t very good.
I read through the report in more detail; you can get quite a lot out of it regarding the realities of the investment world.
One factor is what kind of returns one can realistically expect to achieve. Regardless of your investment strategy, if your return expectations are too high, the resulting “modest” return might cause you to scrap your strategy and look for a new one that could yield better results.
I’ve compiled below the actual 10-year annual returns for funds investing in various markets. These can be used as some sort of “benchmark” when considering your own strategy.
Market and 10-year annualized fund return:
Finland 8.7%
Nordic countries 7.5%
Europe 7.3%
North America 11.7%
Japan 8.0%
Pacific region 8.8%
Emerging markets 8.4%
Emerging - Far East 4.5%
World 9.8%
These figures also include index funds; without them, the numbers would be somewhat lower. You can assess the effectiveness of your own strategy well over the long term: if you are able to achieve an 8–10% annual return (compound interest), you are at a professional level.
The world index has produced an annual return of 12.6%, so beating that with a globally diversified portfolio is a good achievement.
Well, this was a bit of a thought experiment (based on current strong return histories), but sometimes one sees quite ambitious return targets set for portfolios. If/when those targets are not met, there is a great temptation to start jumping from one strategy to another. In that sense, it is good to have realistic benchmarks for what is achievable in the stock market.
Are we arriving at that boring conclusion that just a single index fund would “be enough”? If one had to choose, then the world, or perhaps even just the USA alone.
In addition to a broad market index (which provides exposure to the market factor), one can also invest in factor funds. Examples of these include small-cap value (SCV), large-cap value (LCV), and momentum. However, these tend to have slightly higher fees.
If you want a true “buy and forget” strategy for many years, the easiest way is to buy a world index; that way, the fact that different regions perform differently at various times balances out (some may recall, for example, the popularity of emerging markets years ago, etc.). Perhaps the simplest strategy there is.
Yes. I would personally also take a slice of SCV, because sometimes the market factor alone can perform very poorly for long periods, as happened for example between 2000 and 2015.