Hardworking night owl Joni has completed Siili’s company report late at night with the attitude: ora et labora He prepared the report regarding the technical downward EBITA guidance.
Siili lowered its adjusted EBITA guidance for 2025 last week, which was, however, only a slight disappointment, as the main reason for the decrease was technical. However, the company kept its revenue guidance unchanged, which is particularly positive. It is important that the decline in revenue is reversed, which will allow efficiency measures to yield better results. The stock’s risk-reward ratio is attractive (2026e EV/EBITA and P/E 6x and 9x). We reiterate our ‘add’ recommendation and lower the target price to 5.2 euros (previously 5.5) reflecting the forecast changes.
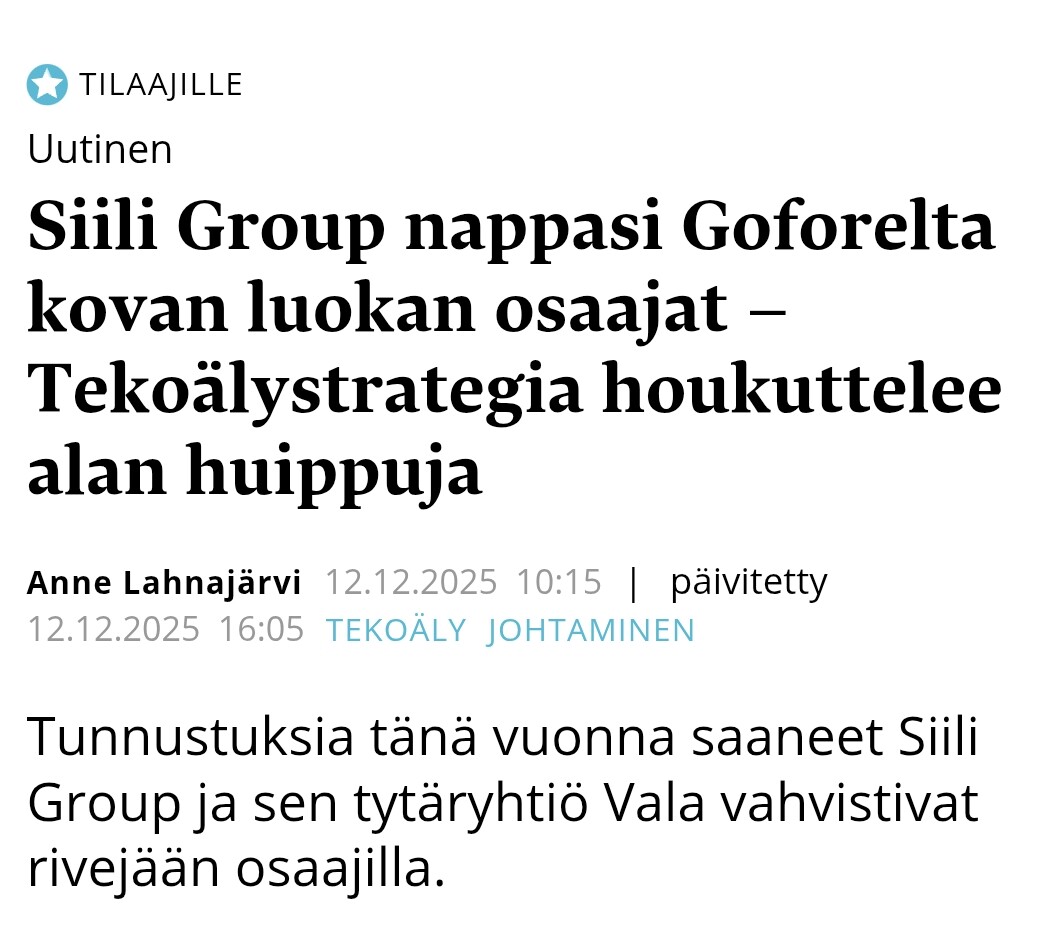
Siili Group’s strategic direction and the culture of its subsidiary Vala Group are now tangibly reflected in two significant recruitments: Virpi Tuohisto and Ari Hirvonen, who have transferred from Gofore, have joined the group in key roles.
Tuohisto started at Vala at the beginning of December in the role of Head of Test Automation & AI, and Hirvonen had already started earlier in the autumn as Siili’s Sales Director.
Siili has declared itself an AI company. It’s still a long way from significant and profitable AI revenue. Time will tell. Hopefully, it brings profitable growth. I think I’ll observe from the sidelines until signs appear on the bottom line.
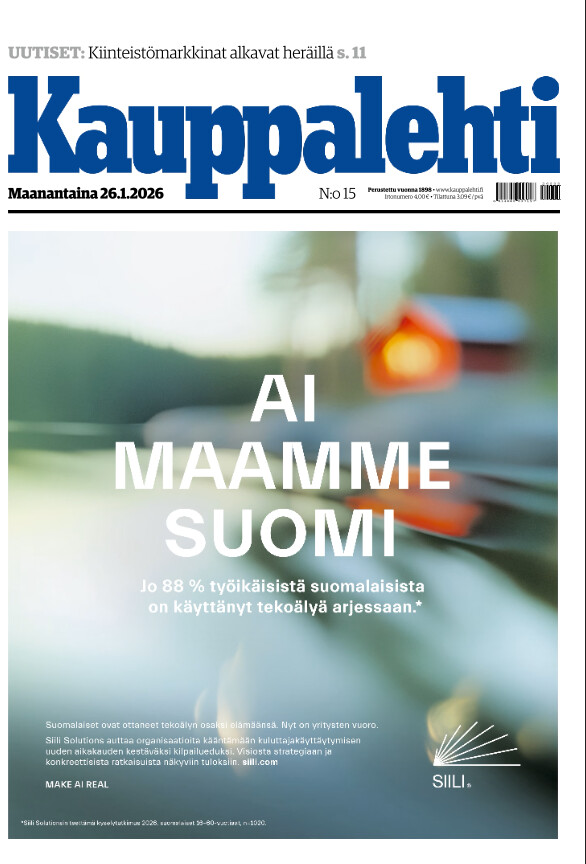
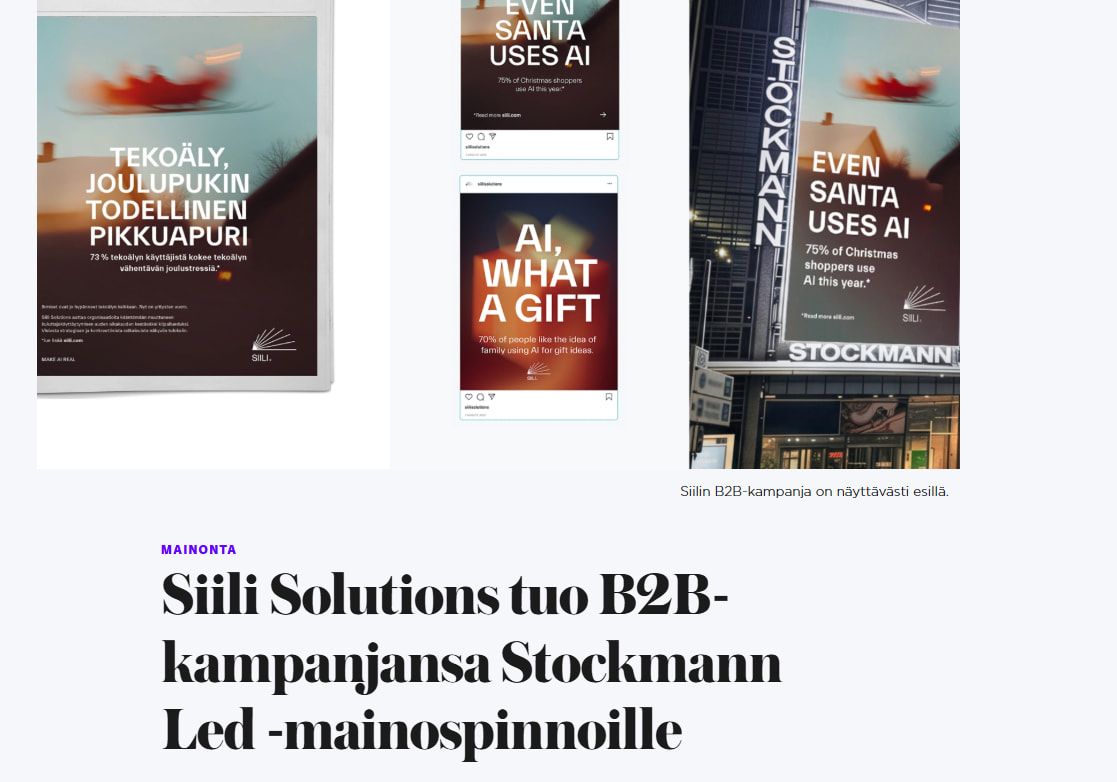
To my eye, Siili has been advertising quite heavily lately. There was another front-page ad in Kauppalehti, and before Christmas, Stockmann was utilized as a billboard. It’s good that they’re drumming things up, but does it also suggest that customers aren’t exactly lining up yet? They’ve been continuing to generate a lot of buzz around AI on LinkedIn and their website lately.
They also managed to get featured on MTV (Maikkari):
We think Siili’s Q4 will provide a lot of factors to understand whether the market is turning. We still forecast 5% growth for 2026. Moreover, we find that the recent EBITA guidance update does not fully reflect the underlying profitability after savings measures. Siili trades at a forward-looking EV/EBITDA of 3.5x, well below its history and peers. We fine-tune our fair value range to EUR 7-10 (from EUR 8-10).
Here are Joni’s pre-result comments on Siili, which will report its Q4 results on Wednesday, February 11.
Siili issued a profit warning in December, the reason for which was mainly technical and affected the Q4 results. However, the company kept its revenue guidance unchanged, which was positive. In the report, our attention is particularly focused on the 2026 guidance, the dividend proposal, and comments on the development of the demand situation during the early part of the year.
Revenue for 2026 is estimated to be 102–126 million euros and adjusted EBITA 3.7–6.9 million euros.
That doesn’t exactly spark cheers of joy, even if it’s not outright horror either. The guidance sounds quite modest in terms of both revenue and profitability. Isn’t a more significant improvement expected for Q4 this year, now that the wave of change negotiations (YT) is over and even the mysterious accounting error has been corrected?
Yep, the profitability guidance is modest, especially compared to the financial targets. In the profit warning, it was mentioned that sales had gone well, but customers’ investment decisions were pushed into this year. I wonder if this explains the somewhat weak revenue development in Q4?
No shouts of joy, but the valuation is modest enough that even at the midpoint of the guidance, the P/E ratio will likely land somewhere around 10. That’s a typical level for a laggard, but considering Siili aims for growth in line with its targets, it’s quite modest. Hopefully, the guidance prepared under the new CFO is more realistic and even more conservative than before, so that there’s a chance to hit the upper end of the range for once.
Regarding that accounting error and its impact, hopefully Joni can extract more information in the interview, as well as about the profitability profile of AI projects.
Here are Joni’s quick comments regarding Siili’s results.
Siili Solutions published its 2025 financial statement bulletin this morning. Revenue fell more than we expected, but supported by cost-saving measures, the result was in line with our expectations in Q4. The company’s guidance range was wide, which is understandable given the market situation. The report contained very few comments on the Q4 situation, so we will investigate this during the day. In the big picture, however, the steepening decline in revenue is concerning.
Joni interviewed Siili’s CEO Tomi Pienimäki right after the earnings release.
Topics:
00:00 Introduction
00:15 Summary of 2025
02:05 Accounting error and operational reasons
03:45 Geographical revenue development
06:43 Progress of AI-assisted software development
09:14 Guidance and underlying assumptions
12:16 Actions to halt the revenue decline
Joni has written a new company report on Siili following the Q4 report.
We reiterate our Accumulate recommendation for the stock and lower the target price to EUR 4.8 (prev. EUR 5.2), reflecting forecast changes. Siili’s Q4 was still weak in terms of revenue, as was the entire year, even though efficiency measures worked relatively well. The market situation has remained challenging, and the transformation into a purer provider of data and AI solutions is still ongoing. We estimate that the company will still have to improve efficiency during the current year, and our forecasts are at the lower end of the guidance. Despite several challenges, the market is, in our view, already clearly pricing this in, and the stock’s risk/reward ratio is cautiously attractive (2026e EV/EBITA and P/E 8x and 11x applying an EBIT-% of 4%).
Quotes from the report:
Revenue decline steepened and fell short of forecasts in Q4
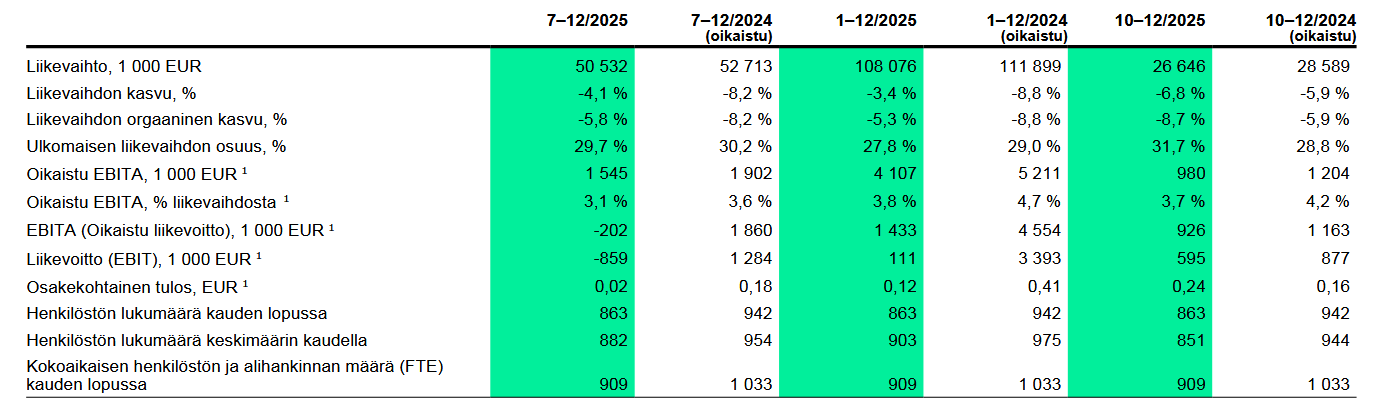
Siili’s revenue decreased by 7% to EUR 26.6 million in Q4, which was below our forecast of EUR 28.2 million. Organically, revenue decreased by 9% (forecast -3%). The quarter had one more working day than the comparison period, which we estimate supported revenue by just under 2%. Revenue was weighed down by the postponement of customers’ investment decisions. This has been a challenge across the entire IT services sector for a couple of years now, making the management of utilization rates challenging. However, the relatively strong decline in revenue is concerning, and it would be important to see it turn around.
Geographically, the share of international revenue was 32% in Q4 based on our calculations (Q4’24 29%). Thus, international revenue grew by ~3%. Based on our calculations, revenue in Finland decreased by 11% (organically 13%), which is clearly a weaker performance than the sector.
Here are Joni’s pre-comments regarding Siili’s Q1 report to be published on Tuesday, April 28th
We expect the company’s revenue decline to have continued in the early part of the year, as the market situation has remained challenging and demand for traditional software development has been weak. We estimate profitability to settle at a low level, although previously implemented efficiency measures do support the operating result. In the report, our attention will be particularly focused on comments regarding the development of the demand situation and signs of a possible turnaround in the revenue trend.
The primary reason for the decline in revenue and profitability is the slower-than-anticipated progress of the AI transformation, as well as the loss of individual client accounts and a decrease in revenue toward the end of 2025. The market has developed more weakly than indicators in the fall suggested, and AI investments by Finnish companies continue to lag significantly behind the level of the rest of Europe. Data and AI projects and international ventures realized during the early part of the year have confirmed that our strategic direction is correct. However, scaling still takes time. For this reason, we have initiated measures to ensure profitability and adjust costs.
Improving profitability requires a return to a growth path, and ensuring this is our top priority in the coming quarters. To ensure profitability, we have, among other things, initiated change negotiations (muutosneuvottelut) regarding layoffs. However, cost adjustments alone do not solve profitability challenges in a business where value is created by the work of experts for clients. Our focus is therefore on accelerating sales, concentrating our offering, and strengthening the most critical areas for growth, such as the Managed AI business and international accounts. At the same time, we are adjusting our cost structure to match current demand levels while securing the prerequisites for growth.
I read these two paragraphs from the report four times and I still don’t understand at all what they are trying to say. Luckily the strategy is correct.
A return to the growth path of temporary layoffs is a prerequisite for profitability.
Well, I guess what they’re really trying to say is that things are going poorly because Finnish companies aren’t yet investing enough in AI, but let’s hope and believe that the investments will eventually come and we’ll be ready when they do. Temporary layoffs will likely allow them to keep the experts on board. Permanent layoffs would drive expertise away, and there has been a lot of investment in employees’ AI skills recently, so they don’t want to let that investment go to waste.
Yeah, a CEO change would probably be appropriate by now. They’ve reacted too slowly to profitability issues. The stock has fallen about 55% in a year to near ATL levels, even though revenue is only down about 15%. There are good chances for a profitability leap, even though demand has contracted.
00:00 Start
00:12 Q1 highlights
01:33 Revenue development by region
02:54 Reacting with change negotiations
04:24 Cost structure and efficiency measures
06:54 Recipe for improving sales
07:34 Meeting guidance
09:24 What would make the CEO increase his ownership?
 He prepared the report regarding the technical downward EBITA guidance.


 Luckily the strategy is correct.
