Reaktor - is the consulting firm also becoming a software company?

Reaktor Group Oy plans an initial public offering and listing on the regulated market of Nasdaq Helsinki

Reaktor Group Oy (“Reaktor” or the “Company”) announces that it is planning an initial public offering (IPO) and the listing of its shares on the regulated market of Nasdaq Helsinki Ltd (“Nasdaq Helsinki”) (the “Listing”). The planned IPO is expected to consist of an offering of the Company’s new shares (“New Shares”) for subscription in a share issue (“Share Issue”), and in addition, certain existing shareholders of the Company are expected to offer existing shares in the Company for purchase (together with the Share Issue, the “Offering”).

Reaktor is a Finnish globally operating technology company that designs, develops, and sells software products and digital solutions. Reaktor’s three-pronged value creation model consists of i) a scalable software product business, ii) a recurring technology solutions business serving customers across Reaktor’s eight business units (Aero, Retail, Gaming & Entertainment, Healthcare, Industrial, Defence & Security, Cross Industries, and Public Sector), and iii) the Reaktor Ecosystem venture business, where the Company co-founds and invests in new technology companies.

Information about the Offering

The planned Offering is tentatively expected to consist of (i) a public offering to private individuals and entities in Finland, (ii) an institutional offering to institutional investors in Finland and, in accordance with applicable laws, internationally outside the United States, and (iii) a personnel offering to the employees of the Company and its subsidiaries. Reaktor, certain Reaktor shareholders, members of Reaktor’s Board of Directors and management, and Reaktor employees participating in the planned personnel offering are expected to commit to customary lock-up arrangements.

The objective of the Offering is to enable the implementation of the Company’s growth strategy, provide the Company access to capital markets, and broaden its ownership base with both domestic and international investors, which would increase the liquidity of the Company’s shares and strengthen the Company’s reputation and brand awareness. The Listing and increased liquidity would also enable the more efficient use of the Company’s shares as consideration in potential acquisitions and in personnel incentive schemes.

Reaktor aims to raise gross proceeds of approximately EUR 20 million through the Share Issue by offering New Shares for subscription. The proceeds from the Share Issue are intended to be allocated to three key areas in accordance with the Company’s strategic objectives:

  • building the software product business, primarily by investing in the Defence & Security business unit, evaluating opportunities to spin off defense and security products for civilian use cases, and productizing consulting work in other business units;

  • international and domestic expansion organically and through selected acquisitions; and

  • accelerating the growth of the Reaktor Ecosystem venture business.

Ilmarinen Mutual Pension Insurance Company, Mariatorp Oy, assets managed by WIP Asset Management Oy, certain funds managed by Sp-Fund Management Company Ltd, Danske Invest Finnish Equity Fund, and Aktia Fund Management Ltd on behalf of the funds it manages (together the “Cornerstone Investors”) have, subject to certain conditions, committed to subscribe for shares in the Company for a total of approximately EUR 45 million in the planned Offering, assuming that the enterprise value of the Company’s entire share capital before the execution of the Offering is at most EUR 190 million.

Mika Sutinen, Chairman of the Board, comments:

“The rapid proliferation of artificial intelligence is a significant driver for future market growth in the technology industry. It creates entirely new opportunities for digital product development. In the long term, the digitalization of society and large-scale transformation projects in companies also bring interesting growth opportunities. We on the Company’s Board believe that Reaktor has a strong position in this market: established customer relationships, an international footprint, and an operating model designed to deliver results. A potential listing would support Reaktor’s next growth phase and strengthen its capabilities to capitalize on the market’s long-term opportunities.”

Pekka Horo, CEO, comments:

"Over 25 years, Reaktor has built technology expertise that combines deep engineering skills with genuine business understanding. We believe our value lies in supporting the achievement of our customers’ goals, not just in software development.

For example, we have developed software products for the defense and security sector that have proven their worth in critical environments, and we have integrated AI as part of our entire delivery and are constantly building AI solutions with our customers.

A potential listing would be a means for us to increase our ability to serve our customers and expand our operations into new markets. A potential listing would be a way for us to develop our scalable software product business, strengthen our international technology solutions business, and accelerate the growth of the Ecosystem business."

Reaktor in brief

Reaktor is a Finnish globally operating technology company that designs, develops, and sells software products and digital solutions it considers pioneering. Reaktor operates through a three-pronged value creation model consisting of i) a scalable software product business, currently comprising NATO-compatible defense software products offered in the defense software market, as well as ongoing productization projects in other business units, ii) a recurring technology solutions business that operates globally and serves leading customers with comprehensive digital solutions across Reaktor’s eight business units: Aero, Retail, Gaming & Entertainment, Healthcare, Industrial, Defence & Security, Cross Industries, and Public Sector, and iii) the Reaktor Ecosystem venture business, where the Company co-founds and invests in new technology companies, complementing Reaktor’s core offering and expanding its capabilities through a portfolio of over 45 companies.

Reaktor sells its technology solutions and software products in several geographic areas, including Europe, the United States, Japan, Hong Kong, and Australia. In 2025, approximately 62 percent of Reaktor’s revenue was generated in Finland and approximately 38 percent from international business. Reaktor aims to increase the share of international revenue from its current level. As part of its international expansion, Reaktor has established offices operating outside Finland in Amsterdam, Lisbon, New York, and Tokyo. These offices, along with offices located in Helsinki, Tampere, Turku, and Seinäjoki, serve global customers across multiple geographic regions.

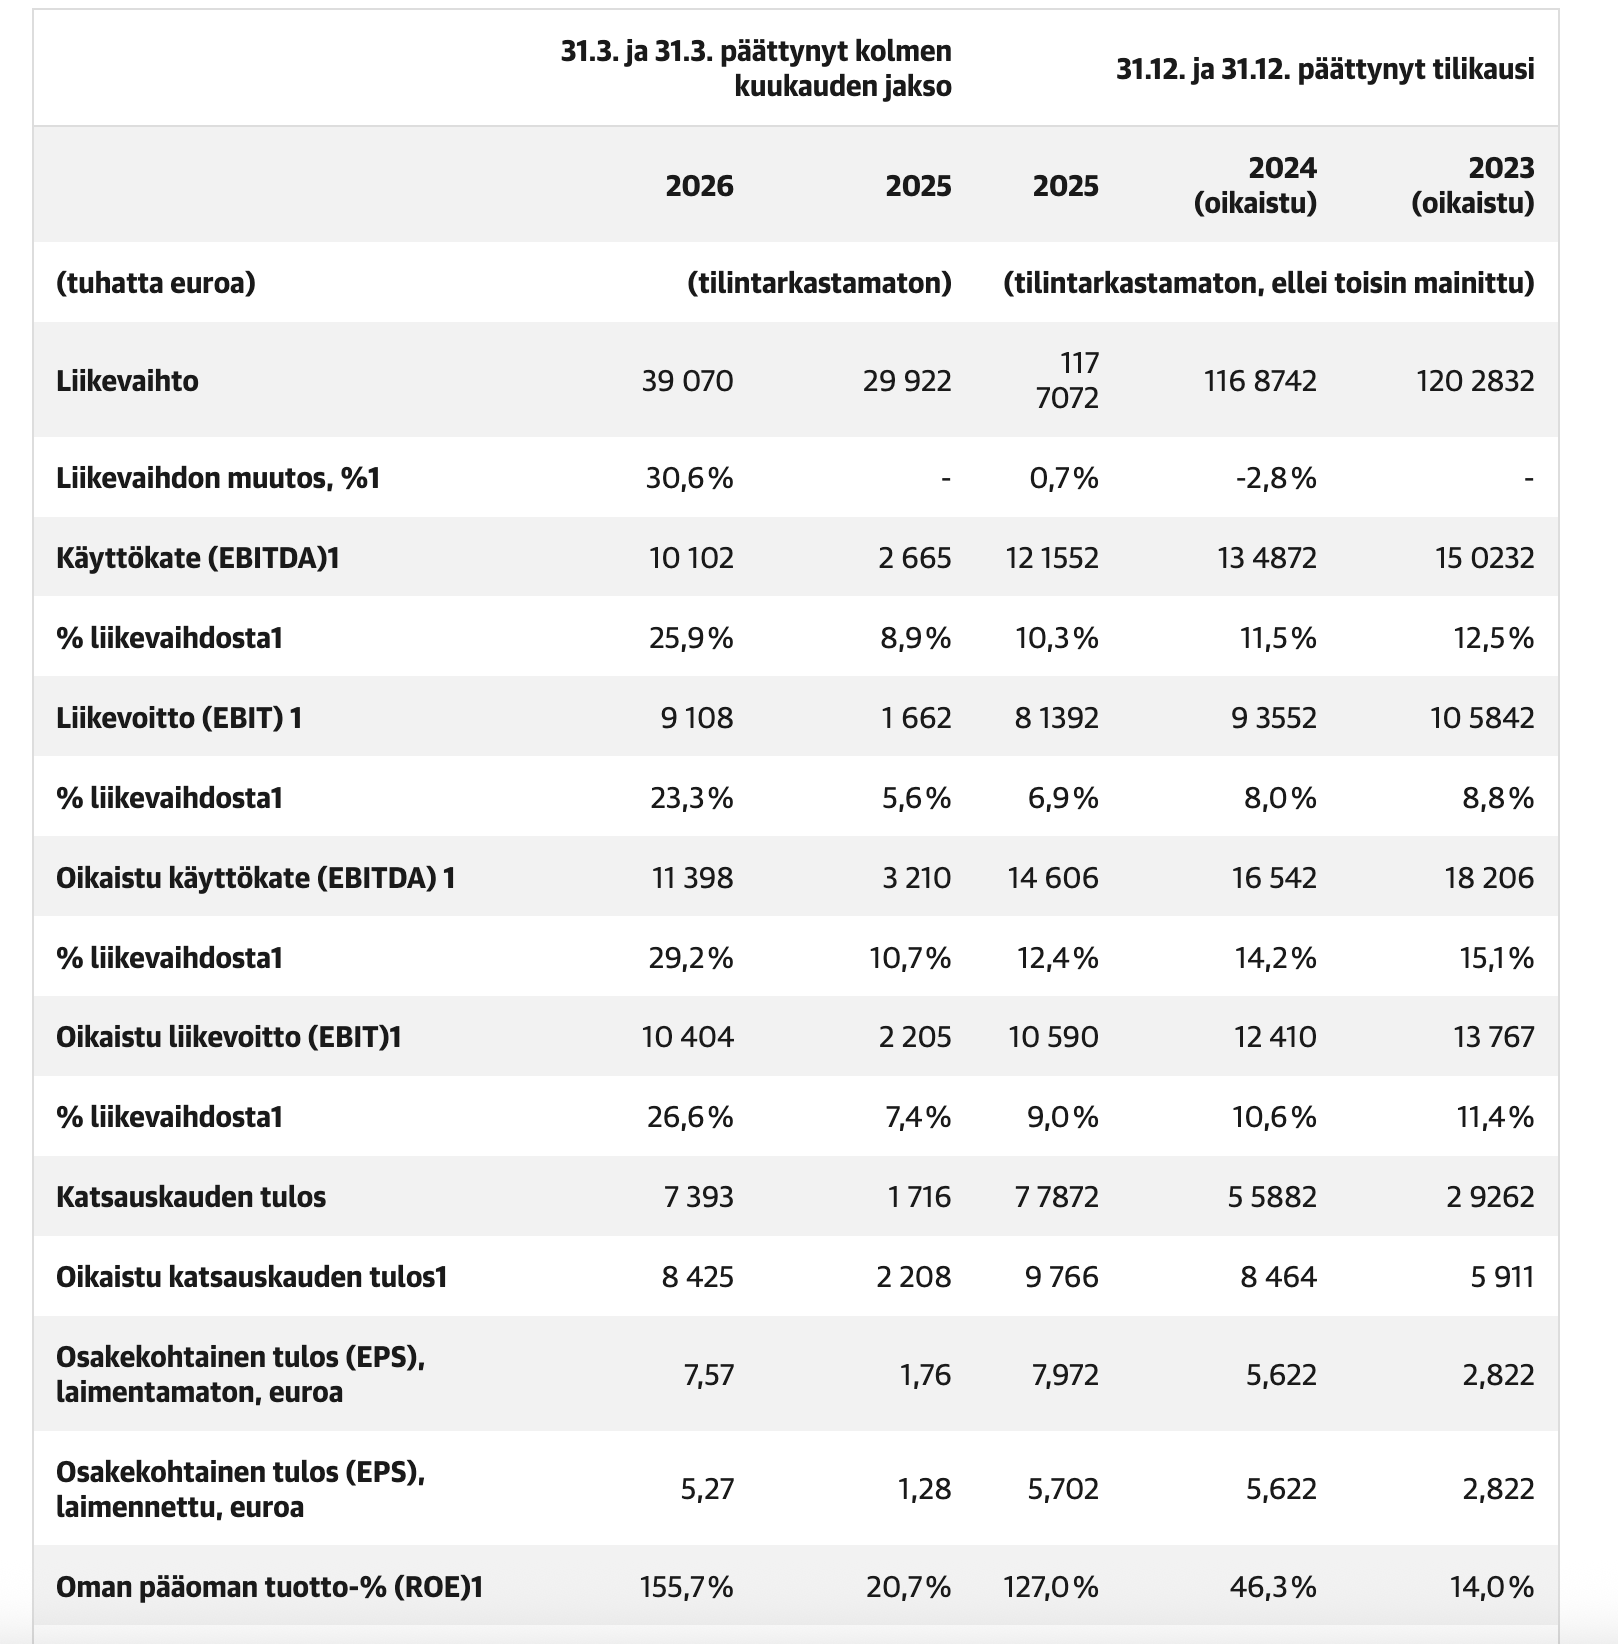
Reaktor’s competitive position is built on the principle that its value lies in supporting the achievement of customers’ goals, not just in software development. The Company’s personnel combine strong consulting expertise with AI specialization and deep technical knowledge. Reaktor’s deep industry-specific expertise and ability to deliver end-to-end solutions enable Reaktor to identify high-value-added business opportunities and implement them through design, technology, and change management.The company’s revenue in 2025 was 117.7 million euros (2024: 116.9 million euros; 2023: 120.3 million euros), operating profit (EBIT) was 8.1 million euros (2024: 9.4 million euros; 2023: 10.6 million euros), and adjusted operating profit (EBIT) was 10.6 million euros (2024: 12.4 million euros; 2023: 13.8 million euros). The company’s operating profit (EBIT) margin in 2025 was 6.9 percent of revenue (2024: 8.0 percent; 2023: 8.8 percent) and the adjusted operating profit (EBIT) margin was 9.0 percent of revenue (2024: 10.6 percent; 2023: 11.4 percent). The company’s cash conversion in 2025 was 69.8 percent (2024: 103.9 percent; 2023: 114.7 percent). The company’s free cash flow from operations in 2025 was 10.2 million euros (2024: 17.2 million euros; 2023: 20.9 million euros). Reaktor had 712 employees at the end of 2025.
Webinar at 10:00 AM

40 Likes

Finally. If anything, this is what I’ve been waiting for.

I’ve been watching Reaktor mature from the sidelines, and now, with the AI wave, it’s a good time to go public. I suspect the IPO price won’t be on the cheapest end, but I think I’ll be getting on board with this one.

6 Likes

So, the Q1 books have been cooked in a way that makes a company that’s been spinning its wheels for 3 years look like it has AI potential. Then, suddenly, when AI tool costs rise next year, everyone will be surprised: “Wait a minute, this is just an IT consulting firm.”

There were change negotiations in the fall to prep for this, but we’ll see if they try to squeeze personnel costs even harder if tool costs triple this year.

Big chuckle at the Palantir comments :smiley:

50 Likes

Helsingin Sanomat reports with an interesting angle:
Reaktor to become the Helsinki Stock Exchange’s first AI IPO

To me, it’s just another consulting firm like any other. The most interesting part is that “Ecosystem” and when its contents start being revealed to the public.

19 Likes

The golden era for IT consulting firms on the stock exchange was 2021, which would have been a much better time to go public. Perhaps Reaktor’s management is banking on the idea that by saying “AI,” investors will be willing to pay a multiple in valuation compared to their competitors.

20 Likes

A software company hitting the stock market at the peak of the AI bubble with AI multiples. Owners pocket the cash, and for everyone else, it’s the usual First North “success story” ahead. Reaktor WAS the best software company in Finland in the early 2000s, with the toughest talent, but now the firm has ballooned into a 700-employee consulting house, branched out all over the place, and is now trying to play Palantir. A software firm trying to brand itself as an AI company, and even though they are a strong player in that field, the core business is melting away. When the AI bubble bursts, this will be the first one to hit the deck.

12 Likes

In a way, I hope that fear takes over and the valuation remains more moderate even after the opening. Then I could jump in.

But if this actually starts to be priced like a bubble, then I’ll just have to settle for watching from the sidelines.

I really have to remind myself as well that if Reaktor had been chasing a bubble valuation, there would have been an excellent opportunity for an IPO back in 2021.

6 Likes

It is stated / claimed there that the 2023–25 revenue consists almost entirely of technology solutions, and in 1Q2026 the software business is €8.6 million—meaning that massive 1Q2026 growth comes after the 2023–25 stagnation.

An incredible start from scratch, or something special?
Perhaps @Iikka_Numminen can clarify this in the interview, and also check the table in the opening message for extra digits that seem to have appeared in the superscripts of the figures/results.

Almost all of the Company’s revenue and operating profit (EBIT) has been generated from the technology solutions business during 2023–2025, which is why software product business revenue has not been reported separately. In the future, the Company expects to increase the share of the software product business in the Company’s revenue and operating profit (EBIT), and the Company’s revenue (and operating profit (EBIT)) will consist of revenue (and operating profit (EBIT)) from the technology solutions business3 and the software product business. In the first quarter of 2026, the organic revenue4 of the technology solutions business was €30.4 million and the revenue of the software product business was €8.6 million.

2 Likes

Yeah, it’s hard to believe that 8.6m/3 worth of MRR was slammed in there, so perhaps there are some deployments or other one-off items involved.

1 Like

This has been kicked around before; they own a good chunk of, among others, Witted Megacorp. They could just enter the stock exchange through the back door with a small corporate restructuring.

2 Likes

Someone who actually knows Reaktor well could explain what makes Reaktor an AI house.

After all, practically every IT consultancy has rebranded itself as such by early 2024 at the latest, even though the reality is something else entirely. Perhaps they use GitHub Copilot, and the more advanced ones might even use Codex or Claude Code. But in reality, there isn’t much more AI in internal processes than that (i.e., scaling is still based on headcount), maybe a handful of experts understand AI at a fundamental level (because basic MVC software dev doesn’t automatically translate into AI Engineering expertise), let alone understanding the customer base’s operations well enough to offer directly productized AI solutions for typical problems.

Reaktor has remained a bit distant to me, so it would be great to hear some insider information on what kind of credentials this IT consultancy is using to call itself an AI house this time around.

22 Likes

In short: Nothing. If a software firm claims to be an AI house, then they simply are, because that’s what they declare.

In all seriousness, Reaktor has been involved with AI for years and has invested heavily in its operations. It says something that Reaktor created the “Elements of AI” course, familiar to many of us, together with the University of Helsinki back in 2018.

Reaktor’s Data and AI Director, Marko Aalto, visited the HS Visio podcast in January.

“The AI maturity of an organization, team, and developer varies greatly. In those teams that have used these tools for, let’s say, at least six months, the majority of the code—50 to 90 percent—is starting to be produced by AI tools.”

10 Likes

I watched the press conference and will probably participate in the offering with a “touhutonni” (a thousand euros). Presumably, this will be oversubscribed, and in the end, only small crumbs will be allocated. Things that worry me:

  • Reaktor has many old owners who haven’t been involved in any way for ten years. There will surely be selling pressure at the start; their acquisition prices are cents, so it won’t matter to them if they get rid of the shares slightly below the IPO price.
  • The Q1 2026 result seems a bit pumped since this license sale hit that period.
  • The product business in general is suspicious. There are few consulting firms that successfully produce product business on the side. Vincit has been trying to revive its product business on the First North (FN) for ten years without success. This revival has then been funded by the cash flows of the consulting business.
  • The Ecosystem and its future is a question mark. Is the intention in the future to buy and merge these companies into the group, or will the current operations continue?
15 Likes

In terms of numbers, this is certainly part of the Finnish IT elite. They talk about industry expertise and being at the core of their customers’ strategies, unlike others. AI is, of course, mentioned multiple times, just like every taxi driver does these days. Personally, I’ll check the IPO price and the valuation multiples before jumping on board. There are really cheap IT companies available in “Hesuli” (Helsinki Stock Exchange) right now, and it’s hard to believe that Reaktor would be so much better in the long run that it would justify paying a (presumably) multi-fold premium compared to others.

It seems Witted has no role in the listing after all. This was rumored 1-2 years ago.

4 Likes

Let’s take note of the CEO’s comment from the HS article linked above. A strong statement, if it’s based practically only on the beginning of the year… Hopefully, we won’t have to revisit this in the coming years.

“We are at a very good growth pace,” says Reaktor’s CEO Pekka Horo.

6 Likes

It will be interesting to see at what price it hits the market. I wouldn’t really pay higher multiples than those of Gofore or Digia. There are also fairly affordably priced growing peers in the international markets, even if they can’t leverage a strong, rapidly growing domestic market like Finland.

8 Likes

The anchor investors have committed to subscribing for 45 million, provided that the pre-money valuation does not exceed 190 million, so it’s likely that 190 million will be the pre-money valuation for the IPO.

8 Likes

Agile-native houses like Reaktor stand to benefit from the AI work trend, if and when they know how to leverage it.

In the previous agile model, high-paid IT consultants had to be moved from the “bench” to billable client work on-site, which was done by coding. Teams went to code within the client’s organization and integrated more or less effectively through an agile working model where code is constantly improved—ideally using DevOps models directly into production without the wait times of the waterfall model.

In the AI work model, a team equipped with new types of capabilities must also be moved off the “bench” and back into client spaces, but it’s no longer just about coding; it’s about reinventing AI work. AI work includes, for example, connecting Claude Cowork and agentic AI workers to the client’s databases and workflows. At the same time, the capabilities of staff in both Reaktor and the client company are elevated. Those who do not “androidize”—i.e., raise their capability level—may find themselves looking for a place outside of these organizations. This increases margins for both Reaktor and the client companies. The same tasks can be performed, perhaps even better, by people other than just coders. It is more important to understand value creation processes; coding skills are easier for an intelligent person to acquire anyway, as Anthropic, OpenAI, and Google are such excellent inference engines and improve every week.

It remains to be seen how well Reaktor specifically can execute this. There are even tougher firms globally, though they likely won’t bother with Finland. However, I think it’s great that in 2026, AI work is finally being done for real, rather than remaining stuck in hallucinations that AI inference cannot enrich, let alone replace, work. The future is already here, it’s just not evenly distributed! :rocket:

11 Likes

In my opinion, the view above sees Reaktor as the only company in Finland that has planned or is even to some extent conducting AI-based business. This perspective only acknowledges Reaktor, even though other companies in the same industry are largely doing the same things and are roughly at the same stage regarding the use of AI—some perhaps even ahead.

Based on following IT industry media and job advertisements, companies like Digia, Tieto, Loihde, F-Secure, and CGI are also highlighting AI-based business models and mentioning it in their job postings.

The general “rule of thumb” feeling is more that AI (wherever the client permits its use, e.g., not in all public sector accounts) has already been adopted quite extensively. A few examples include Digia, Tieto, CGI, Loihde, and F-Secure, which have also had articles about this in the media.

5 Likes

As I wrote above, it is one thing to bring up AI in every context and brand yourself as an AI house. Indeed, almost all IT consulting firms both here and globally have done this, to put it bluntly, starting from 2024 at the latest.

Then it is a completely different matter to truly be an AI company. And at least in my books, none of the Finnish publicly listed companies pass my screening for AI company classification—despite the energetic branding—at least not yet.

There are AI houses in Finland that pass my screening. Silo is the most obvious one, but there are also many emerging smaller ones like Agion, Brillian, Rework, etc., which have built their entire business to be AI-native.

In my day job, I am exposed to these AI promises from IT consulting firms, and in my opinion, there is invariably a huge gap between the branding and the actual operations. That is why I am also somewhat skeptical of Reaktor, although I admit it has remained more distant to me compared to many other industry peers.

13 Likes