As I understand it, Qt is a heavily shorted stock at the moment. Is there a specific reason for this, and what kind of effect does this have on the stock’s value?
3 Likes
Luiro has commented on how Qt is performing as expected with this IAR acquisition. 
27 Likes
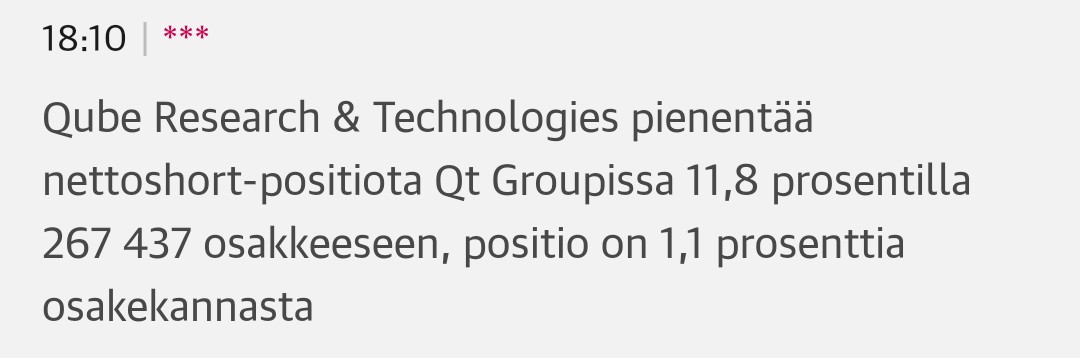
Smart move by Qubel to cover part of its short position. I wouldn’t want to hold a short position for too long.
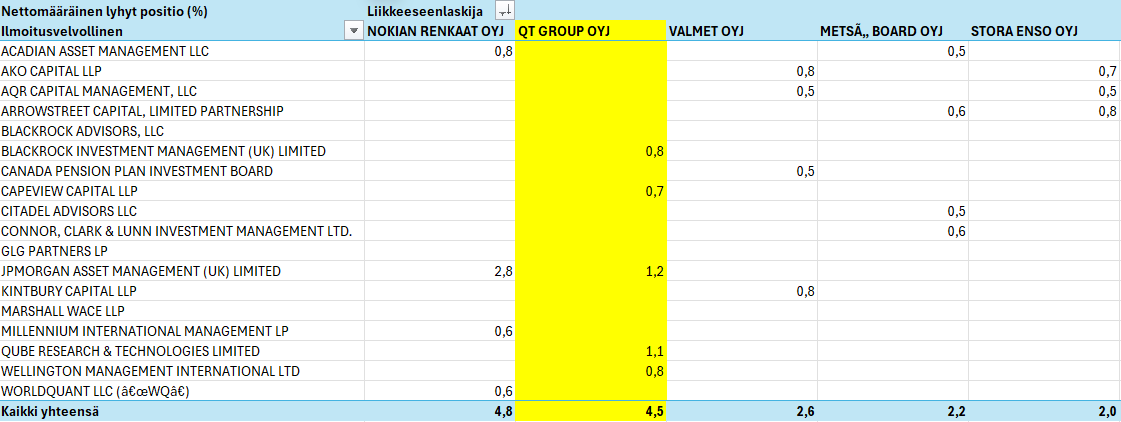
You can track short positions from FIVA. Some are missing, however, positions under 0.5%.
The data can be downloaded to Excel via the link at the bottom of the screen, where sums can be calculated. According to this, the sum of Qt’s positions is the second largest, right after Nokian Tyres.
8 Likes
In my opinion, a long-term investor should consider short-seller positions mainly as an indicator of market sentiment, and certainly not as a direct basis for buying or selling. In my opinion, Qt’s situation is currently attractive for the following reasons:
- The worst tariff fears subsided in Q3. The tariffs announced initially were so brutal that customers’ product development departments went into a kind of panic mode and did not want to make any investment decisions. Now, they know how to live with the situation.
- Positive news has emerged during Q3: the IAR deal, Suzuki collaboration, Qt for MOSA release, etc.
- If one considers the short game, the Q3/2024 comparison period was not nearly as tough as Q2/2024. It is possible that Qt has now closed bigger deals in Q3.
- The CEO + Chairman of the Board own so many shares that there is certainly a desire to get the share price back on an upward trend.
- The stock has been trading sideways for 5 years, which means the valuation level has come down brutally. I personally do not understand at all why QT should be priced at these multiples.
45 Likes
You can’t necessarily draw that conclusion from it. If they wanted a strong rise, then they would be planning to sell at some point and possibly make an exit. I’m sure they earn well enough that if they want to continue in their jobs, the share price shouldn’t have a very big significance.
6 Likes
Additionally, it’s good to remember that stock-based compensation is an important part of the chairman of the board and CEO’s compensation structure in practically all listed companies, and a favorable development in the share price practically always indicates well-managed business operations and value creation. Correct me if necessary, but even Nokia’s executives seemed to have decent stock holdings in the company as a result of SBC, yet it didn’t encourage them to innovate those damn touchscreens for phones…
The share price or business development does not progress favorably just because the chairman of the board or CEO wants it to.
The valuation was sky-high 4-5 years ago, and it was quite healthy for the air to be let out of the stock. It’s another matter whether the current valuation is too low; however, EPS is predicted to decrease by about 20% this year compared to last year, which indeed makes many question the continuity of growth in the coming years.
As a bull myself, my view is that if EPS doesn’t start growing, the valuation is still high. If, on the other hand, growth resumes in 2026 (even with the predicted growth rate), then the stock is cheap.
17 Likes
A few years ago, I pondered a scenario where Qt developer licenses would be free:

Qt would then become the de facto environment for AI code agents, schools, and others.
Sales revenue would dip for a few years, but we would get it back with interest as the volumes of distribution licenses and the sales of QA and other ancillary products would go through the roof like the revenue forecasts of quantum firms. Salespeople could also be cut.
Well, such a decision will naturally not be made (developer licenses account for almost half of the company’s total sales!), but it’s a fun thought experiment.
My guess is that Qt, as a relatively liquid stock, is part of a broader basket of cloud software, and shorts move according to the industry. SaaS companies have long been pressured by the narrative that AI-driven coding will take away their business.
Below are Qt (green), BVP Nasdaq Emerging Cloud Index (blue), and Nasdaq (orange) since 2022.
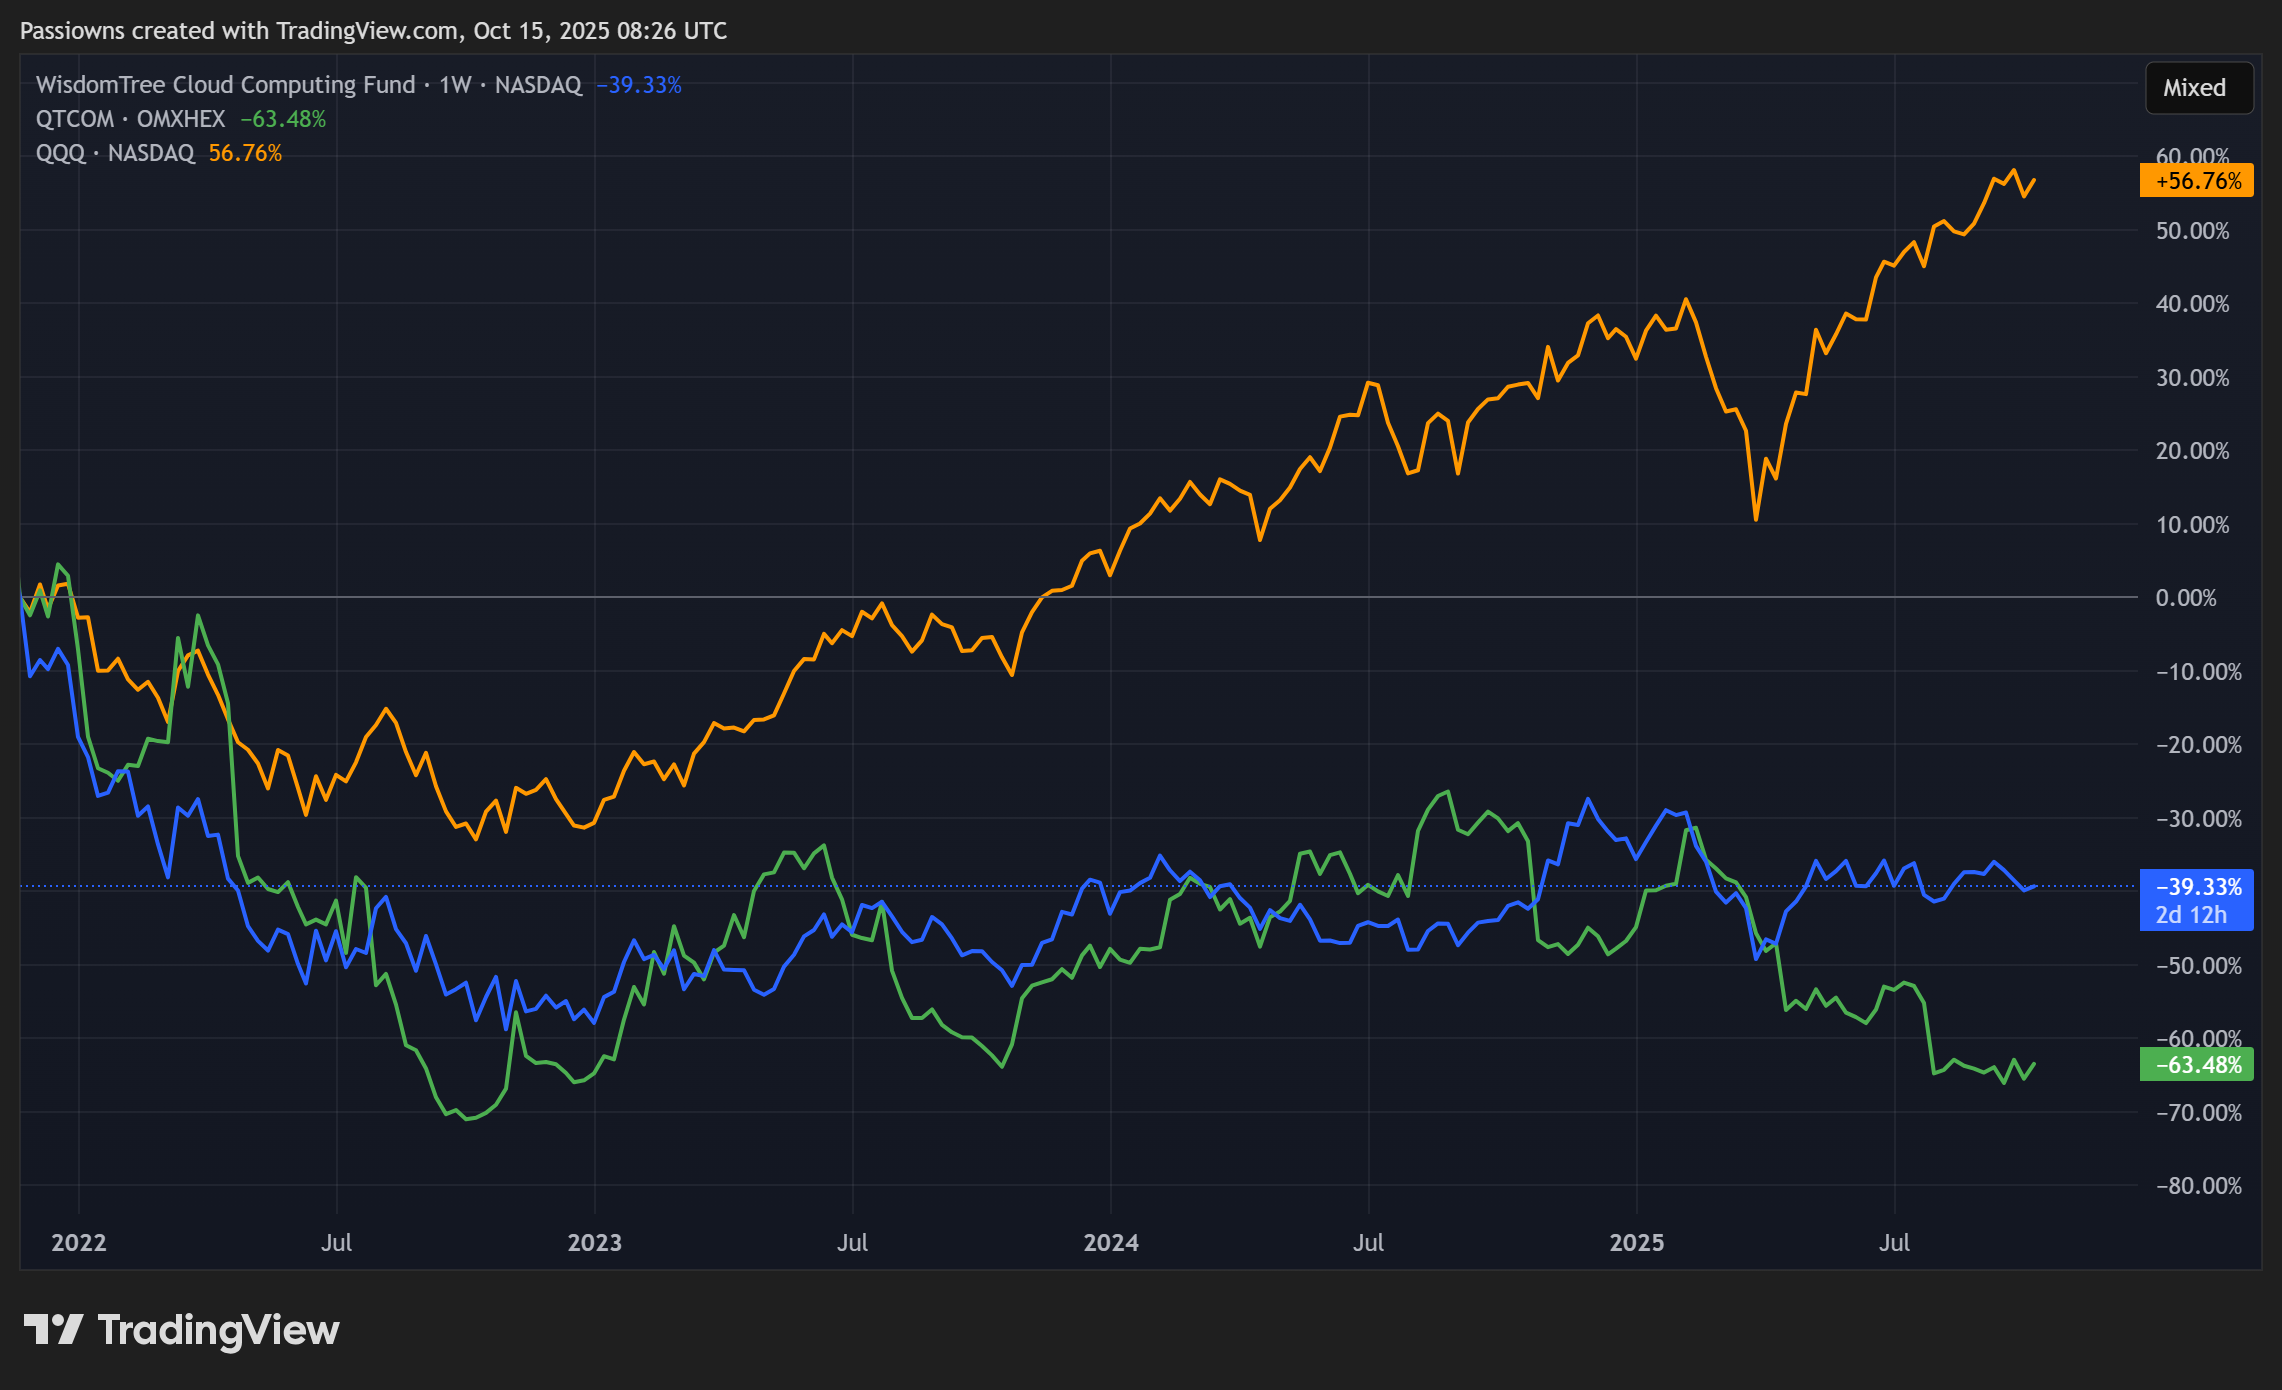
Of course, the company’s own (weak) performance is the most important factor affecting the share price, as seen from the slump in the last six months.
39 Likes
Qt Group Plc lowers its financial guidance for 2025. A change in Qt Group’s customers’ purchasing behavior, caused by general economic uncertainty, has significantly slowed down revenue growth in all areas of the company’s business. Contrary to expectations, larger license deals worth several million euros have not been concluded during the third quarter. The company estimates that the average size of deals will not significantly increase during the remainder of 2025 either.
In addition to weaker-than-expected revenue growth, one-off costs resulting from the acquisition of IAR Systems Group will negatively impact Qt Group’s full-year EBITA margin (EBITA-%).
New outlook for 2025:
We estimate that full-year 2025 revenue will grow by 3-10 percent year-on-year in comparable currencies, and that the EBITA margin (EBITA-%) will be 20-30 percent in 2025. The financial guidance includes the estimated impact of the IAR Systems Group acquisition on Qt Group’s revenue and operating profit for the remainder of the year.
Qt Group will specify its estimate of IAR’s impact in connection with the January-September 2025 interim report.
56 Likes
3-10% revenue growth INCLUDING some positive impact from the acquisition.
In the 2024 financial statement release:
”Outlook 2025
We estimate that full-year 2025 revenue will grow by 15-25 percent year-on-year in comparable currencies and that the operating profit margin (EBITA-%) will be 30-40 percent in 2025.”
The business environment is difficult, but we have fallen far from the February outlook 
51 Likes
Unfortunate, but a very expected thing. Good that they announced it this early. Will the purchase location open today? #35ecua
10 Likes
We are operating with quite wide forks when there is less than 2.5 months left of the year.
And a hefty drop in guidance when compared to the old one
Previous outlook for 2025 (given on April 23, 2025):
We estimate that full-year 2025 revenue will grow by 10-20 percent from the previous year in comparable currencies and that the operating profit margin (EBITA-%) will be 30-40 percent in 2025.
Qt Group Plc will publish its interim management statement for January-September 2025 on October 30, 2025, at approximately 1:00 p.m. and will provide more detailed information on the financial performance of the third quarter of 2025 therein.
21 Likes
Didn’t Varelius say that all deals were already in the pipeline for the rest of the year? That was quite a fabrication in connection with Q2.
72 Likes
That man has lost his credibility. So many times he has promised the moon. The truth has been different.
70 Likes
I.A.R.'s revenue in Q4 last year was approximately 132 MSEK (~12 MEUR). This year, revenue has been flat, so let’s assume the company will generate that much revenue this year as well.
Qt estimates that it will complete the acquisition on 3.11. Thus, the revenue coming from IAR to Qt this year could be 66%*12 MEUR=7.92 MEUR.
This would result in approximately +3% inorganic revenue growth for Qt this year.
In relation to this, Qt guides, in my opinion, that its own business will grow 0-7% this year. Assessing profitability is more difficult because there are one-off expenses involved.
23 Likes
Yeah, as was written in connection with the previous result, this was very much expected. And it actually just makes me wonder why this wasn’t done already then, as H1/25 was much weaker than H1/24.
The midpoint of the new guidance for EBIT is 55.7 M €, so I would say that, for example, Inderes’ forecasts are overstated by about 11 M €. A harsh drop, and the target of just over 39 € that I mentioned earlier now seems quite realistic.
33 Likes
Where does this 66% come from? A poorly slept night and my mind is blank, is there a decimal error there?
1 Like
Will distribution licenses even turn into money as expected? It feels like Qt’s growth still depends only on developer licenses. Won’t distribution licenses deliver that hockey stick growth? It seems Qt is only playing ringette.
9 Likes