Do you think that if Qt’s profitability is +30% EBIT with a turnover of €250m, its valuation is still challenging?? How do you actually approach your analysis? In the same way one prices raw material companies at the peak of a cycle with a single-digit P/E?
Or are you expecting all technology companies to transform into commodity companies via AI? I’m genuinely interested in hearing your reasoning
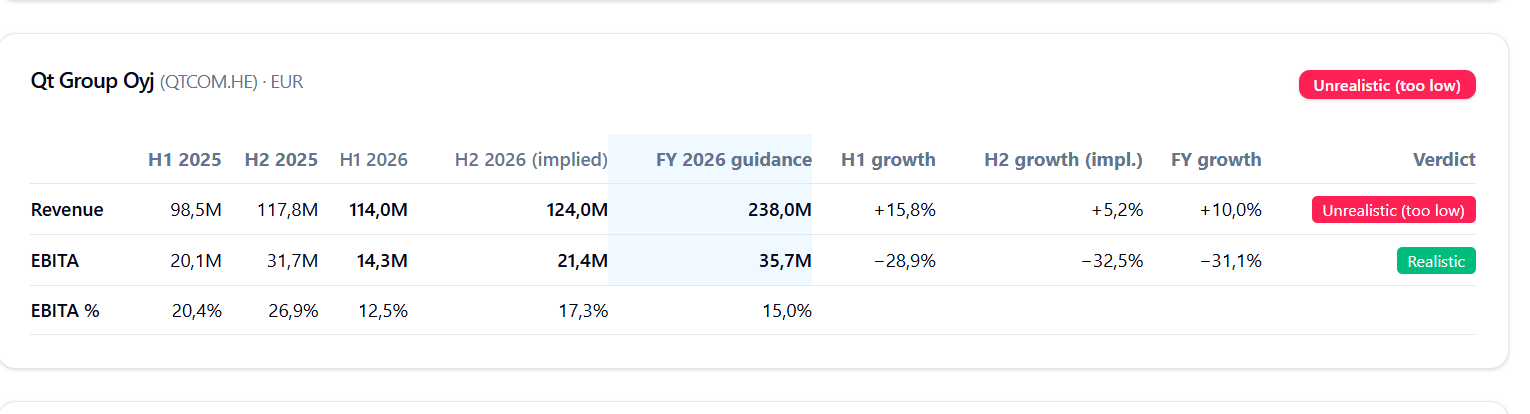
The earnings report didn’t convince me, but reaching the lower ends of the guidance doesn’t seem very unrealistic in light of the figures below.
If we use the “at least” figures from the full-year guidance, a 10% increase in revenue and a 15% EBITA result in the following full-year figures: Revenue €238M and EBITA €35.7M.
Regarding revenue, the guidance is on the conservative side, and for EBITA, it is realistic.
I am considerably more optimistic about the outlook for the next 1.5 years. Admittedly, I went “all in” at the 18–22 euro levels, so I am a bit biased. Here is my own summary of the positive drivers. Nothing new here, of course, if you have been reading the reports closely.
In my opinion, a major risk is associated with the success of the IAR integration and the Qt culture, now that they have started cutting costs and laying off people in a significant way for the first time. Will key personnel leave if the general mood in the company declines?
Qt’s positive drivers for H2/26 and 2027
H2/26:
The profitability program is only now starting to have a full impact: Q2 adjusted EBITA-% was already 22.2% excluding 4.3 MEUR in one-off costs. On top of that, the discontinuation of IAR’s cybersecurity business adds ~3 MEUR in savings with no impact on revenue.
The guidance (growth >10%, EBITA-% >15%) looks conservative after Q2, with room for an increase later in the year.
Demand is recovering: Q2 +20.9% in comparable currencies; new sales were strong, ARR +32%. Organically, it is still modest, but the company isn’t priced as a growth stock (yet).
2027:
IAR’s transition to a subscription model is turning from a headwind into a tailwind and is clearly ahead of target (68% transitioned, the target was 40%).
Earnings leverage opens up: savings at full weight + growth with a fixed cost structure → Inderes forecasts EPS of 1.53 → 2.51 € (+64%).
2027e EV/EBITA ~10x and P/E ~16x — still modest for accelerating earnings growth.
Figures from the Inderes Q2 report (Aug 7). My own target price by the end of 2027 is 48e/share. Let’s see how it plays out.
I agree about the integration; it requires skill and patience. On the other hand, cost-cutting and change negotiations can even improve the atmosphere and culture, because in a company that has grown long and fast, it’s easy for 5% of the staff to be people whose departure is positive for everyone—the person leaving, the company, and those who remain.
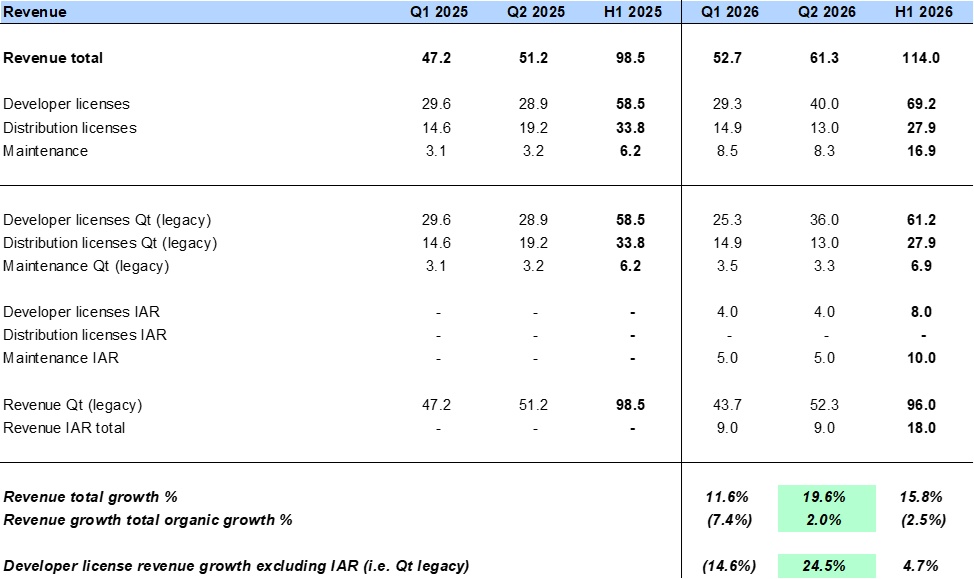
Now that I’ve taken a closer look at the Q2 2026 earnings report, my rough estimate is that revenue from Qt’s “legacy” development tools—that is, excluding IAR—grew by approximately 24–25% year-over-year in Q2.
It’s true that you can’t draw too many long-term conclusions from a single quarter in Qt’s case, but that level of growth was certainly a positive surprise and raises the bar compared to previous quarters. One would assume there are some larger deals behind this as well.
Note: In this analysis, development tools also include quality assurance.
Where did you find the IAR figures? I personally couldn’t find them with that level of precision in that report.
For 2025 H1, IAR’s figures were €21.2M and the adjusted operating profit was €3.8M. If your figures are even close, that’s a €3.2M headwind in revenue, and the assumption is that a significant portion of that lost revenue hits the adjusted operating profit directly.
Quickly calculated, the impact of IAR would have been -2–3% on revenue, with its contribution to profit being almost negligible. One can only hope that this is due to the billing model and not because the business is melting away. On the other hand, the “old” Qt’s performance would have been quite decent once again.
I have made a rough estimate based on publicly available information. In my opinion, various data points are quite readily available, making it possible to make an estimate in the right direction.
Looking at the figures previously reported by IAR, we can see the following:
Q1 2024 - Q2 2025 revenue has been consistently between 109 MSEK and 132 MSEK.
Q1 2025 revenue: 124.2 MSEK, i.e., approximately 11 MEUR.
Q2 2025 revenue: 109.4 MSEK, i.e., approximately 10 MEUR.
Qt commented the following in their release: Based on Qt Group’s and IAR’s financial statements for 2024, IAR would have added approximately EUR 43 million in net sales and approximately EUR 15 million in EBITDA to Qt Group. That is roughly 10.8 MEUR in revenue per quarter.
Prior to the acquisition, Qt maintenance sales were consistently around 3 MEUR per quarter (Q1 2024-Q3 2025 range of 2.9m-3.2m). With Qt’s subscription business model (“SaaS”), the focus is not on maintenance revenue. The situation is different for IAR, as the subscription/SaaS transition is ongoing. After the IAR acquisition, Qt’s quarterly maintenance sales grew to a level of about 8.2-8.5 MEUR, so from this, one can quite reliably estimate that IAR’s maintenance sales are about 5 MEUR per quarter.
My understanding is that IAR does not receive distribution-based revenue in the same way as “legacy” Qt products. Therefore, the remainder of IAR’s revenue comes from developer licenses.
My own rule-of-thumb estimate is that IAR’s subscription transition will decrease IAR’s revenue this year by at least 10% y-o-y. Based on management’s comments, the transition has progressed faster than expected. In that case, IAR’s revenue could now be roughly 9-10 MEUR per quarter.
I believe that this year, IAR will dilute Qt’s profitability—both when adjusted for one-off “integration costs” and on a purely reported basis. Next year, the situation should be much better if IAR’s subscription transition proceeds in the right direction and the “excess fat” has been trimmed. This is certainly one part of the 20 MEUR cost-saving target.