Should the thread title be changed to “Qt Group - The growth rocket is burning kerosene again”?
Just so we don’t get too ahead of ourselves or get overconfident, here are some rocket emojis to follow:  .
My favorite part of the report:
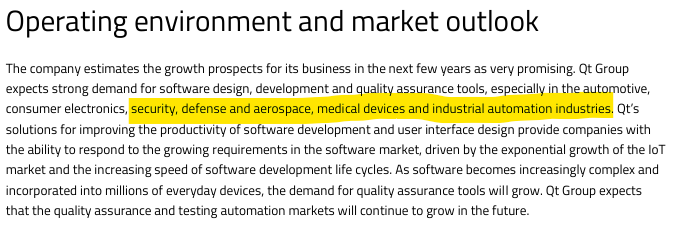
Exactly the kind of mega-trends you want to be involved in.
49 Likes
Qt shareholders and those considering it. What are you planning to do:
- Buying more
- Trimming my position
- Considering buying
- Not touching it
0
äänestäjää
1 Like
Uskoo ken tahtoo, mutta ainakin on jotain mitä odottaa  (kiitos @Marianne_Palmu hyvästä kysymyksestä)
" So it’s like the potential market is like a double basically. So that’s kind of the size I’m envisioning. So if you add all that together, with the current portfolio, you should be able to build a full EUR 500 million business with a very, very profitable operations."
13 Likes
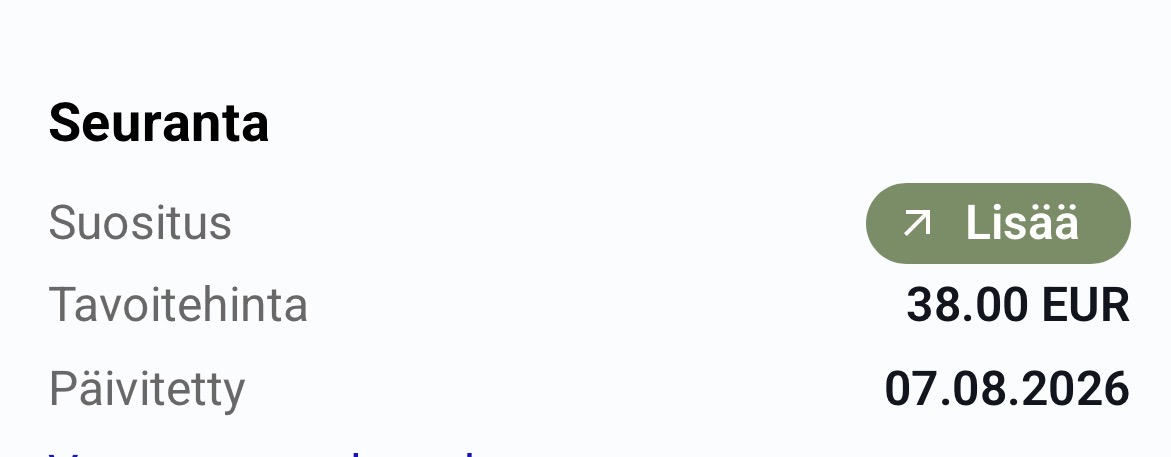
Target price revised upwards, just as yesterday’s report suggested. It will be interesting to see what kind of recommendations others provide.
25 Likes
Kauppalehti’s brief news reports that SEB has raised its target price for Qt Group to 34 euros (previously 28 euros) and lowered its recommendation to “hold” (previously “buy”).
20 Likes
New report:
In my opinion, the forecasts were raised quite significantly, not just slightly.
23 Likes
OP reiterates BUY and raises the target price to 40.0 (prev. 33.0). Titled “The sun is shining again”.
38 Likes
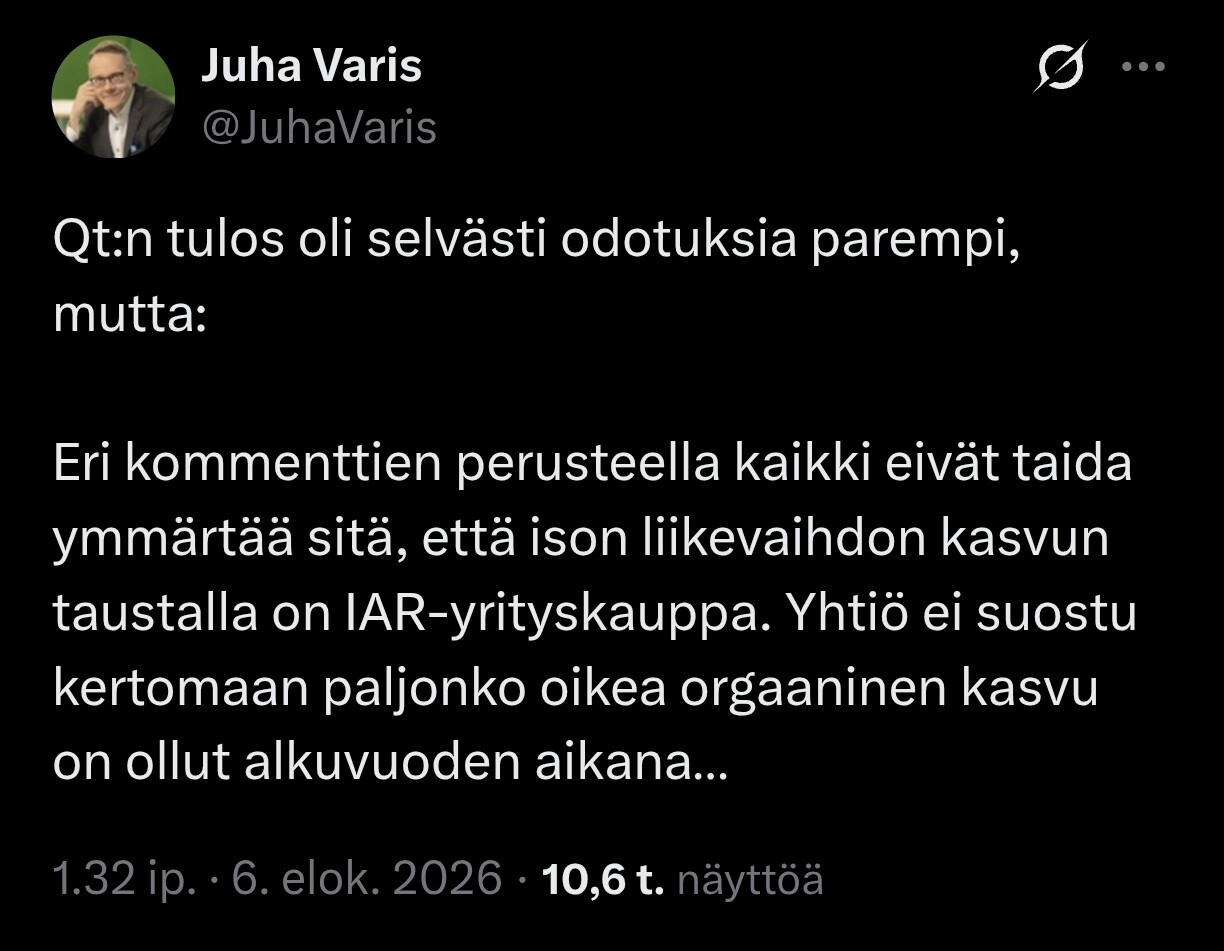
A typical tweet for Juha Varis.
He always looks for something negative in his tweets, worth following.
It is partly true, but the acquisition is also on the “expense side,” meaning surely they can’t report figures before the acquisition indefinitely.
23 Likes
It may be that some didn’t understand this, but the market as a whole isn’t that stupid.
My estimate for the inorganic growth brought by IAR in Q2 is about 8–8.5 million. Of that, about 5 million would be maintenance revenue, which aligns with the growth in total maintenance revenue. At the same time, Qt’s traditional business distribution license revenue fell by 6.2 million. In other words, of the reported 10 million growth, about 7–8 million was from Qt’s traditional business developer license and consulting revenue. That is significant—over 25% growth in the very segment that was feared to be the first hit by AI disruption.
47 Likes
It remains somewhat hazy since Varelius mentioned that the business developed steadily in a challenging market. In reality, the organic growth could well have been very lackluster..
“Despite this, the second quarter was a time of stable business for Qt Group. We remain a key part of many customers’ production processes, which leads to strong commitment and stable renewals.”
11 Likes
No, tell me, why won’t Varelius tell Varis the truth? What is stopping him and what is he afraid of?
3 Likes
It’s hard to believe that in the current golden age of Vibe coding, a developer of such development tools would get very far. Your eyes really open when you prompt for the first time and get a thousand-plus lines of perfectly commented, clear code in just a few minutes.
The share price has quite a lot of growth expectations baked in again, and you can certainly assess from that alone that organic growth hasn’t been very significant. Perhaps there’s reason for caution with this one?
12 Likes
It’s hard to believe that in this golden age of current “Vibe-coding,” a developer of such development tools would get very far. Your eyes really open when you prompt for the first time and get over a thousand lines of perfectly commented, clean code in just a few minutes.
I don’t think “Vibe-coding” or increased productivity removes the need for a programming platform (on which or with which code is written) or commercial licenses. If anything, it creates additional demand (=read: additional sales).
22 Likes
I personally struggle to find any indicators in the reported figures suggesting that revenue is about to enter a period of clear organic growth or that profitability is returning to previous levels. To my eyes, the performance seems quite modest, even though the result managed to beat the analysts’ downgraded expectations.
For example, Inderes’ forecasts look like this:
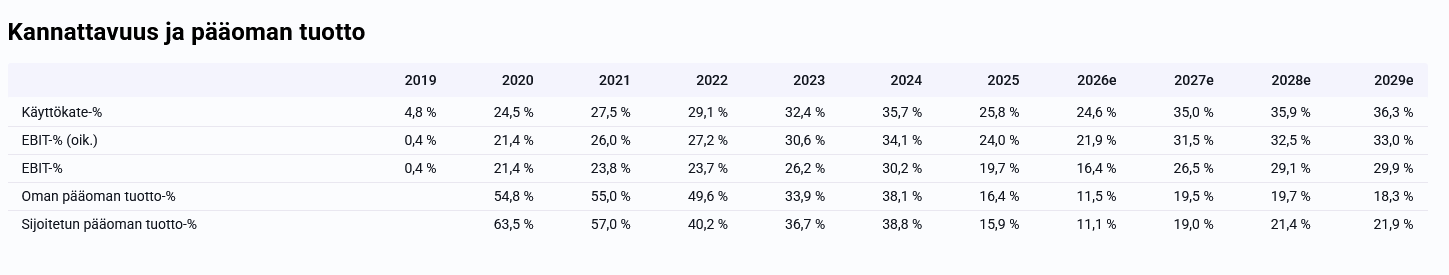
According to the forecast, EBITDA is expected to jump back to the 35% level next year, with revenue growing by nearly 8%. Other analysts share similar views, so Inderes is not alone in expecting this kind of miraculous recovery.
I see many of the same traits here as with Kempower, where analysts who have fallen in love with the company refuse to admit they were completely wrong with their previous recommendations. Now they are trying to kick a dead horse back into motion whenever they find a tiny glimmer of hope.
In my opinion, the stock is aggressively priced considering how challenging things are, let alone what happens if that magical turnaround in earnings fails to materialize.
30 Likes
Without taking a stance on the “vibe coding” or the demand for products in general, I could comment on the valuation, as the share price really doesn’t expect much growth at all. The EV (Enterprise Value) is somewhere just under 900 million. With 250 million in revenue and roughly a 30%-35% EBITDA margin, the company is generating 75-85 million in EBITDA. The nature of the business does not require significant investments, and capital is not tied up in physical assets, so the EBITDA is quite close to cash flow before taxes. So, with these assumptions and taking taxes into account, the company is trading at 12.5-15x free cash flow. It should also be noted that the current organization has been scaled with higher growth in mind, so there would certainly be plenty of inefficiencies to cut on the cost side if the top line remains stagnant forever. Thus, I would say the market is really not expecting significant growth from the company, but rather a decline in revenue over the long term.
23 Likes
That improvement in profitability in Inderes’ forecasts seems to be primarily driven by personnel costs.
There have been cooperation negotiations (YT) and synergy-related efforts following the integration.
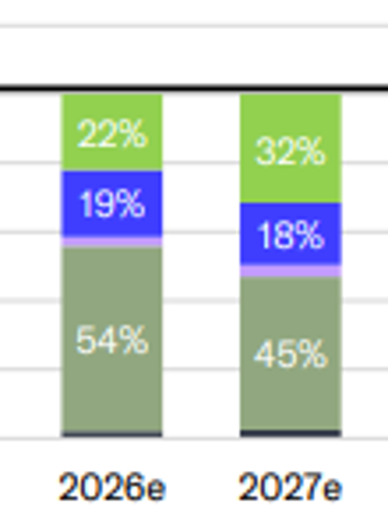
I, for one, am very skeptical that personnel expenses will decrease by 9 percentage points of net sales.
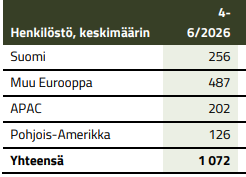
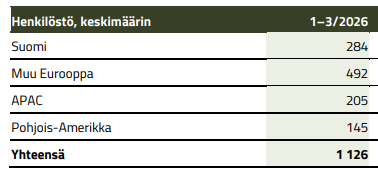
From Q1 to Q2, the headcount had already decreased significantly. Furthermore, there may be more movement out throughout the year.
In addition, there are non-recurring costs allocated to 2026 that will not repeat in 2027:
“The ongoing restructuring of operations and cost savings support the improvement in profitability in the second half of 2026, but on the other hand, they burden the second quarter by 4.3 million euros.”
10 Likes
Are you taking into account IAR’s SaaS transition? The pricing model was changed this year, so it will take a while for IAR to reach the revenue level seen at the time of purchase. For this year, IAR is therefore contributing lower revenue and high costs, which weakens not only the revenue but also the profitability. Qt’s cost-savings program is also quite significant, so it would be a failure if it didn’t show in the earnings next year.
Both companies do have the same problem in the sense that as growth has slowed, the market has continued to search for the right valuation level, but otherwise, I wouldn’t consider Qt and Kempower to be very comparable.
13 Likes
Growth expectations stem from the fact that, by all accounts, sales of development licenses increased. This should also be reflected in distribution licenses in the coming years.
As for the expectation of increased profitability, it comes mainly from the 20 million [euro] cost-saving program. It is important to remember here that Qt invested heavily in sales and R&D in 2025, just as growth stalled. The company assumed that strong growth would continue and bloated the organization prematurely. Analysts assume that this 20 million can be cut from the “fat” added in 2025 without significantly impacting revenue.
IAR’s transition from a one-time license sales model to a recurring revenue model is also a significant driver in the forecasts. To put it bluntly, under the old model, the salesperson had to sell new development licenses to the customer every X years, and the revenue was recognized immediately upon the sale. Under the current model, the customer signs up for a recurring subscription once, the salesperson does not need to sell again, and revenue is generated indefinitely. In reality, things are likely not quite that rosy, but in any case, this change in sales model means temporarily lower revenue relative to costs, and the resulting lower profitability for IAR should recover as early as next year.
The forecasts can justifiably be considered optimistic, but there are definitely grounds for them. It remains to be seen whether those things will materialize as planned or not.
16 Likes