New partner with 4,500 employees found in Spain QPR Software and hiberus: A Partnership Forged to Illuminate the Path to Operational Excellence
6 Likes
More partnerships with Polish consultants.
The final installment of interest-bearing loans is being paid in the coming days, so going forward, there will be €500k more cash available per year. We’ll see how the money will be used in the coming years. Dividend distribution could be a realistic way to use the money, at least in part, as squandering the amount on travel or other marketing and R&D might strain the bottom line perhaps too much.
1 Like
New partners seem to be found at a good pace. This time, collaboration with Swedish SAP consultants.
1 Like
Will it turn into sales? Hardly any new contracts have been seen lately.
Atte’s preview comments as QPR reports its Q4 results on Friday, Feb 13. 
We expect the company’s revenue to have remained in decline due to the expiration of certain legacy contracts, the weakening of the dollar, and an otherwise subdued sales outlook. We expect a largely stable result, supported by staff reductions and temporary layoffs. In the report, the main focus will be on the sales and growth outlook for 2026. The company announced several deals at the end of the year, but in our assessment, clearly accelerating SaaS growth still requires more successes.
According to the latest press release, at least some customer relationships have been established with Cognitio Analytics.
2 Likes
Here are Atte’s and Roni’s comments as QPR deepens its collaboration with Cognitio Analytics
The arrangement is a continuation of the collaboration that began in June 2024, which has already produced its first joint customers. The news is in line with QPR’s strategy, where developing the partner channel plays a critical role in scaling international sales.
1 Like
It seems QPR has started issuing daily announcements. A half-million-euro deal for QPR Metrics to the Middle East.
5 Likes
Here are Atte’s comments as QPR sells the intellectual property rights for the QPR Metrics software for the Middle East & some African countries to Leaders Solutions
QPR Software announced on Thursday that it is selling the regional intellectual property rights for the QPR Metrics software for the Middle East and certain African countries to its long-term partner Leaders Solutions. The arrangement brings a significant one-off revenue stream relative to the company’s size and supports the strategic focus on process mining SaaS solutions. We will account for the arrangement in our forecasts in connection with QPR’s Q4 update.
2 Likes
CEO Heikki Veijola was interviewed by Atte after the release of QPR’s Q4 results.
Topics:
00:00 Introduction
00:11 Q4 summary
01:40 Sales pipeline development
03:52 Full-year development and its drivers
04:57 Building the partner network
10:15 Cash flow and financial position
11:17 AI-based root cause analysis
13:50 AI threats and opportunities
16:42 Outlook and guidance
17:55 Growth investments
18:37 Market outlook
Here is a new company report on QPR from Atte and Roni based on the Q4 results.
We reiterate our Reduce recommendation for QPR and revise the target price to EUR 0.55 (prev. EUR 0.58). The Q4 figures clearly fell short of our expectations, and the growth outlook for 2026 was also a disappointment. With our lowered forecasts, QPR’s combination of growth and profitability will remain subdued in the coming years, in relation to which the stock’s valuation (2026e EV/S 1.8x) is elevated.
Here are Atte’s comments on QPR’s CEO change.
QPR Software announced on Tuesday that it has appointed Matti Erkheikki as the company’s new CEO, effective immediately. He succeeds Heikki Veijola, who is stepping down from his position as CEO. The change of CEO came as a surprise to us as such, but in light of QPR’s sluggish growth rate in recent years, the change of leadership is understandable.
1 Like
Here are Atte’s and Roni’s preview comments as QPR reports its results on Friday, April 24.
We expect the company’s revenue and earnings to have grown clearly from the comparison period, thanks to the IPR sale of the Metrics software announced in February. Without the one-off income, the figures would weaken from the comparison period according to our forecast. In the report, our main focus is on the development of process mining SaaS sales and the first comments from the new CEO Matti Erkheikki, who started in February, regarding the company’s situation. According to our assessment, a sustainable earnings turnaround still requires significantly stronger SaaS growth, for which QPR’s full-year outlook is currently cautious.
2 Likes
You can find the views of QPR’s new CEO Matti Erkheikki on the company here.
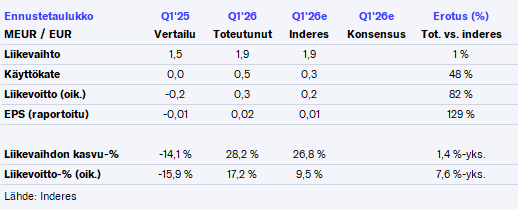
The Q1 result was better than our expectations, as the cost structure was slightly lighter than we expected. It is also worth noting that the income related to the Metrics arrangement (0.616 MEUR) was now recorded all at once in Q1, whereas in our forecasts, 0.5 MEUR was scheduled for Q1 and the remaining tails for Q4’26 and 2027. Stripped of this one-off income, Q1’s operational performance was a notch softer than our expectations, and particularly the development of SaaS revenue (+3% and -5% from the previous quarter) remained subdued. More detailed comments will follow in Monday’s earnings update.
2 Likes
Roni and Atte have published a new company report on QPR
We reiterate our reduce recommendation and EUR 0.55 target price for QPR. The company’s Q1 results exceeded our expectations, but this was partly due to timing factors related to a one-off gain from the Metrics deal, in addition to good cost discipline. The development of SaaS revenue, which is central to the company’s value creation, fell short of expectations, and the full-year outlook remains subdued. At the current valuation (2026e EV/S 2.0x), we believe QPR would need to get its revenue on a significantly stronger growth path for there to be a justified upside for the share.
Quoted from the report:
QPR’s operating cash flow (Q1’26: EUR 1.35 million) was very strong at the beginning of the year, reflecting the one-off gain received and, in our assessment, also collected receivables. In January, QPR paid a EUR 0.25 million installment of its bank loan, with the final EUR 0.25 million installment due in December. The balance sheet is thus now net debt-free in our assessment. Following the strong cash flow, the cash position (Q4’25: EUR 0.62 million) has presumably strengthened in Q1. Additionally, the company has an unused credit limit of EUR 0.5 million available if needed. However, with the current balance sheet, we do not believe QPR can significantly accelerate its growth investments.
1 Like
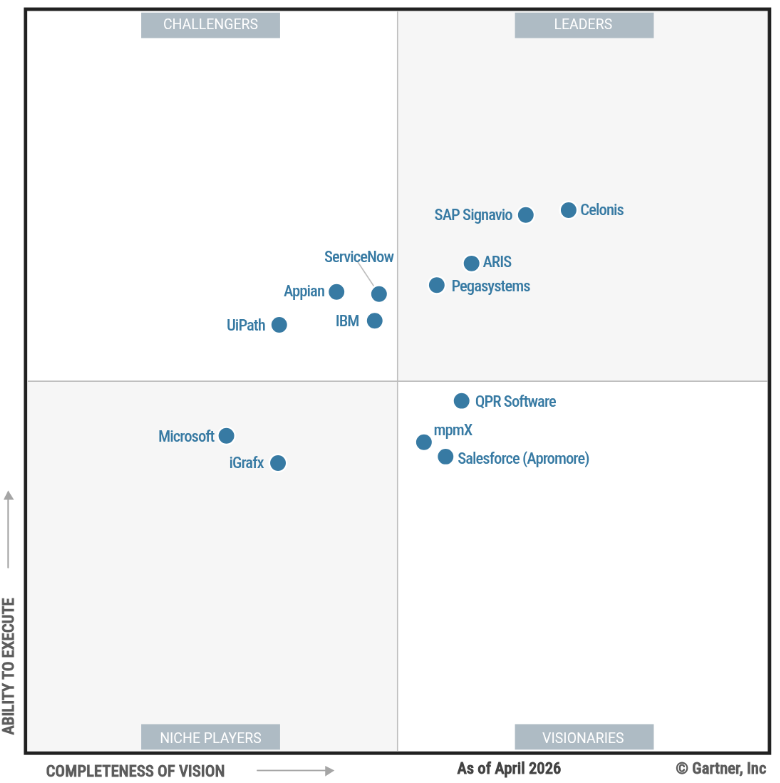
QPR for the fourth year in a row in Gartner’s Magic Quadrant in the Visionary category:
Here is the latest Quadrant from April:
And the corresponding chart from December 2024:
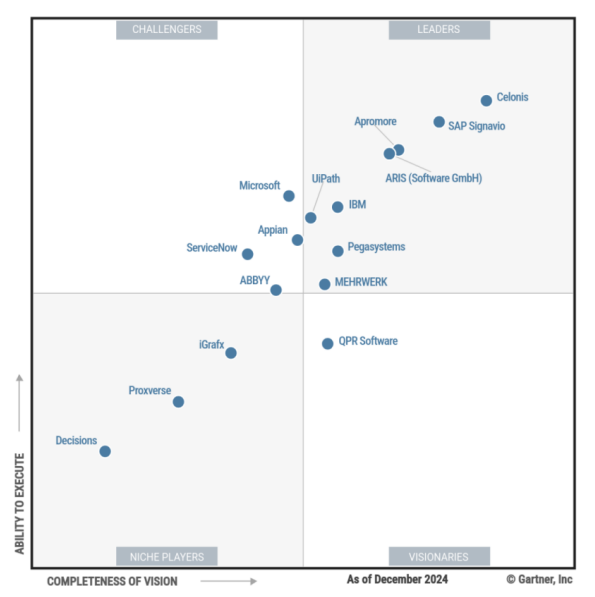
One could note that the field of companies has tightened compared to before and the number of “Leaders” has shrunk. QPR has taken a step upwards in the chart, which can be interpreted as a positive shift. Here is the section on QPR quoted from the report:
QPR Software
QPR Software is a Visionary in this Magic Quadrant.
Its QPR ProcessAnalyzer and QPR EnterpriseArchitect products offer process mining and process modeling and analysis natively, while relying on third-party partners for task mining.
Operations are mostly focused in EMEA, serving midmarket to large enterprises, concentrated in manufacturing and consumer packaged goods, BFSI, and pharmaceuticals and life sciences.
QPR’s roadmap prioritizes enabling agentic AI operations by launching an MCP interface to securely expose process insights to autonomous AI agents, unifying case-centric and OCPM models, and automating process modeling from unstructured data.
Strengths
Native Snowflake architecture: QPR’s platform is built natively on Snowflake, enabling zero-copy analytics that keep data securely within the customer’s environment. This integration enables process analysis without manual data replication or ETL pipelines. However, the platform is not limited to Snowflake customers, and organizations can also access the solution through QPR’s managed service, AWS-hosted offerings, and on-premises configurations.
OCPM: QPR was an early innovator in OCPM. The platform automatically generates object-centric data models from relational schemas by identifying object-to-object relationships, eliminating tedious manual mapping. A native OCPM flowchart visualizes multiple interacting processes such as orders, items, and deliveries in a single view.
Unified process mining and modeling: QPR tightly integrates its process mining and enterprise architecture modeling tools. Users can discover as-is flows from event logs, export them into the enterprise architect repository in BPMN 2.0 format, edit or optimize them, and send them back to the process analyzer for automated conformance checking.
Cautions
Process modeling and analysis: QPR’s modeling environment and simulation reports have an outdated appearance and lack modern design. Setting up simulations requires significant technical expertise and lacks guided or AI-assisted setup, making onboarding challenging for new users.
Geographic concentration and partner-dependent reach: QPR focuses direct sales and growth on Europe. In other regions, such as Latin America, Asia/Pacific, and the Middle East, the company relies on partners for implementation and support. Organizations outside Europe should confirm that local partners have the expertise needed for deployment and ongoing success.
No native task mining: QPR has retired its proprietary task recording technology and now relies on third-party partners for granular, task-level data capture. Organizations that require integrated process and task mining must procure and manage a separate tool, increasing procurement friction and deployment complexity compared with unified competitor solutions.
2 Likes
Finally some news on this board as well..
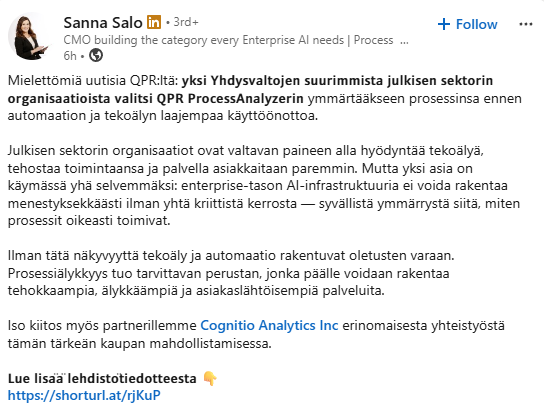
QPR’s software to be implemented in one of the largest public sector organizations in the United States QPR:n ohjelmisto käyttöön yhdessä Yhdysvaltojen suurimmassa julkishallinnon organisaatiossa | Kauppalehti
7 Likes
Sanna has a good comment regarding the development of AI across the entire organization’s operations.
4 Likes
Here are Atte’s comments regarding this recent news from QPR
QPR Software announced on Wednesday that one of the largest public sector organizations in the United States is deploying the company’s QPR ProcessAnalyzer software. We view the news as a positive signal, as it represents an important strategic breakthrough and a concrete demonstration of the North American partnership strategy’s effectiveness. The fact that the deal was announced via a press release suggests that it is not immediately significant in financial terms. However, QPR has now got a foot in the door of the U.S. public sector, which could lead to new deals or expansions of the current contract in the coming years. The news does not trigger immediate changes to our forecasts, but it supports our expectations for SaaS revenue growth.
6 Likes
Negative profit warning from QPR
New guidance for the 2026 financial year
Based on the current contract base and market outlook, the company estimates that SaaS revenue for the 2026 financial year will be lower than the previous financial year’s level. The company estimates that QPR ProcessAnalyzer’s SaaS revenue will be at the same level as the previous financial year.
The company forecasts that EBITDA will be positive and better than in the previous financial year.
Due to the nature of the business and long sales cycles, quarterly fluctuations can be significant.
The company’s operating environment is expected to vary regionally in the 2026 financial year, and economic growth in several market areas is forecast to be moderate. Geopolitical tensions, trade policy risks, and political uncertainty increase uncertainty in the international business environment.
Previous outlook for 2026 (given on Feb 13, 2026, reiterated on Apr 24, 2026)
Based on the current contract base and market outlook, the company does not expect a significant change in SaaS revenue development in the 2026 financial year. The company forecasts that EBITDA will be positive and better than in the previous financial year.
Due to the nature of the business and long sales cycles, quarterly fluctuations can be significant.
The company’s operating environment is expected to vary regionally in the 2026 financial year, and economic growth in several market areas is forecast to be moderate. Geopolitical tensions, trade policy risks, and political uncertainty increase uncertainty in the international business environment.
2 Likes