Purchase:
- Copart. Finally snagged an opening position in this hype-boom-thing!
Since this message written at the end of May, the valuation multiples have practically melted. The P/E at that time was 33x → 29x; EV/EBIT 27x → 23.8x. This is still not cheap, but there are many factors in the background that catch my attention. Firstly, the business model (which I briefly explain in the quoted message) has proven effective over a long period. The company is developed steadily, without unnecessary rushing in any direction. Management has strong skin in the game, and the business is developed for the long game, not quarter by quarter. The company’s biggest problem is where to deploy its approximately 3.5 billion USD cash pile, as there isn’t much debt either. A true quality company!
For this reason, Copart has always been quite generously valued. High multiples for a slow-grower (mörnijä) growing about 10% annually, which certainly doesn’t operate in a very sexy industry. However, in recent months, the valuation has started to become a bit more appealing, considering that Copart is always expensive. You won’t get this at P/E 15, so there’s no point waiting for that. This time, the buy signal was actually given by TA charts, where there’s an interesting spot: on a weekly level, the SMA(200) has hit the price curve quite rarely. We are now pretty much a dollar away from that event, and thus I find the entry point quite appealing. History doesn’t always repeat itself, but it often rhymes. Previously, these have been at least good buying opportunities. It’s also good to note that the underlying business has remained stable, and it practically has a market duopoly in the United States.
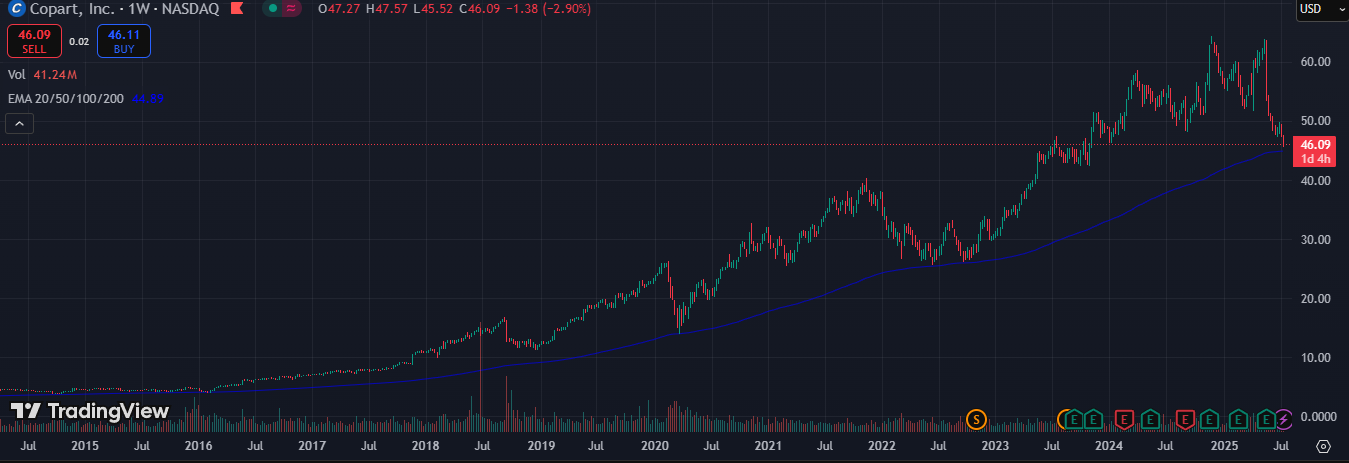
I’m jumping in with a small position (2% of the portfolio), but I will very likely take another similar one in the coming days/weeks.