I forgot to mention that, at least based on what I’ve read from the forums, the stock didn’t really rise much after the exploration result of the occurrence was announced. It’s possible I misunderstood or that the stock had already gained significantly in advance?
1 Like
But did that research result have an impact on the stock price? I understood it didn’t?
1 Like
It was released on Wednesday before the stock market opened
https://orocoresourcecorp.com/oroco-announces-significant-3d-ip-survey-results/
2 Likes
That result is largely baked into the course already. It would have been a surprise if the imaging had yielded poor results, although the result was particularly good now. One must remember that this is an expensive stock, when talking about junior mining, but at the same time also the highest quality - the QT of its own field. Sometimes it goes sideways, especially if the entire junior copper sector is slumping. It will then rocket again in due course. It is typical that daily gains are really steep (30%) and then it is difficult to buy into rising stocks. In my opinion, this current situation was an excellent opportunity to add - the risk level decreased, but it did not affect the price.
4 Likes
Slightly off-topic, but Crux published an excellent article on investing in mining companies, which, among other things, listed risk factors associated with juniors.
4 Likes
I myself haven’t bought junior mines for a couple of reasons:
- Reserves are overestimated relative to fair value,
- Production costs are underestimated,
- Investment costs are underestimated,
- Startup difficulties are commonplace,
- Continuous dilution of shares through offerings.
Equipment isn’t cheap, especially in these low-grade ores. The investment period, including the ramp-up phase, can be decades. Over this timeframe, before any copper concentrate has been sold, estimating the price of copper is pure speculation.
Does the ore contain Platinum Group Metals or other side streams that could bring in the entire revenue once processing begins, with copper being a byproduct?
Water treatment is unlikely to be an issue in hot countries, but there are always risks associated with environmental damage.
In my opinion, these issues haven’t really been addressed in this thread or in the video. The video relies on the idea of being bought out, and investment isn’t discussed at all.
Furthermore, a Feasibility Study hasn’t been done with investment in mind. We are truly at the very beginning stages here.
Have the rock samples been studied from the perspective of metallurgical processes?
Apologies for the bearishness, but I myself would also see a potential big upside in PGMs. These are common in this type of ore.
5 Likes
DFS is done after drilling.
So the order of operations is as follows:
-3DIP completed
-Permits for drilling (allegedly the permit process is already underway)
-Drilling through which DFS is obtained
-Sale to a major
In this case, the risk is reduced by the fact that one of the three areas (North) was already drilled in the early 90s, and the results obtained from there can be mirrored with the 3DIP results, so we’re not starting from scratch. Now there are signs that the other two areas (South, Brasiles) are also good mining areas, meaning CAPEX is distributed over a larger amount of ore.
There are probably 10-15 videos on the subject in total, if you’re interested, go through all of them.
1 Like
Valid points, everything you brought up. When you watch those videos, you’ll surely get answers to quite a few questions. By “equipment,” do you mean equipment potentially used for mining/enrichment? That won’t be part of Oroco’s operations, but it would be for the buyer.
What factors do you think would support a decrease in copper prices in the future?
Fitch Solutions expects the copper market deficit to ease from an estimated 416,000 tonnes in 2019 to 299,000 tonnes in 2020 before widening again from 2022, according to a mid-September report. The analytics provider forecast a shortfall of 489,000 tonnes in 2024, rising to 510,000 tonnes in 2027.1.10.2020
2 Likes
A little more presentation on the Santo Tomas find, since there was interest https://orocoresourcecorp.com/wp-content/uploads/OROCO-RESOURCE-CORP-Presentation-AUG-2020.pdf
1 Like

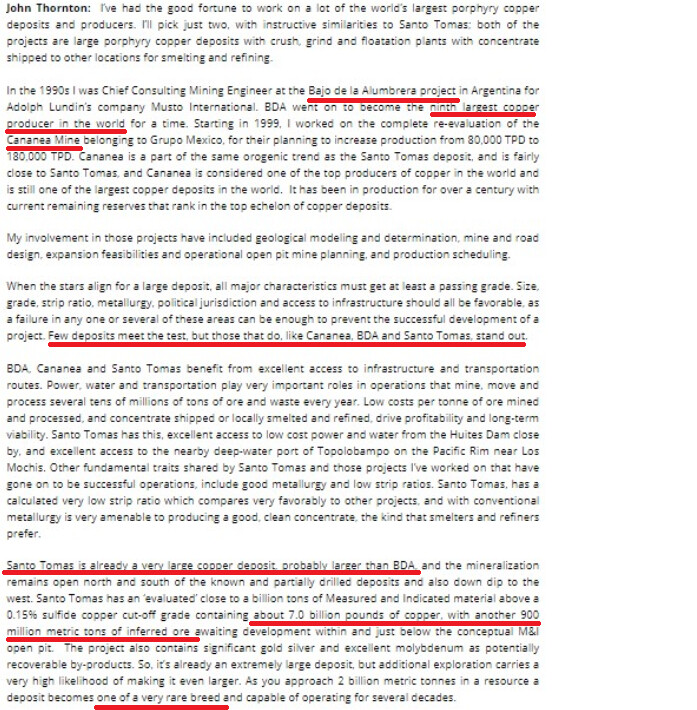
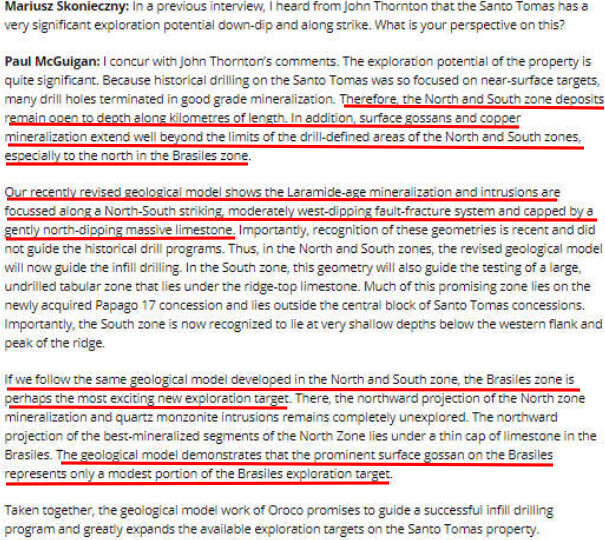
3 Likes
I don’t doubt the size of the ore body for a second.
For me, the biggest problems are two things:
-the profitability of utilizing the ore body,
-the true cost of the exit strategy.
The first naturally affects the latter a great deal.
Junior mines have a significant risk, as mentioned in the opening, but also a significant upside if realized favorably.
4 Likes
A SeekingAlpha post about Oroco, relatively bearish at least in the short term. Published in December, so it doesn’t take into account the results of the latest 3DIP measurements. However, it’s a relatively in-depth analysis of the copper business, so it’s worth reading:
https://seekingalpha.com/article/4394432-oroco-resource-lofty-valuation-for-historical-resource
2 Likes
The writer in question has written 1100 articles in five years, which is 220 articles per year, or about one article every weekday of the year.
I somewhat doubt the guy’s ability to delve deeply into this case.
Anyway, basing a valuation on some historical performance table at different stages of a project is a bit daft if you ask me.
2 Likes
In Oroco’s case, these analysts have been condemning it to the lowest tier from the start. Only very recently have a few admitted their mistake.
2 Likes
I’m currently poring over a technical report.
I wouldn’t be too concerned about the term “historical” here. This patch of land has been owned by so many parties over the years that each one has wanted to verify measurements, so they’ve been confirmed quite a few times.
Larger drillings have been done twice by two different owners. In addition, other owners have conducted small test drillings a few times to confirm these larger drillings. The data from all measurements is consistent with each other. Now that we also have promising 3DIP measurements, the risk of anything other than positive surprises in standard measurements is relatively small.
I need to look into its valuations a bit. One has already caught my eye: a company called Marimaca (also TSX) has a smaller copper project. With a copper price of $3.15, an 8% NPV discount rate, and leasing mining equipment, the post-tax NPV is $524 million. On the other hand, the copper content is slightly higher than Santo Tomas.
=> With these parameters, the company’s mcap is currently $200 million, making the P/NPV 0.38.
In itself, I’m not necessarily a big fan of NPV in this context. With an 8% discount, copper mined 10 years from now is valued at only 43% of its worth. At a time when the risk-free rate on US government bonds is about 1%, a 7% risk premium for operational activities (the risk that the mine would for some reason no longer be able to extract copper from the ground in the next year) seems quite high. Unlike many other businesses, future cash flows in a mine are demonstrably present in the ground, almost like on a balance sheet. Converting them into cash just takes time.
NPV analysis is probably more relevant for small <10-year projects where the ratio of NPV to initial investment is poor, but especially in a project as large as Santa Tomas, IRR better reflects long-term cash flows. The project, with quite conservative estimates, yields over a +20% net profit on the initial invested capital every year for decades.
8 Likes
Historical exploration projects
- From the beginning of the 20th century, locals have been manually digging for ore in the area.
- 1968 - 1971 ASARCO drilled most of the holes currently in the area. A total of 59 different drillings with a total drilling distance of 15,000m (Drilling series STD in company documents).
- 1973 - 1977 Tormex had ASARCO’s drill samples re-measured and also drilled 7 holes themselves, totaling 2400m. Both matched ASARCO’s results.
- 1973 The Mexican government surveyed the area’s mineral resources with the help of geologists. Apparently, the survey mainly focused on the general geology of the area, and no drillings were made, for example.
- In the 1980s, the Mexican government surveyed the area’s mineral resources using helicopter-borne magnetic measurements. Large magnetic anomalies were observed over a large area around the current research area. In addition, four smaller anomalies were observed within this area, within the current mining area owned by Oroco.
- 1990 Esmeralda group made research plans for the area and cataloged the locations of previous drillings.
- 1991 Minera real de angeles re-measured ASARCO’s drill samples and took two new samples themselves from ASARCO’s drill holes. The results apparently matched ASARCO’s figures, but official documents are no longer available.
- 1992 - 1997 Exall Resources drilled 40 new holes for a total distance of 4000m. (Drilling series STE in company documents). Measurements matched ASARCO’s measurements. ASARCO’s and Exall’s measurement results were combined, and based on them, the first pre-feasibility study was built by Bateman engineering (available on the company’s website). Exall also conducted metallurgical tests on the ore.
- 1997 - 1998 Minera MGM reviewed all previous reports and conducted small verification measurements themselves. Official documents are not available for this.
- 2002-2007 Ownership of the area during this period is somewhat unclear, but the consultant IGNA engineer re-tested ASARCO’s and Tormex’s samples, and took some verification samples. The results matched the historical reports. IGNA also conducted three geological studies on the area’s structure between 2002 and 2007.
- 2003 Bateman engineering updated Exall’s pre-feasibility study from 1994 but did not conduct verification measurements themselves.
- 2005 - 2010 Cambria Geosciences conducted several technical studies, including re-measuring old drill samples and acquiring material from Exall’s ex-consultant for the area. Based on these, an estimate was made of the area with the highest ore content, which is usually referred to as “2009 grade shell” in later documents.
- 2011 Thor resources created a mining plan for the area and a 3D model of the area’s reserves (apparently practically an interpolation based on historical drillings). (Thronton 2011)
- 2015 Ownership ended up by court decision with the previous owner Ruero International, from whom Oroco (Xochipala gold) bought the area in 2016.
9 Likes

Demand for copper is constantly growing thanks to EVs and general electrification worldwide.
Copper production remains at the same level or decreases as old mines begin to deplete.
Copper inventory levels are at a 5-year low.
The price of copper continues to rise.
Oroco’s Santo Tomas (ST) mine’s NPV is at a minimum of 1.6B USD at a copper price of 3.25 USD (an estimate from a year ago). With new results and the current copper price of 3.75 USD, the NPV could be as high as 5-8B. Oroco owns 81% of the ST mine.
It is estimated that Oroco will receive 40% of the NPV when a major acquires it.
1600M x 0.81 / 250M shares x 0.4 = 2.1 USD, or about 2.6 CAD per share.
5000M × 0.81 / 250M x 0.4 = 6.5 USD, or about 8.5 CAD per share.
8000M x 0.81 / 250M x 0.4 = 10.4 USD, or about 13 CAD per share.
The price on the stock exchange yesterday was 1.78 CAD.
Just think about it.
10 Likes

In the portfolio. It’s been thought about.
5 Likes
Anyone interested in copper or oroco, check out this fresh presentation

8 Likes