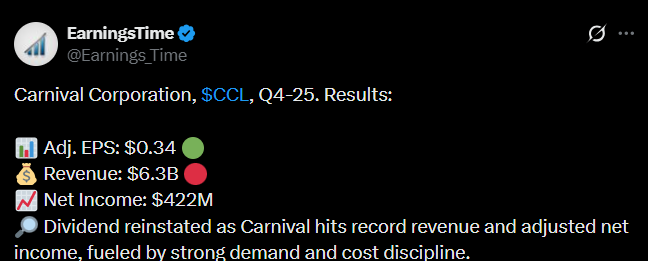
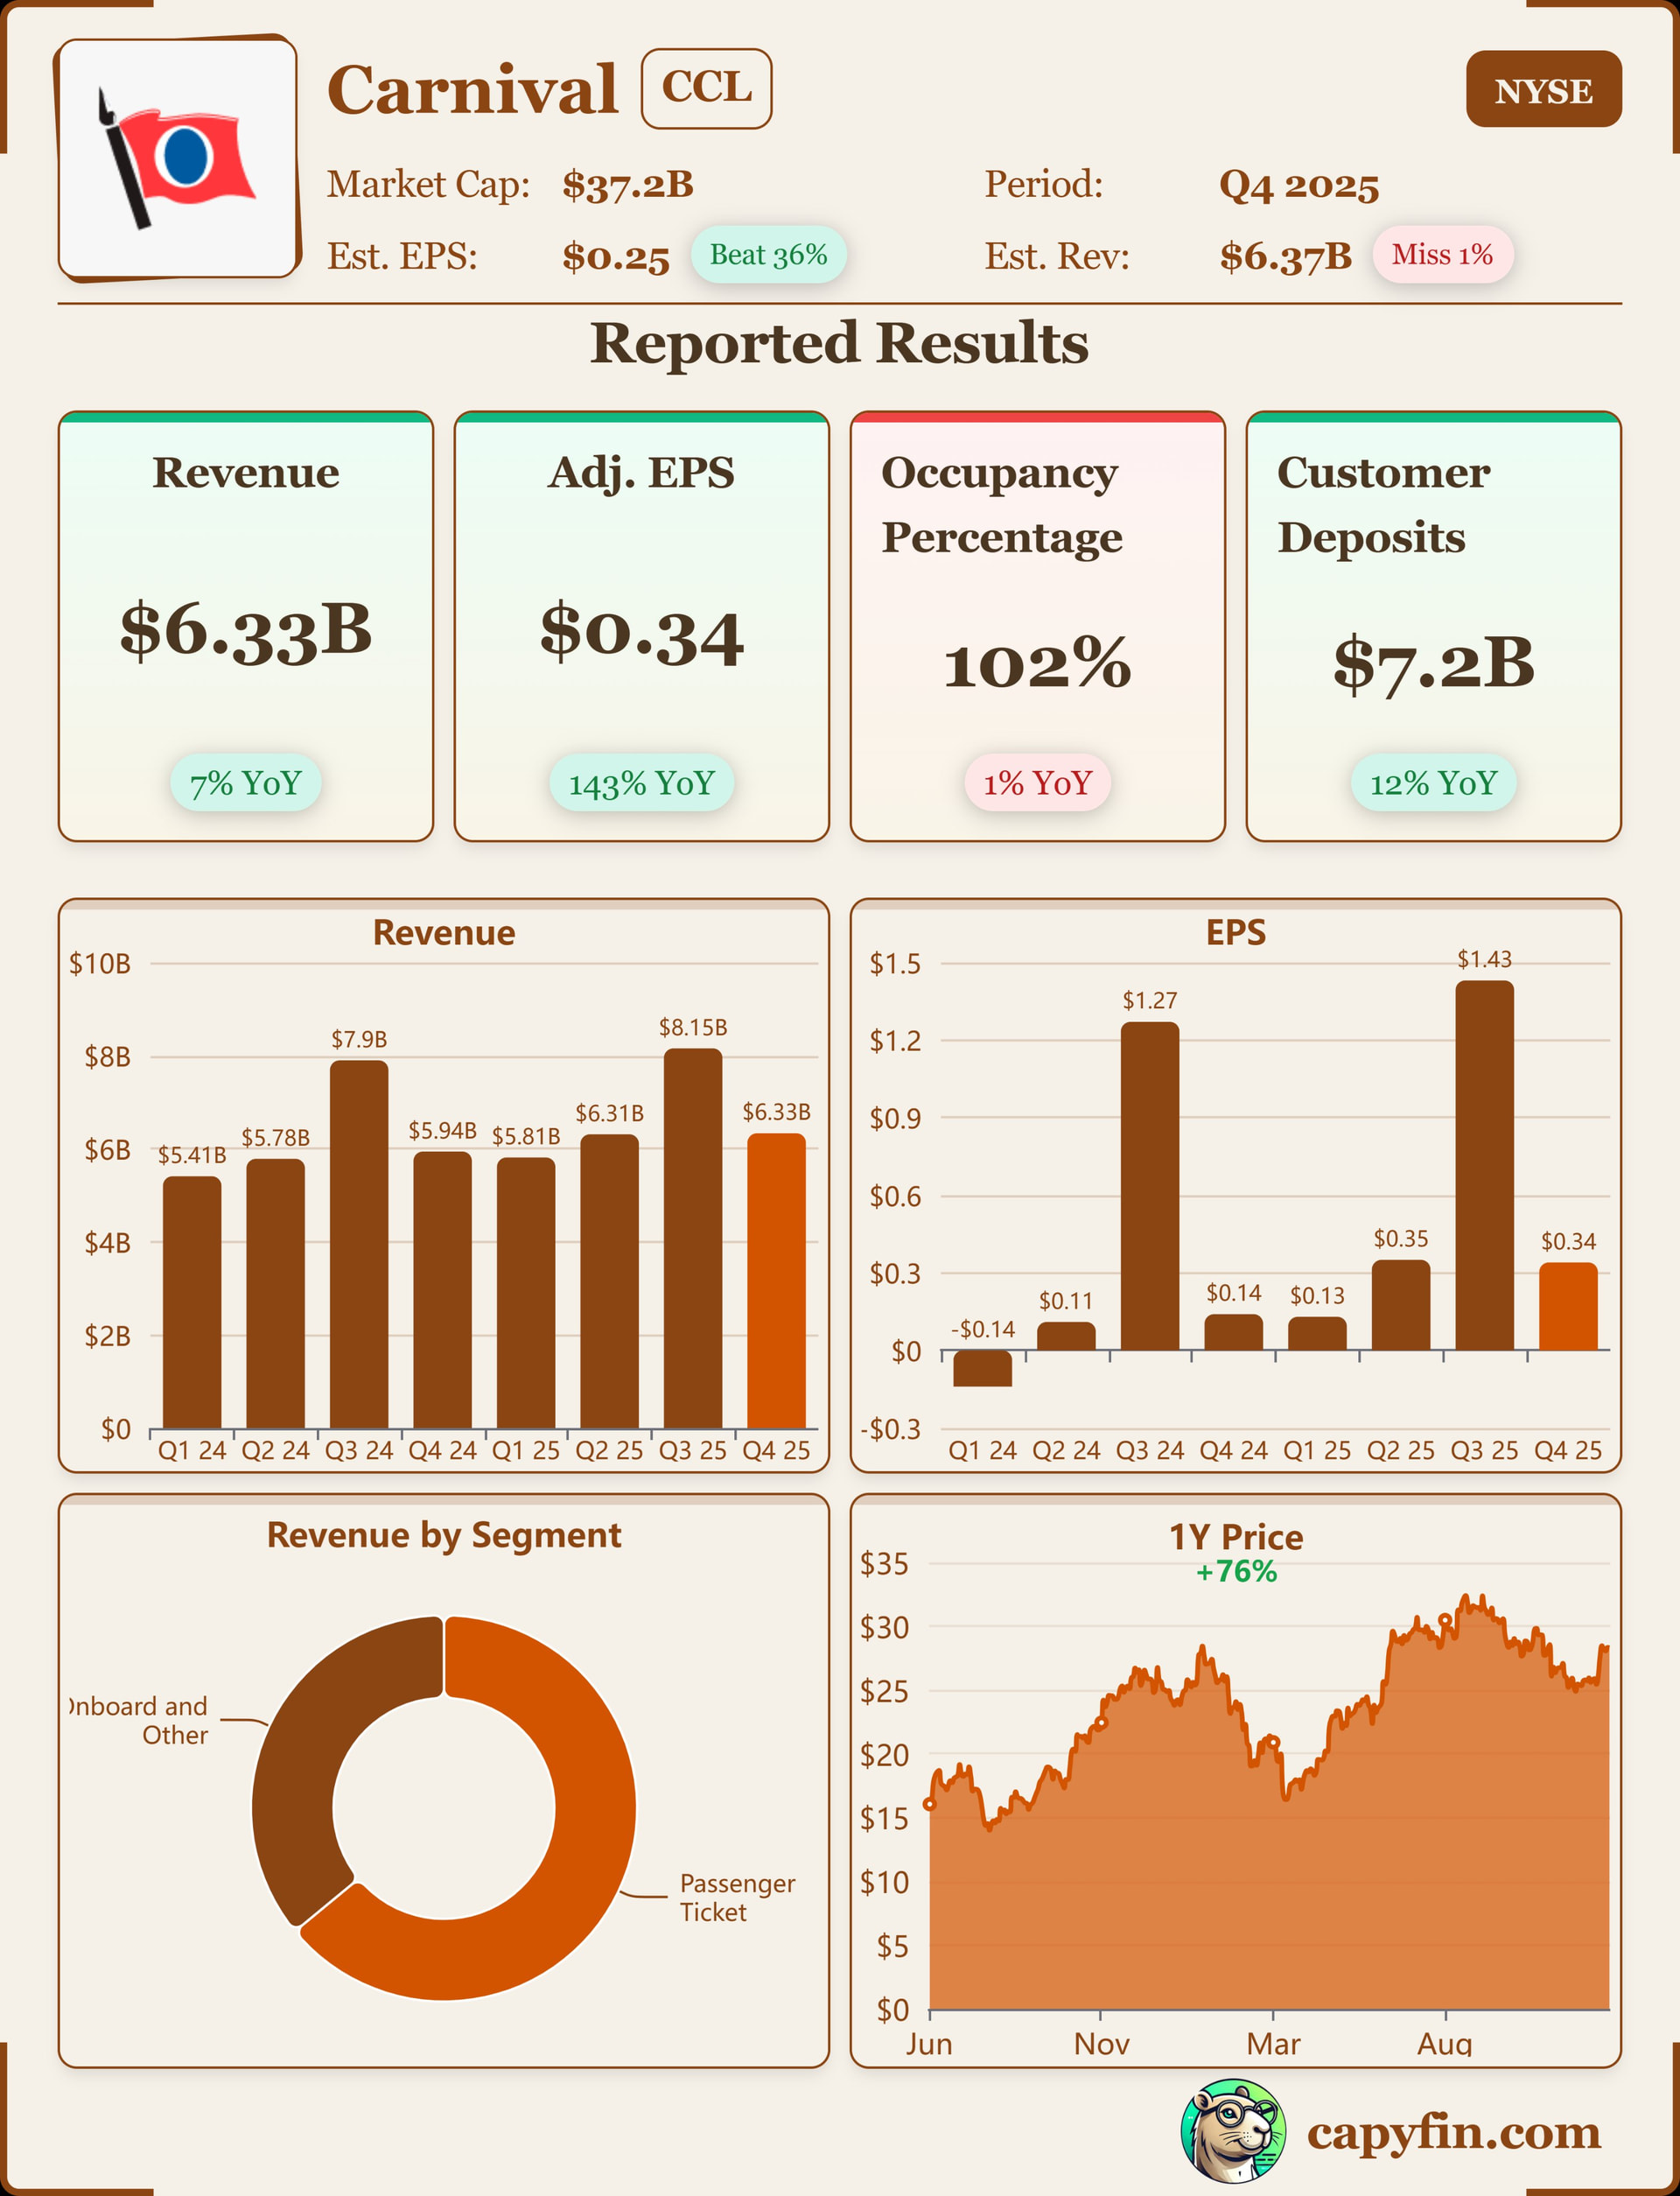
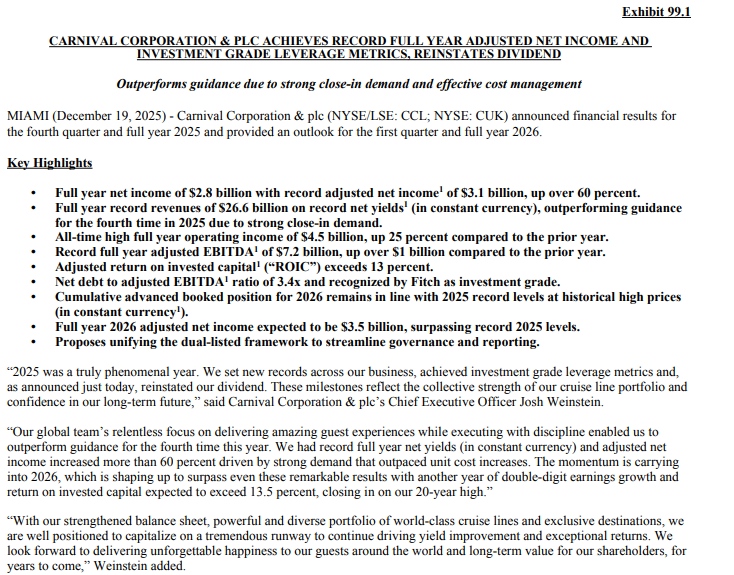
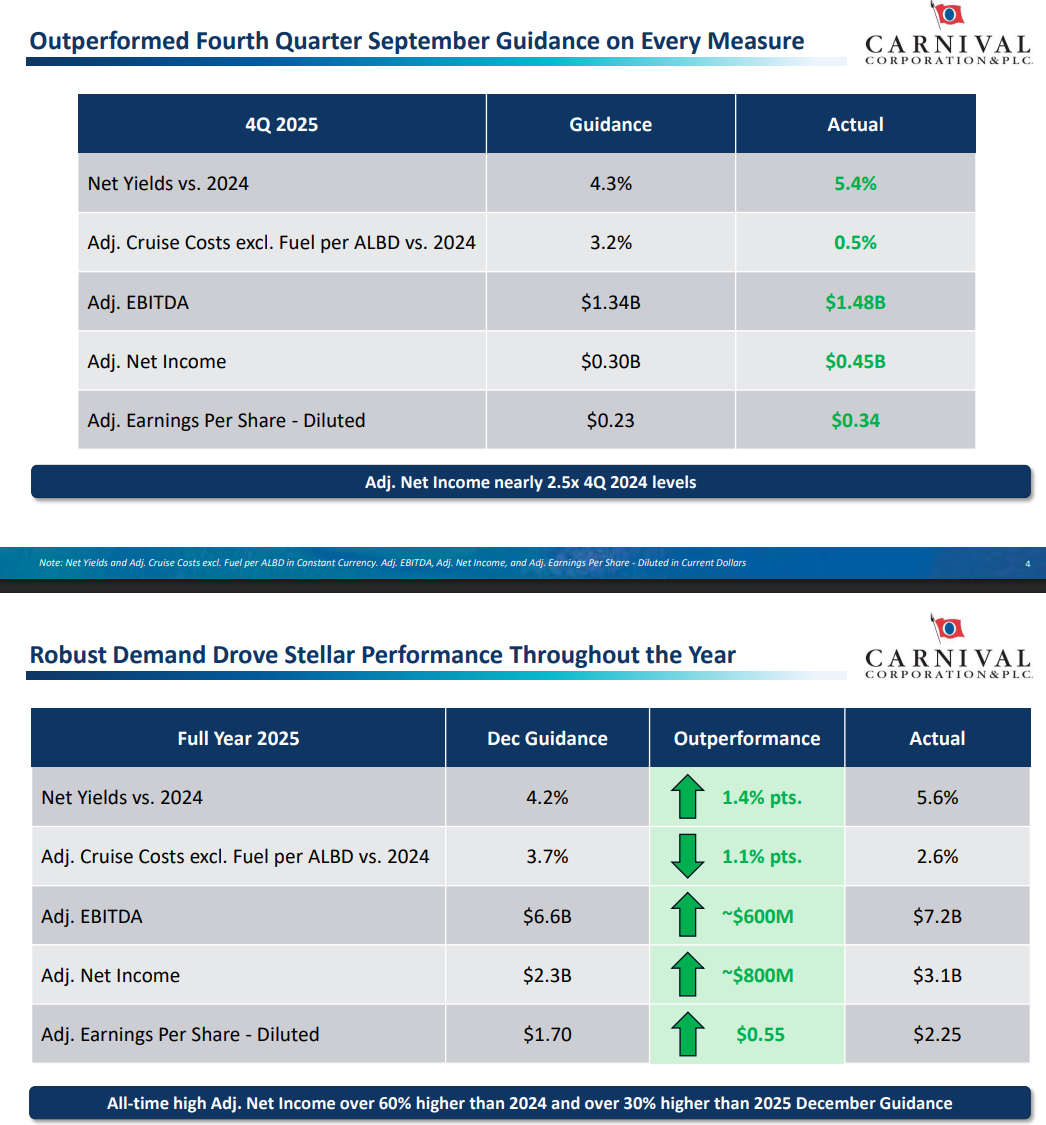
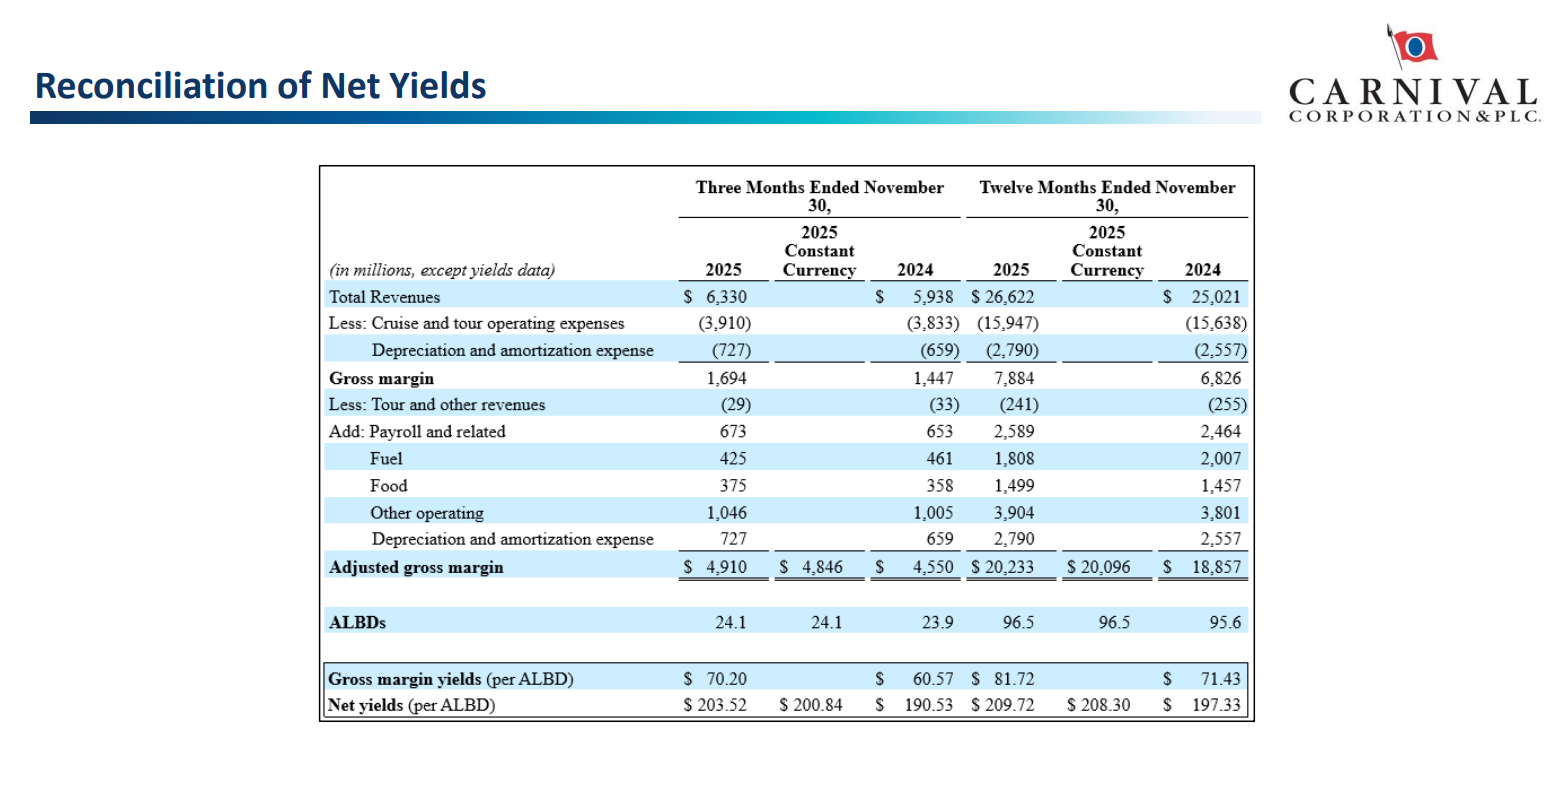
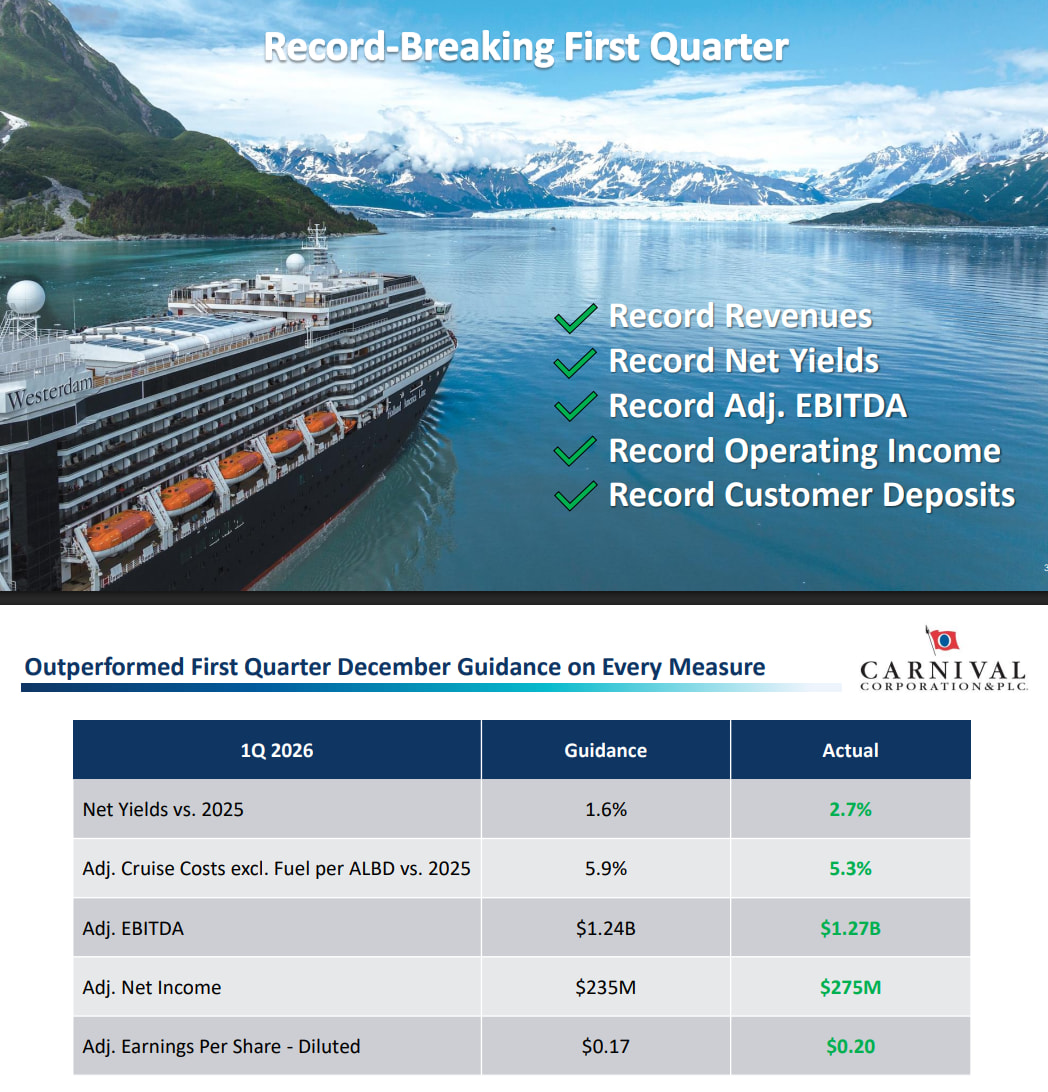
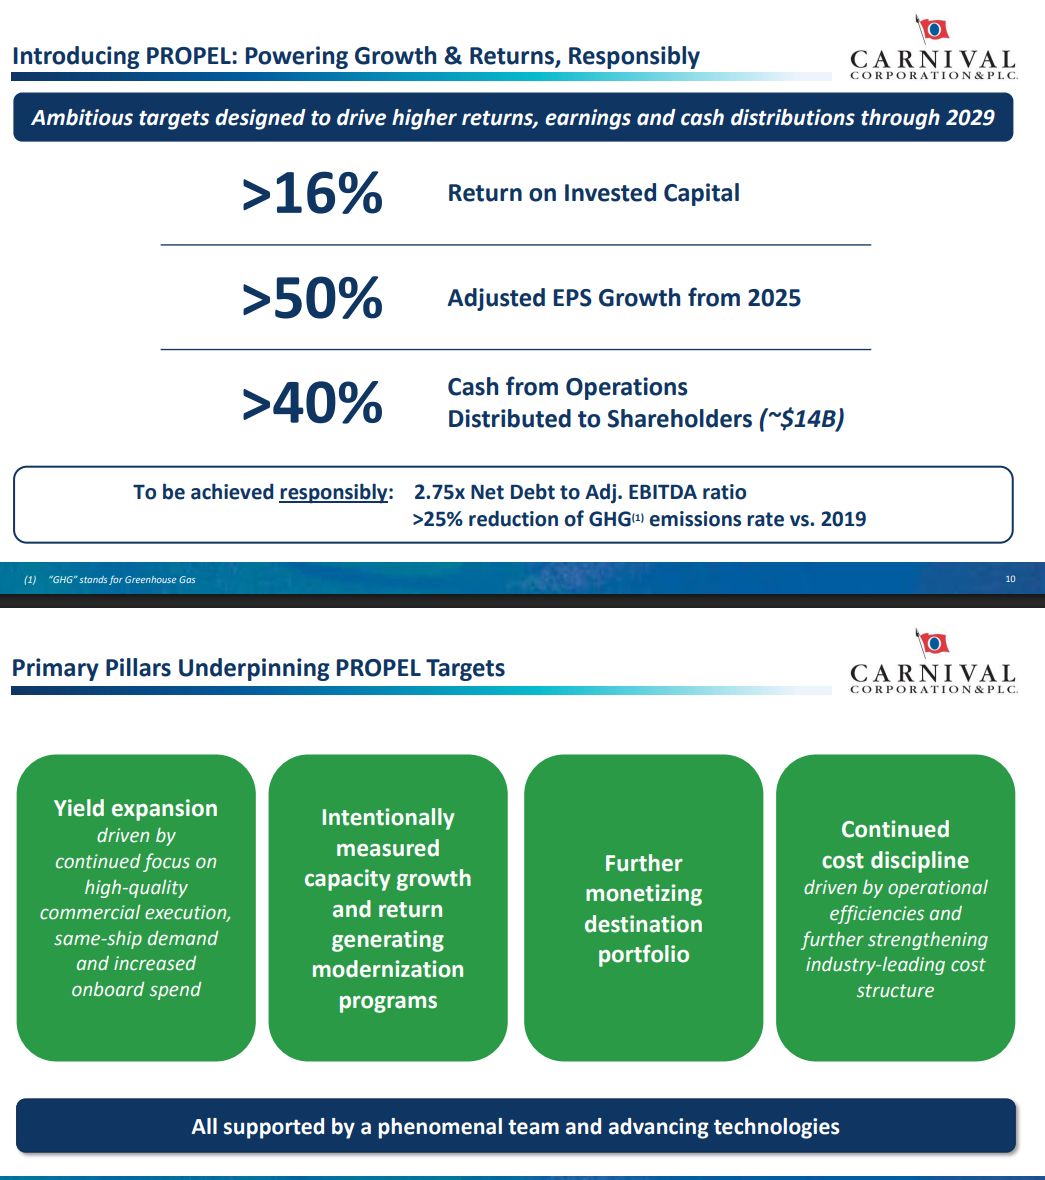
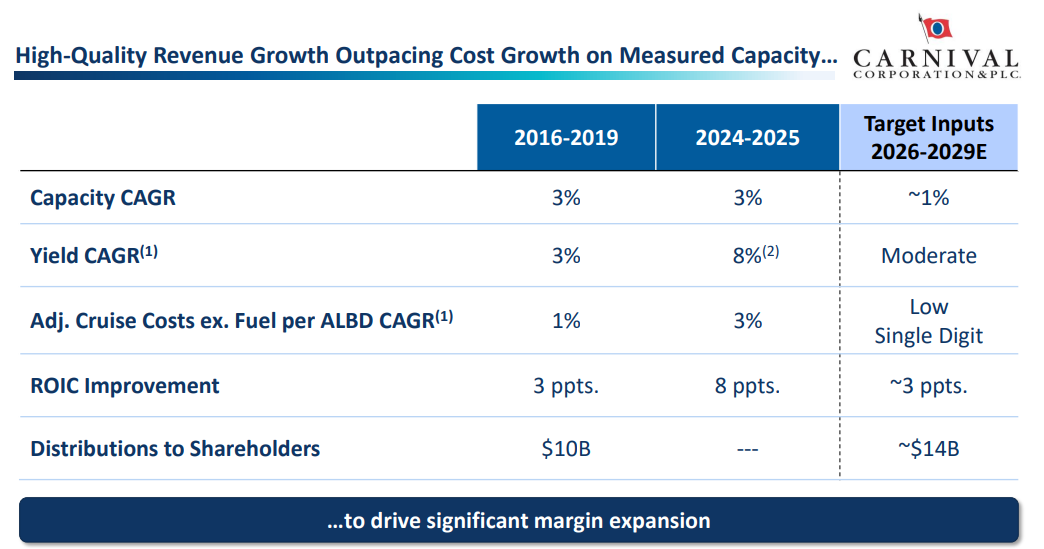
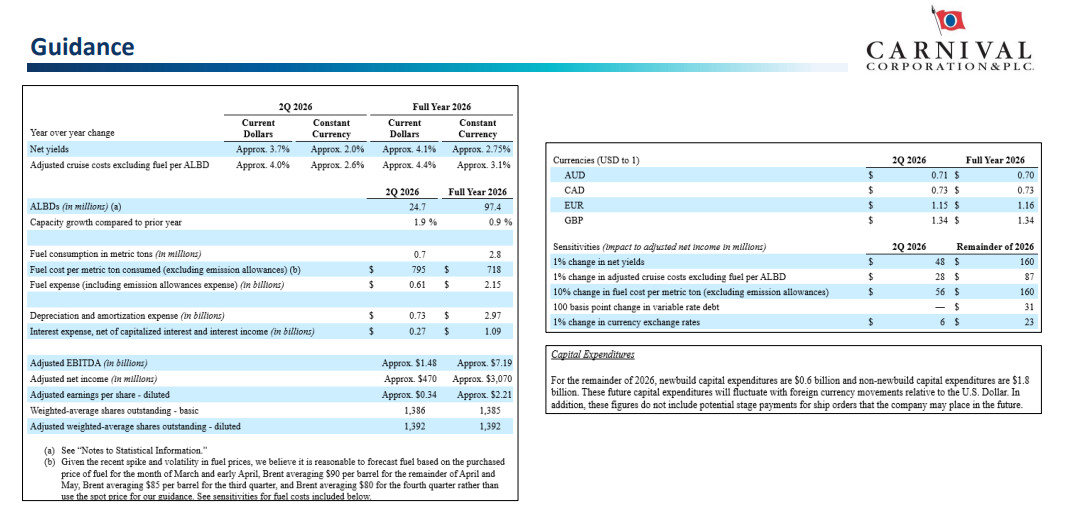
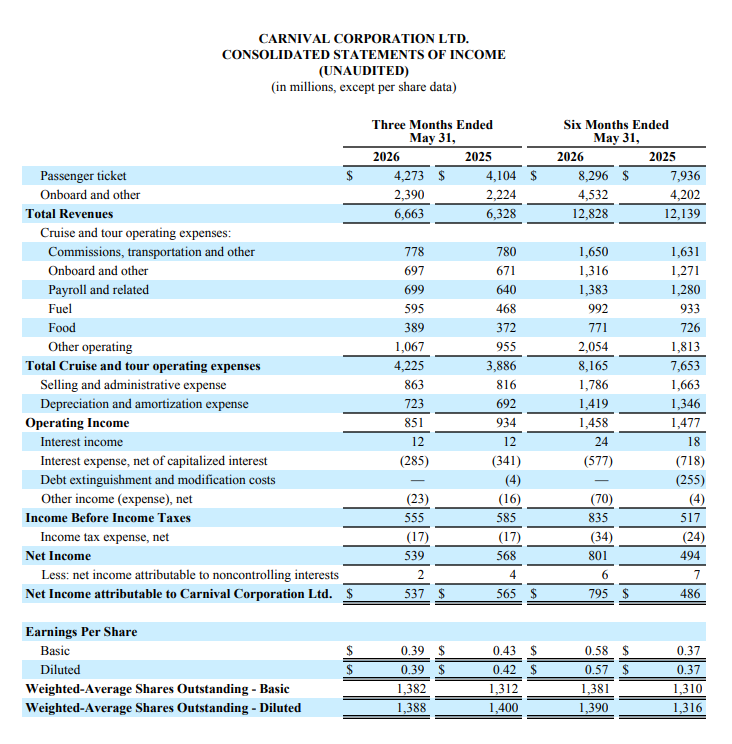
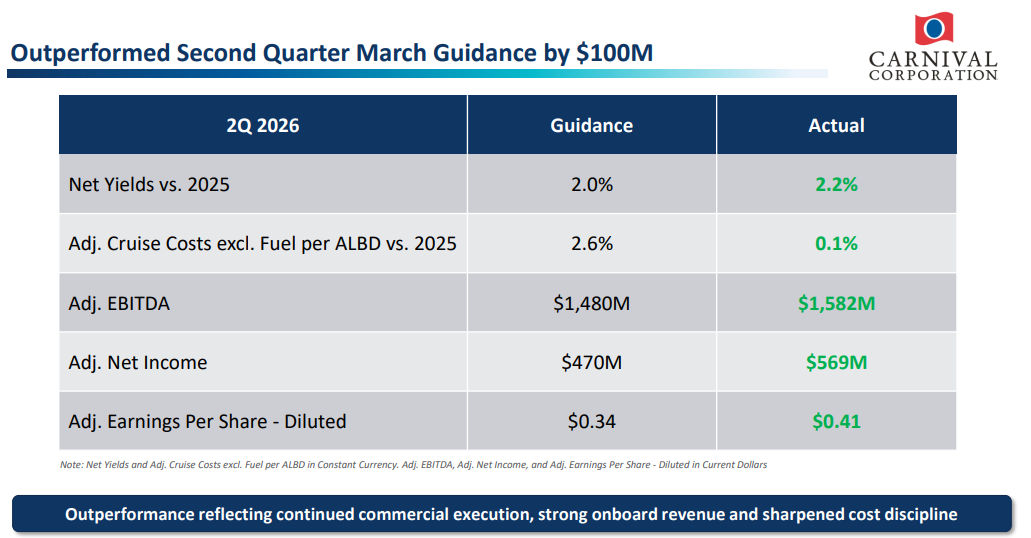
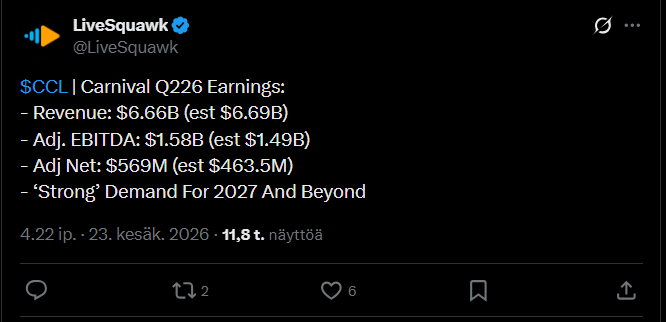Carnival again achieved a record result, in addition to raising its earnings guidance and reporting strong demand as well as booking accumulation for future years. Revenue and net profit exceeded expectations. It was also pleasing that energy efficiency brought additional benefits.
Challenges, however, include increased personnel and food costs, as well as still high debt, but cruise demand and improved margins keep the outlook positive for at least the coming years.
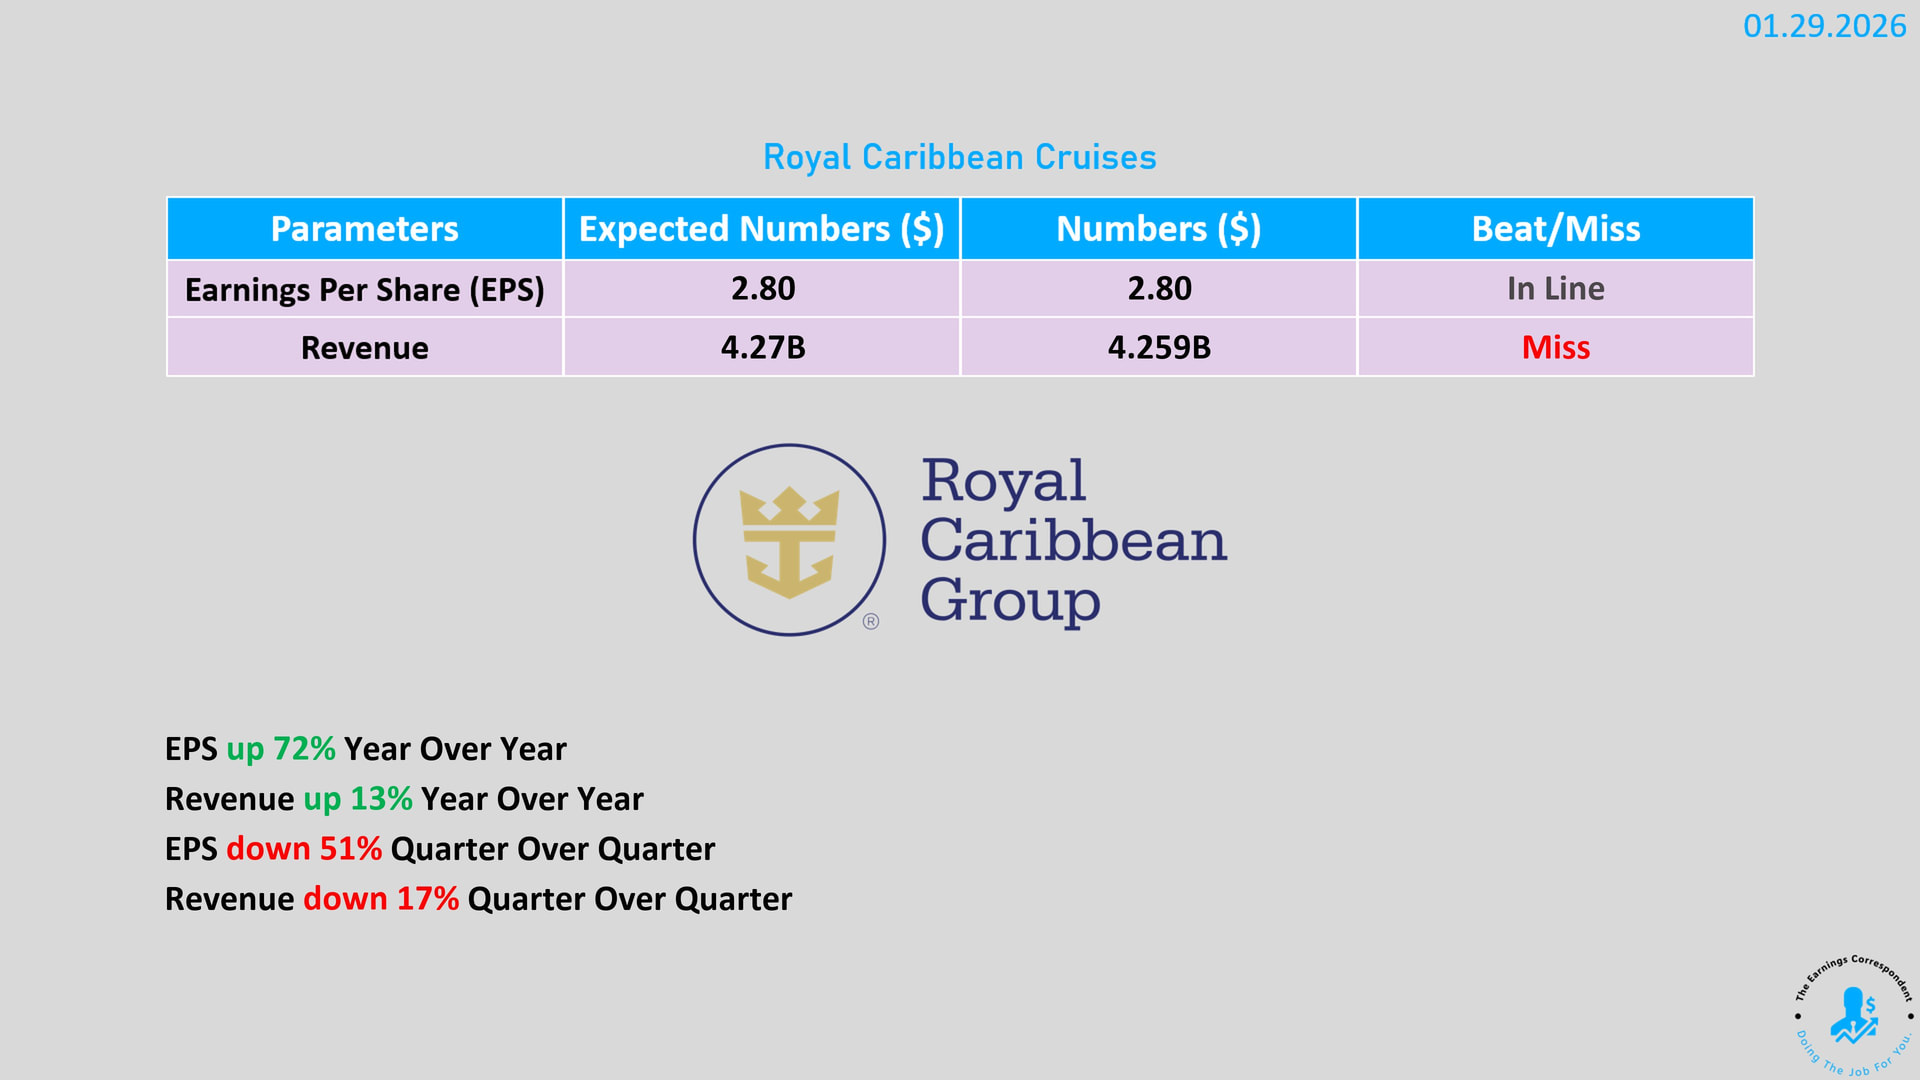
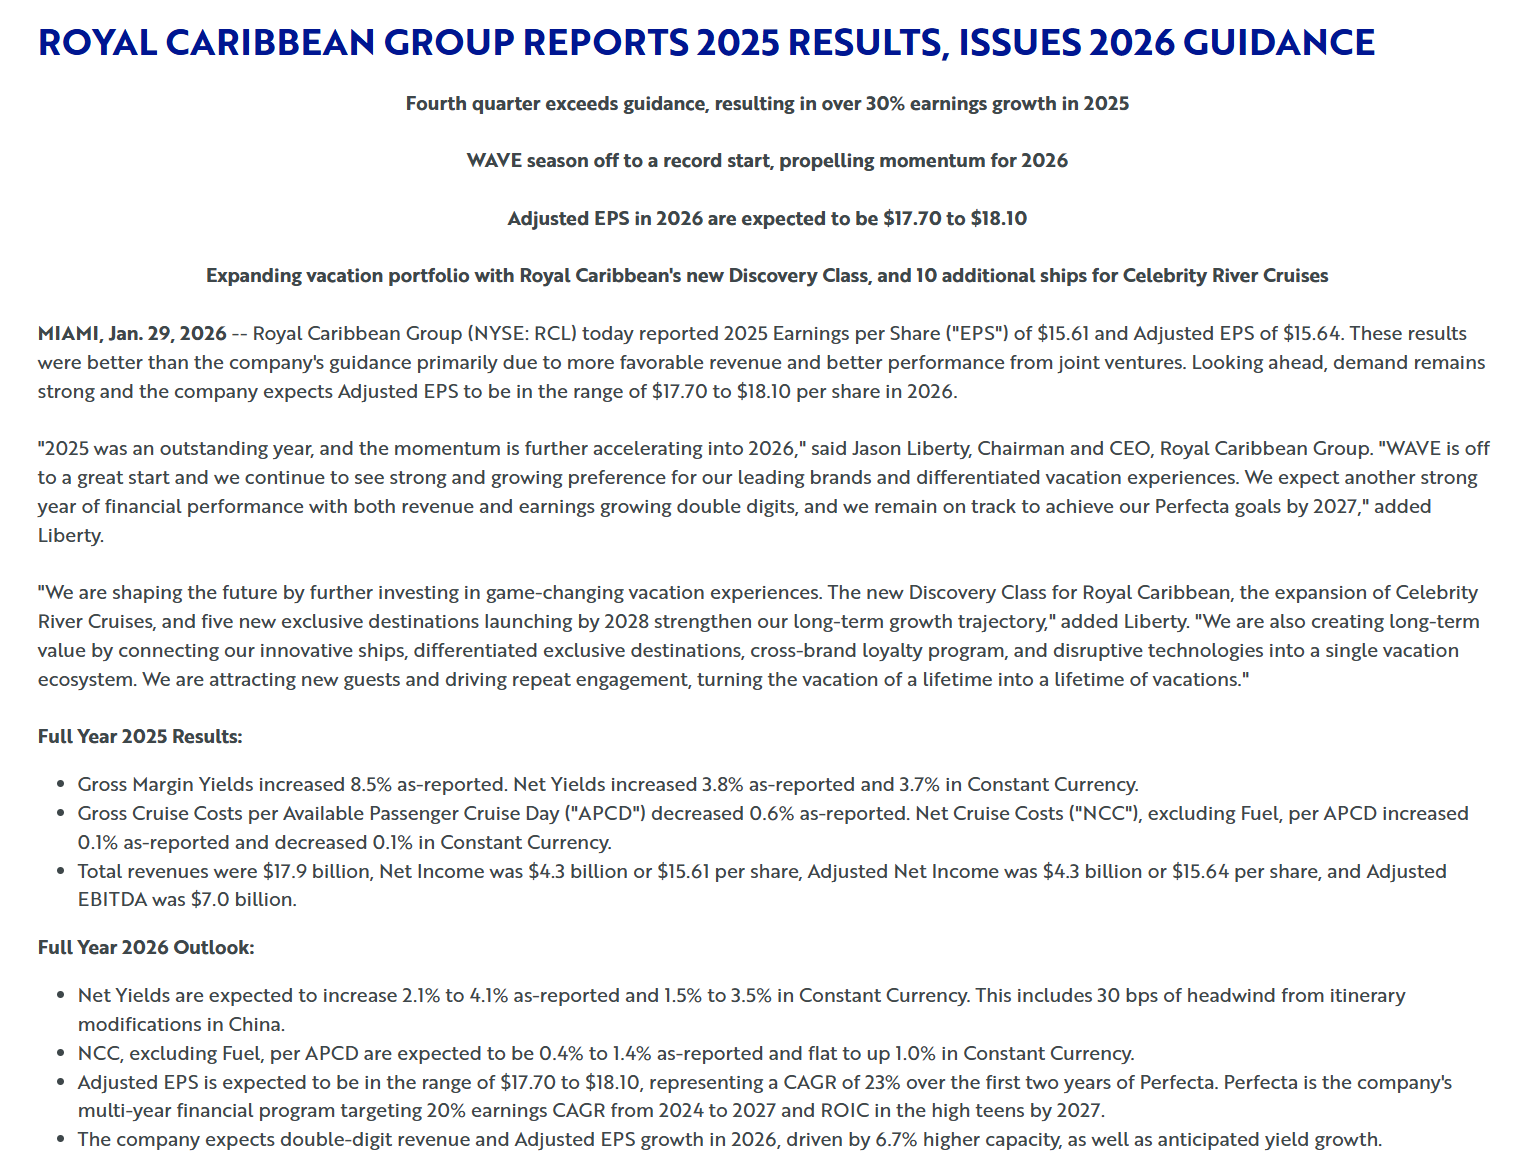
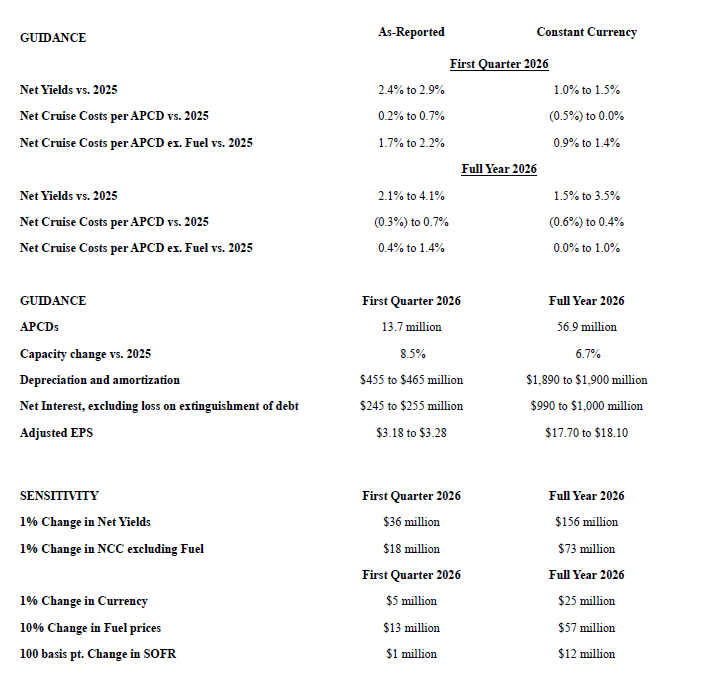
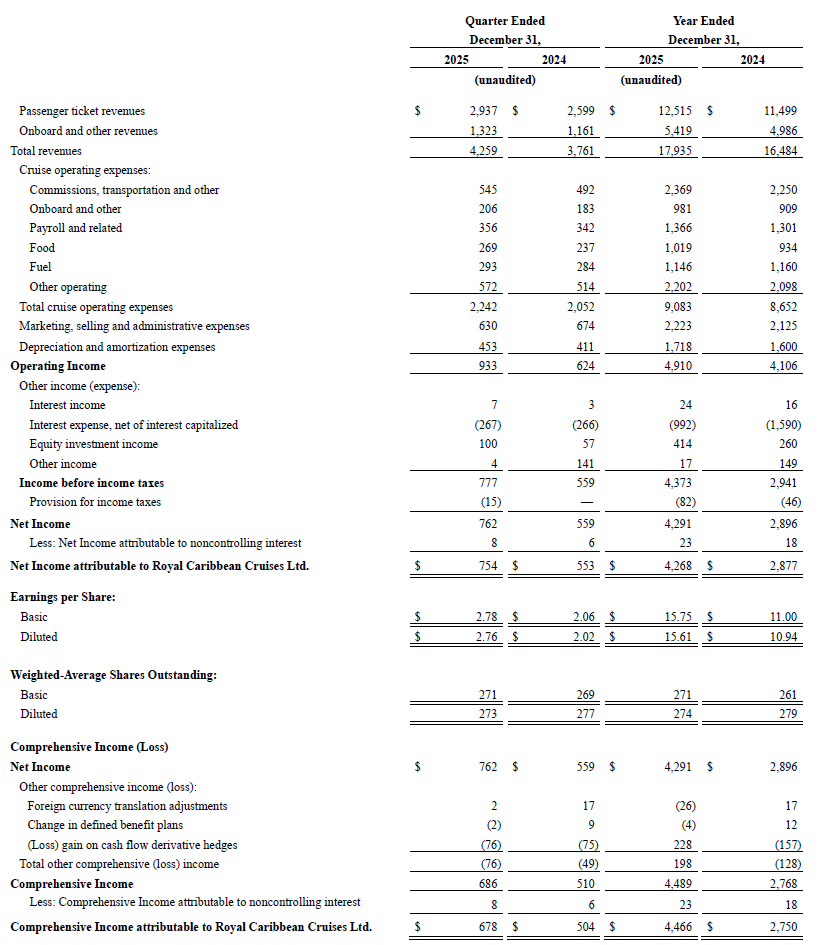
Royal Caribbean’s quarter went well; earnings and revenue grew, and customers are more satisfied than ever. Sales are strong, profitability is improving, and the company raised its full-year outlook. The future is viewed confidently, as booking levels are already strong far in advance, and at the same time, investments are being made in new ships, unique destinations, and technology, e.g., a new Royal Beach Club is opening in Santorini.
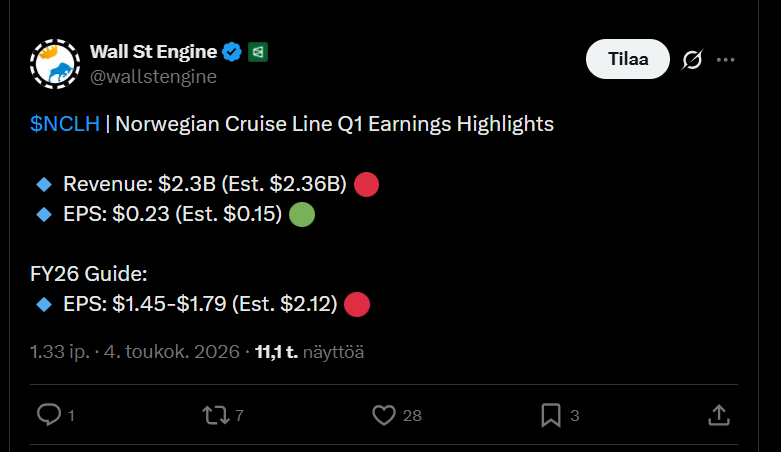
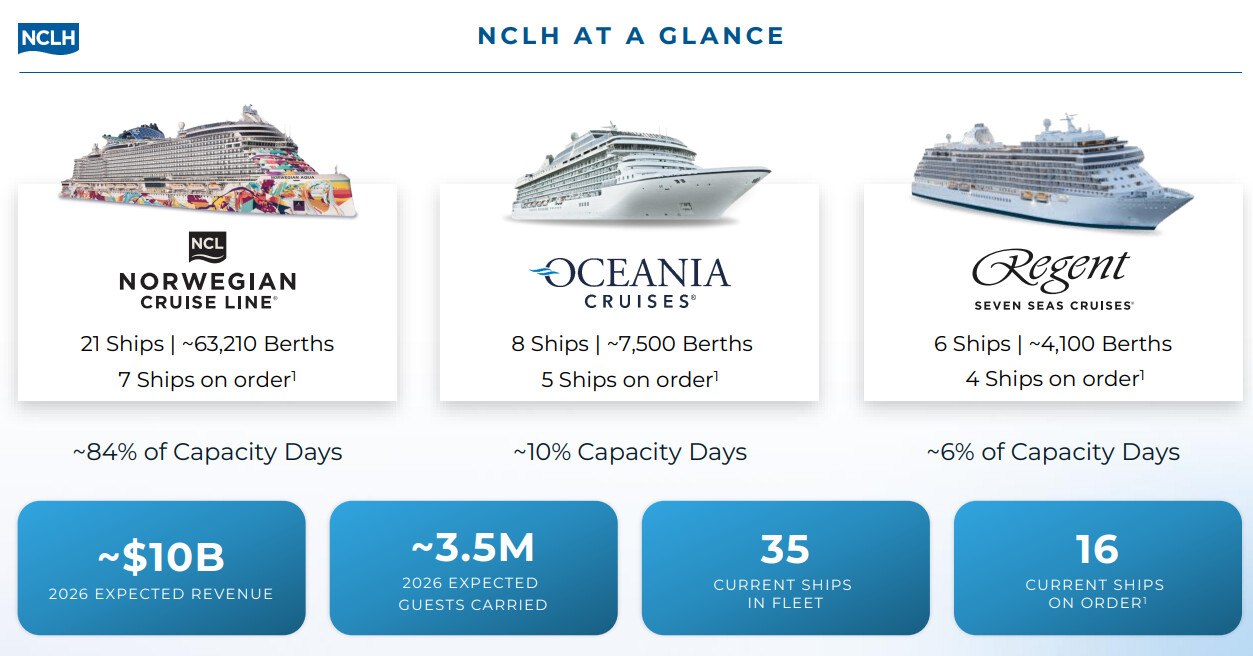
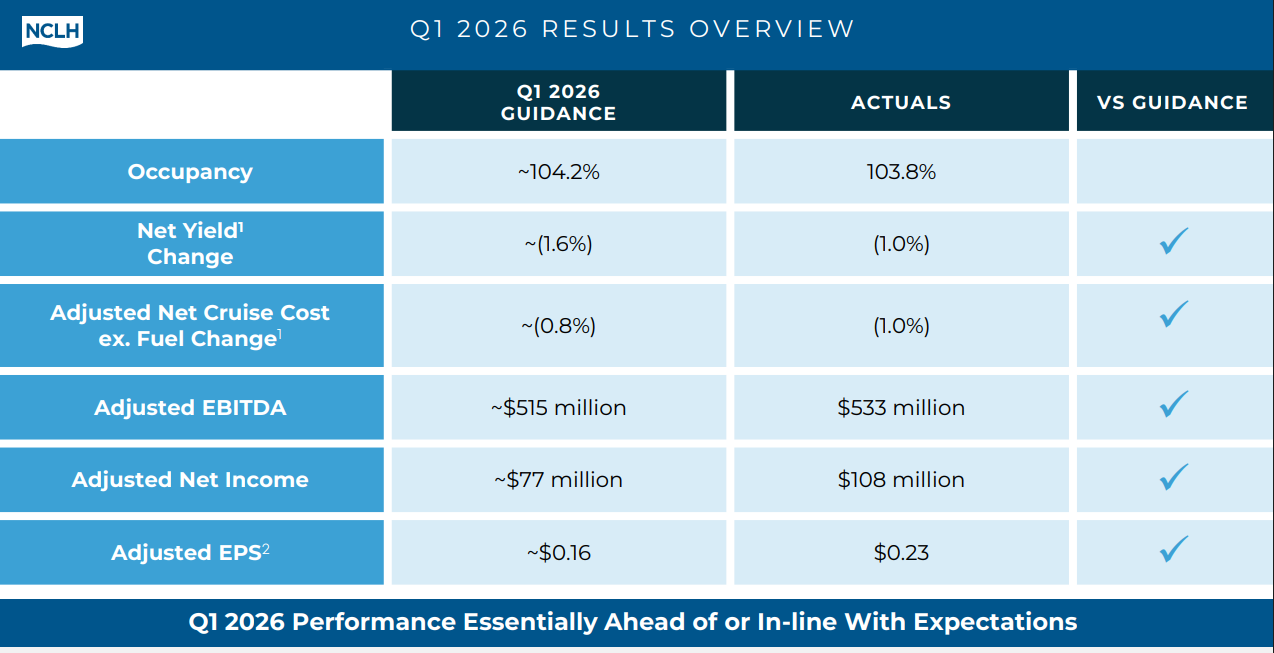
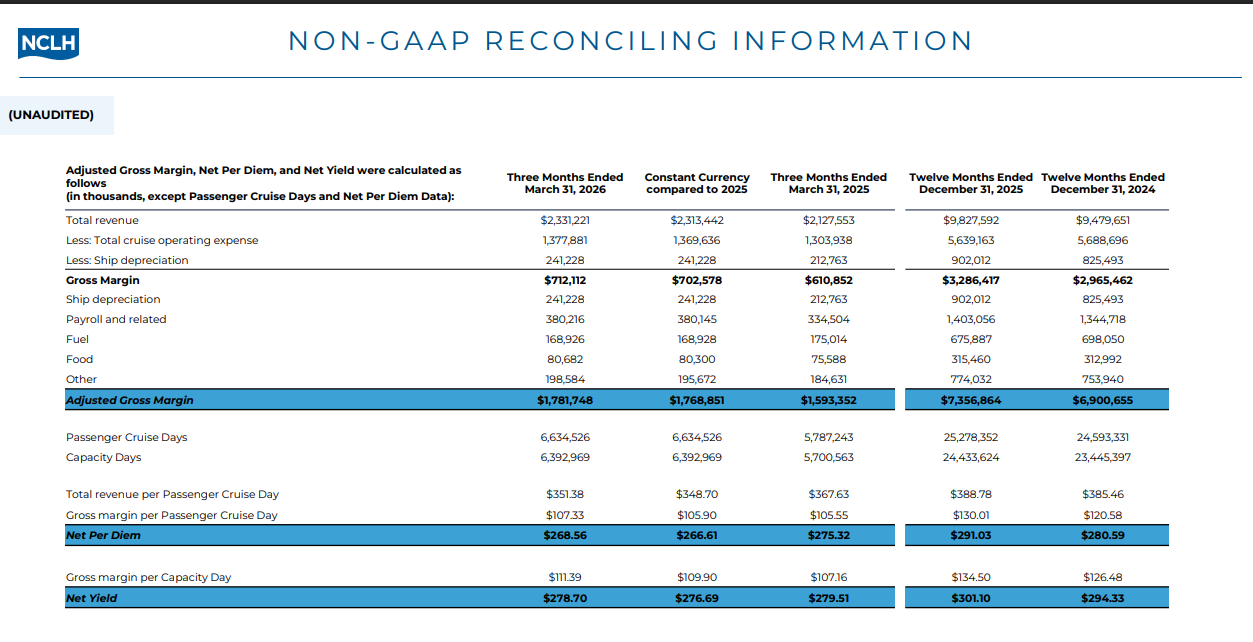
Norwegian Cruise Line achieved a satisfactory result at a quick glance, with revenue and profit growing.
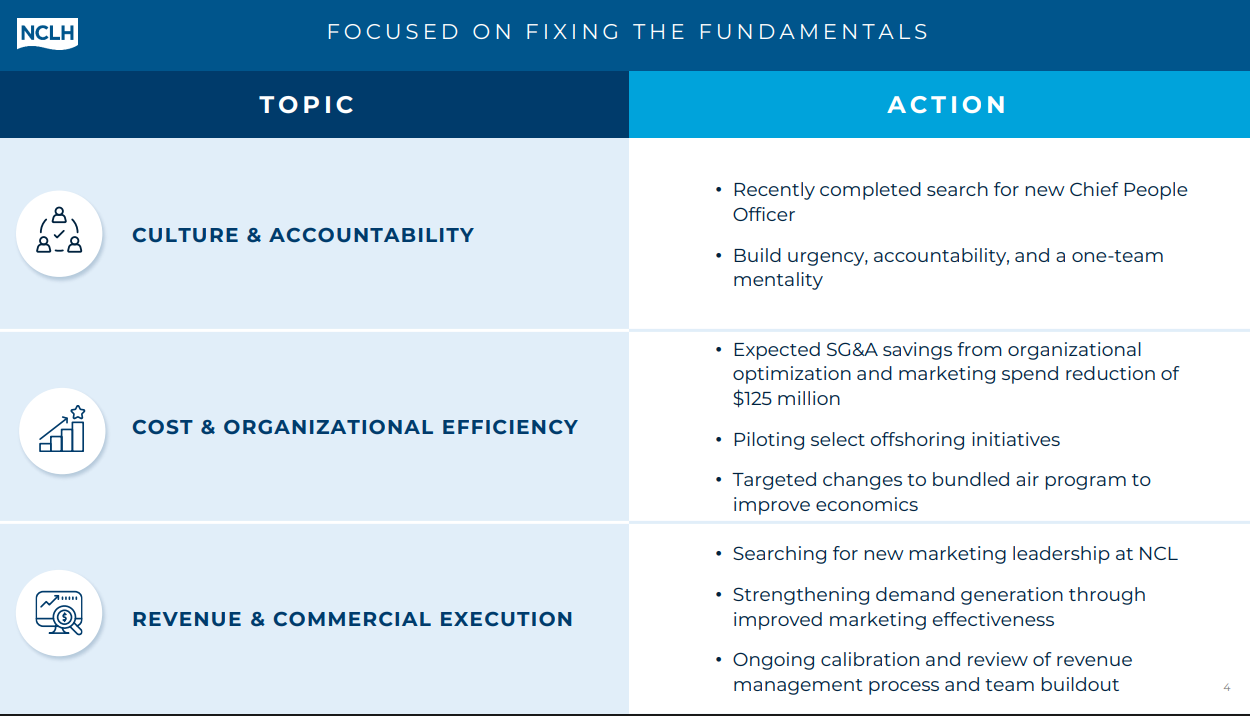
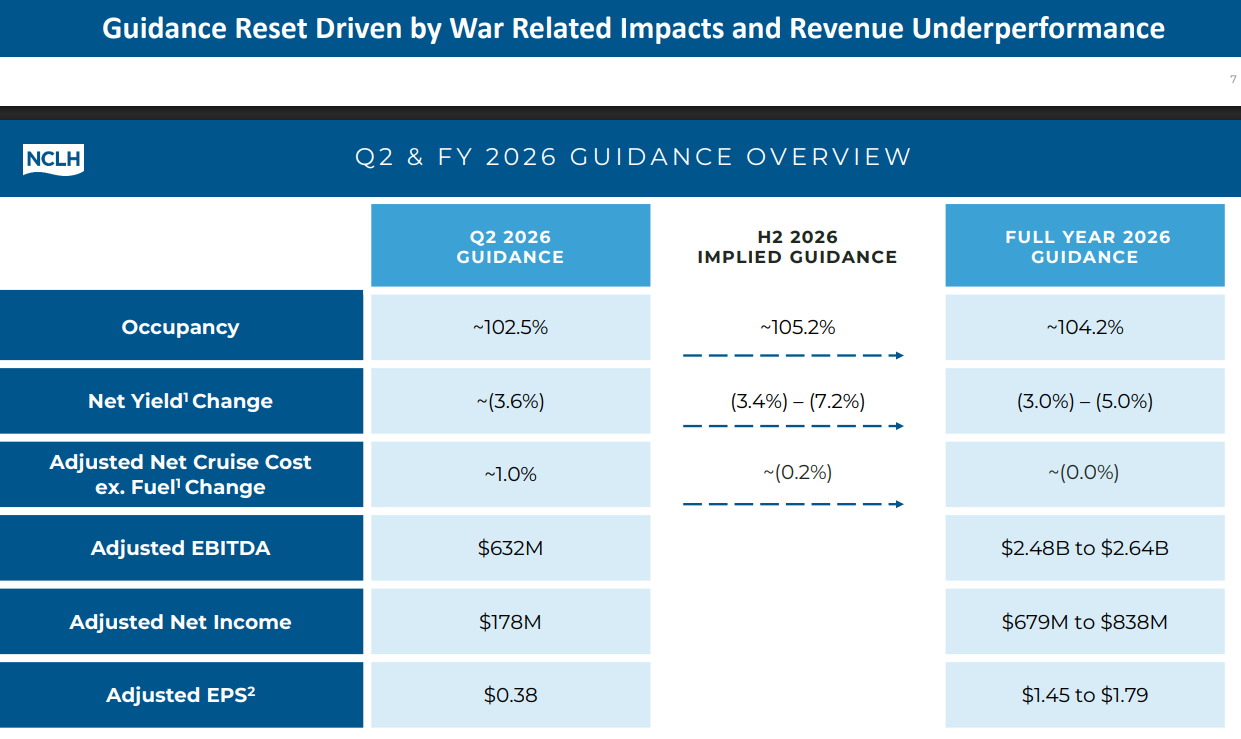
Management emphasized the strength of a diverse brand portfolio and otherwise successful operations both on land and at sea. But investors were disappointed that debt rose slightly again, even though it was supposed to decrease. Costs are also expected to grow in the rest of the year, and margins are under pressure.
The article below discusses the future of Carnival.
The article states that Carnival is heading towards significantly higher revenue by 2030. Profitability has turned positive, and debt is being reduced concurrently, even though it still amounts to as much as 26.5 billion dollars.
Credit ratings are on the rise, and analysts also expect over 13 percent annual earnings growth. The current P/E ratio of around thirteen makes the stock moderately priced, but on the other hand, a significant risk remains the high debt level and demand dependent on the economic cycle.
Carnival is looking to capture more demand in the future. It’s expanding its fleet, with plans to introduce one to two new ships per year. And it’s pushing aggressively into places like Australia and New Zealand. This should allow the company to serve more customers, which supports more revenue over time. Consequently, there’s a high likelihood that the business will be larger in 2030.
Carnival reports that it has successfully corrected its course and, to mark the occasion, is restoring its dividend.
The year was strong overall; revenue and profitability improved, and the debt burden was significantly reduced. Even the credit rating agency’s outlook supports the message that the worst risks are behind them.
At the same time, the company admits that cost pressures continue, which may cause volatility in the next quarter’s earnings performance. Growth relies heavily on pricing power, as capacity is being increased cautiously. Booking demand is brisk, however, which brings a bit more light to the future.
The end of last year went roughly as expected, and the ships were full of passengers. Demand for future trips is also at record highs, and on top of that, the company managed to keep costs in check, although revenue fell just slightly short of expectations.
The best part of the report was likely the future outlook, which is mostly bright, as bookings are reportedly pouring in at a heavy pace. In this regard, expectations were exceeded once again.
I couldn’t find an existing thread other than for cruise ships, so I thought I’d open a new one. The travel industry is in a sharp decline, and the ongoing crisis is unlikely to affect everyone in the same way. Many travel companies also pay good dividends. Pandox has risen sharply in recent years. Personally, I’m considering re-buying Scandic if the share price drops. Do the rest of you have any travel industry stocks on your watchlists? I’m also considering Accor, but I don’t remember how much business they have in the Middle East.
Carnival’s performance was exceptionally good, leading the company to raise its future earnings outlook.
Demand for cruises has remained very high, and strong pricing and comfortably filling booking calendars indicate robust momentum and passenger confidence. The company is transitioning from debt reduction to a new strategic phase, where the focus will increasingly shift towards rewarding shareholders and long-term value creation.
However, significant challenges, of course, include fuel price fluctuations and simply the general increase in costs. Despite the uncertainty, the cruise industry’s growth cycle appears stable, and experiential travel continues to attract consumers despite global uncertainty. This development reflects a shift from recovery to sustainable and profitable business operations.
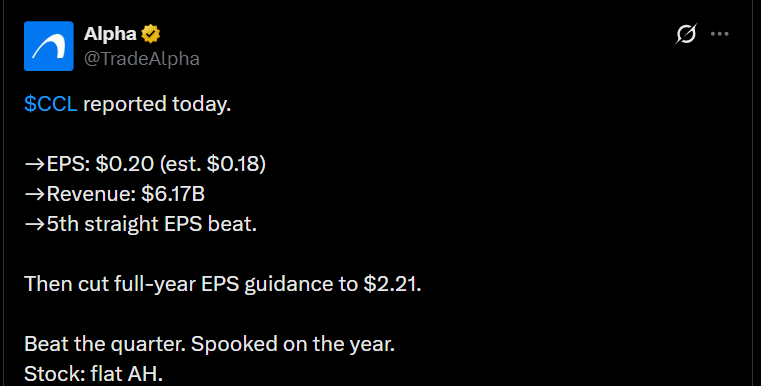
Norwegian Cruise Line reported quite good figures for Q1. Revenue, EBITDA, and earnings per share exceeded forecasts; additionally, the occupancy rate remained high.
However, the share price fell because the company lowered its full-year earnings guidance due to geopolitical risks and a decline in net yield per passenger.
Carnival’s results were overall quite okay; although revenue slightly missed expectations, the key profitability figures exceeded forecasts.
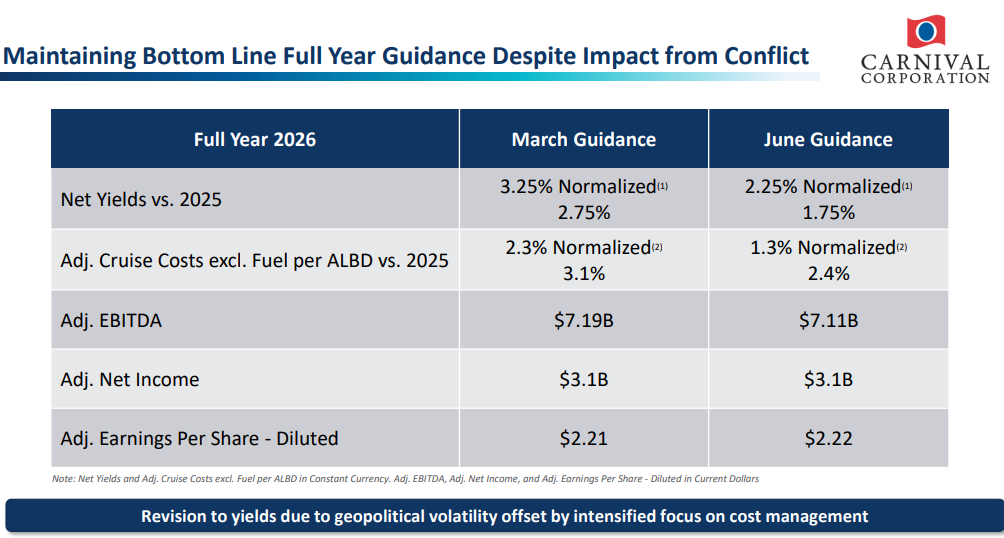
Demand for cruises still looks good, bookings are high, and the company is even able to raise prices. Rising fuel costs and tensions in the Middle East weighed on the result, but then again, cost discipline compensated for much of it. The outlook remained fairly okay.