Expansion is indeed a goal, Nu is applying for an operating license for the US market
September 30, 2025 – Nubank (NYSE:NU), one of the world’s largest digital financial services platforms, announced today that it has applied for a national bank charter with the Office of the Comptroller of the Currency (OCC) of the United States. This undertaking is aligned with the company’s intention to explore future international opportunities by evolving its regional platform into a global model. Pursuing a U.S. national bank charter positions Nubank to unlock new possibilities within the U.S. financial landscape.
primarily expanding service to the existing customer base
At the same time, applying for a U.S. national charter helps us better serve our existing customers based in the country and, in the future, connect with those who share similar financial needs and could benefit from our products and services,” said David Vélez, founder and CEO of Nu Holdings.
Amazon’s Brazilian division and Nubank have announced a partnership, making NuPay a payment option in Amazon Brazil’s online store. This offers Nubank customers, among other things, the use of an additional credit limit and various installment payment systems. And as is customary with Nubank, this is a completely digital operation, requiring no external devices like a
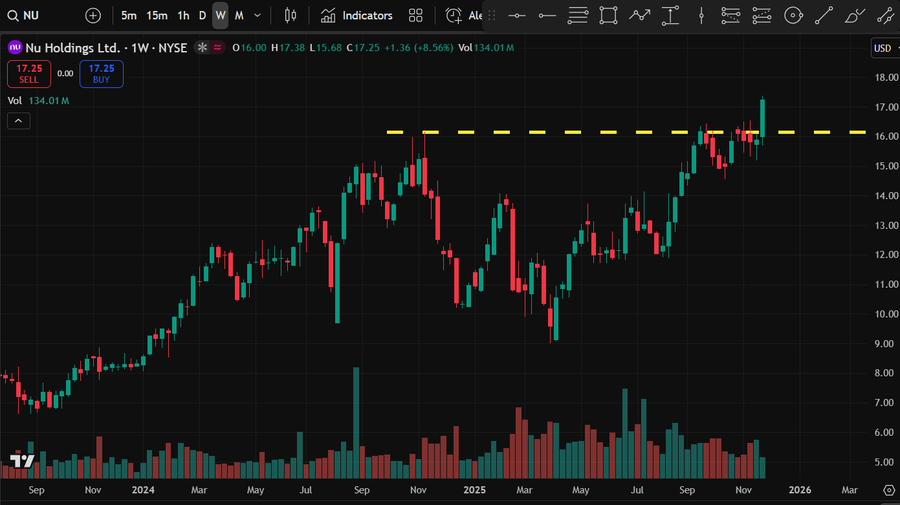
Tomorrow, after the market closes, NU Holdings will release its results. Paper-hand Buffett sold Berkshire’s stake at the beginning of the year, at around USD 11.8. Now the share price has been around USD 16. Even masters don’t always get it right, which has (at least so far) served as a good buying opportunity for me. So thanks for that.
But let’s stop the chatter and get to the point, which is tomorrow’s earnings report. Expectations (which vary surprisingly much between different sites):
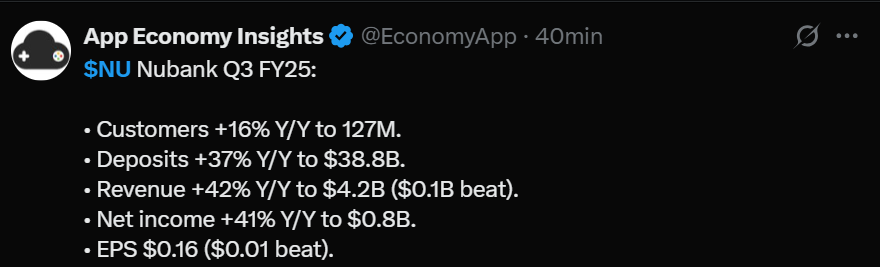
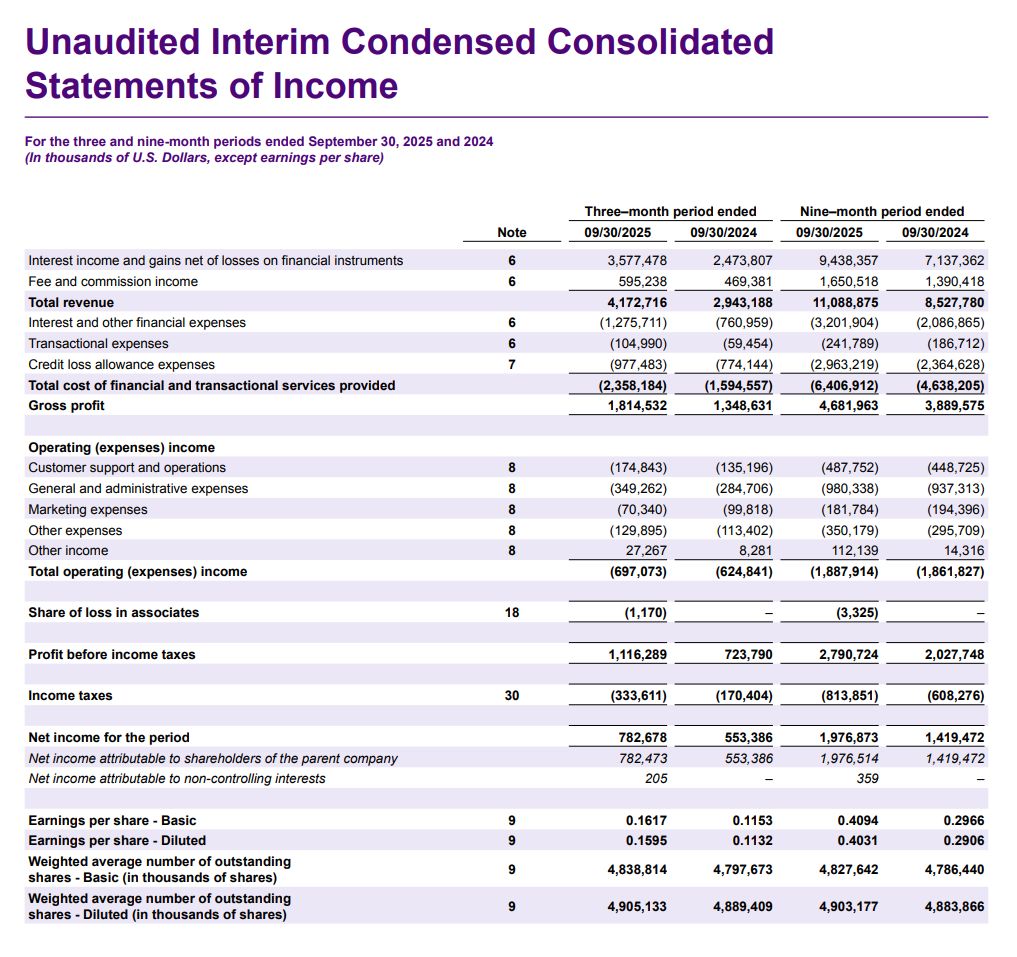
Revenue 4.0 bn USD EPS 0.15 USD
In addition to just the hard numbers, I’ll be following the number of monthly active users, as well as, of course, the development in Colombia and Mexico.
The company isn’t getting off easy again, as revenue forecasts would be approximately 37% YoY growth and EPS approximately +25% YoY growth.
I predict an overshoot on revenue and EPS to hit the forecasts!
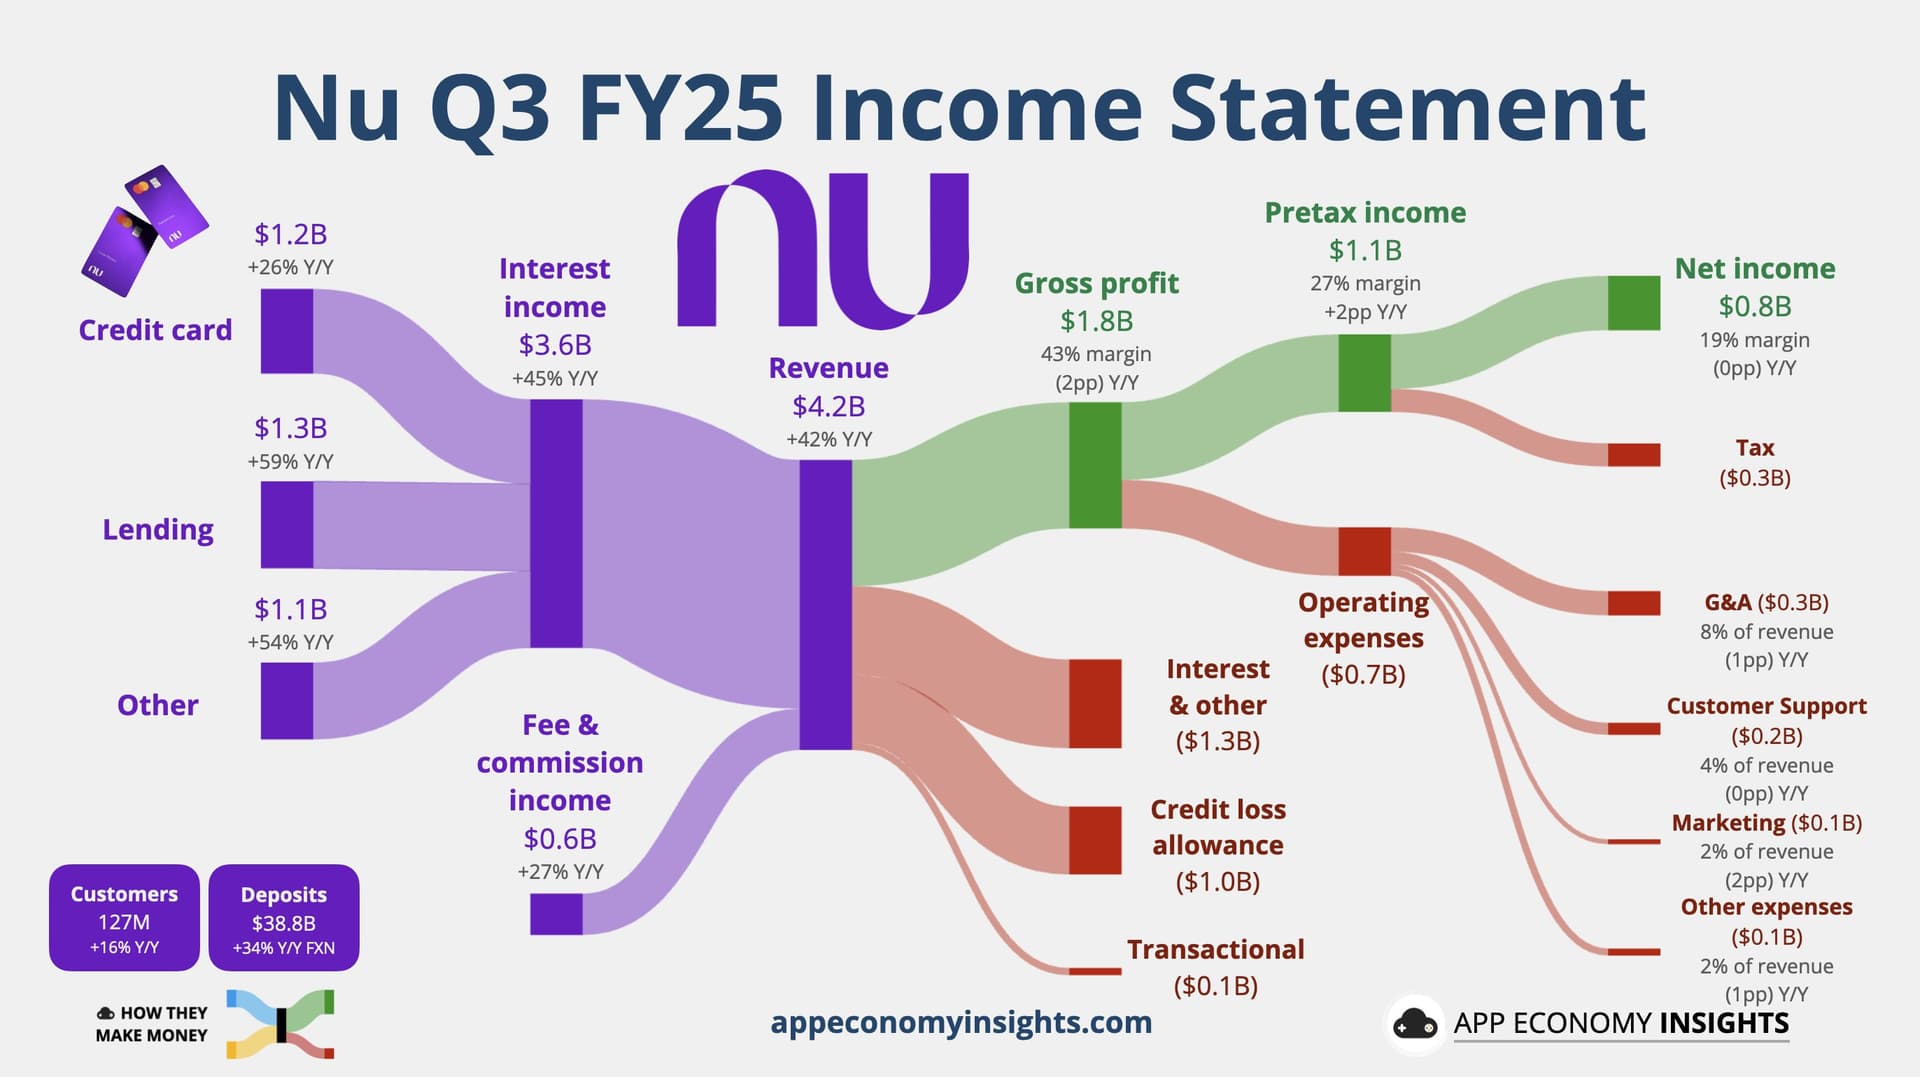
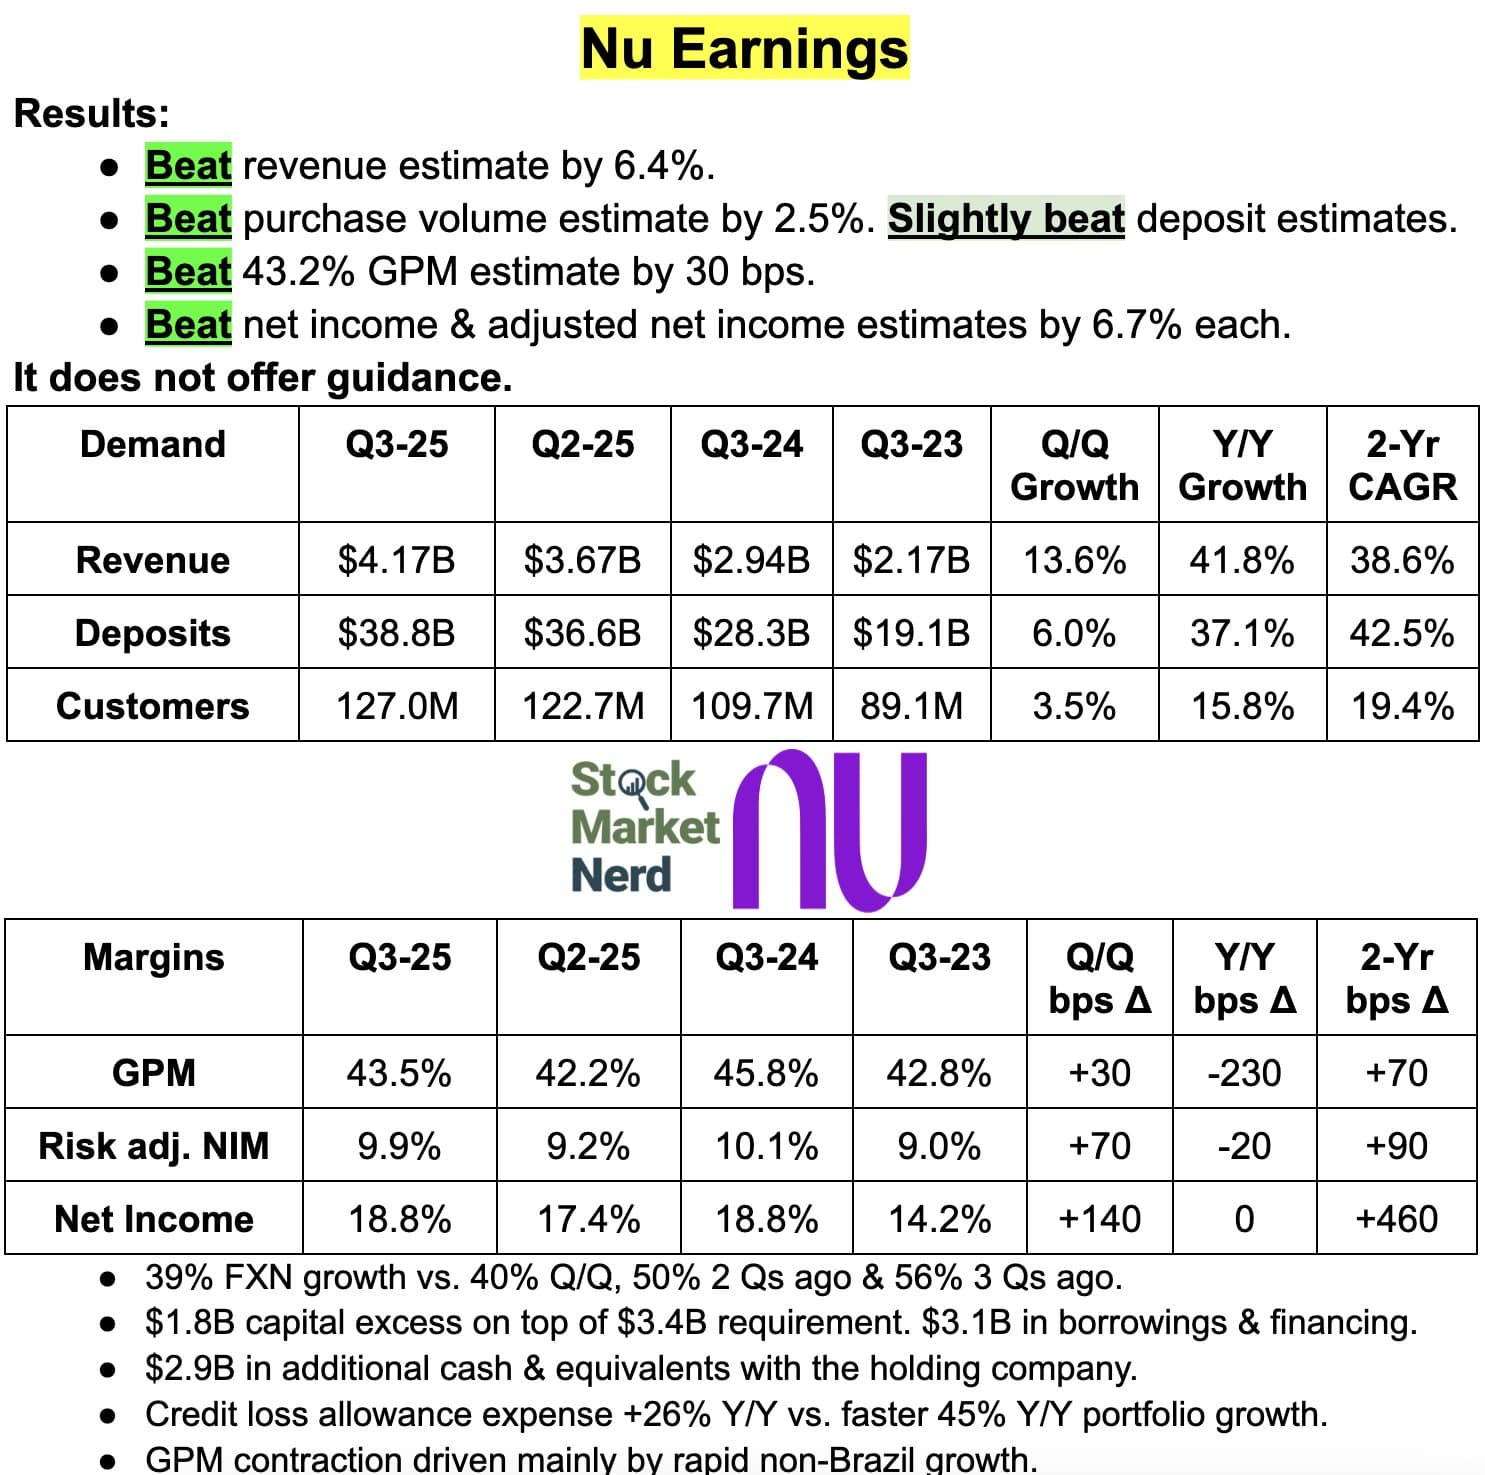
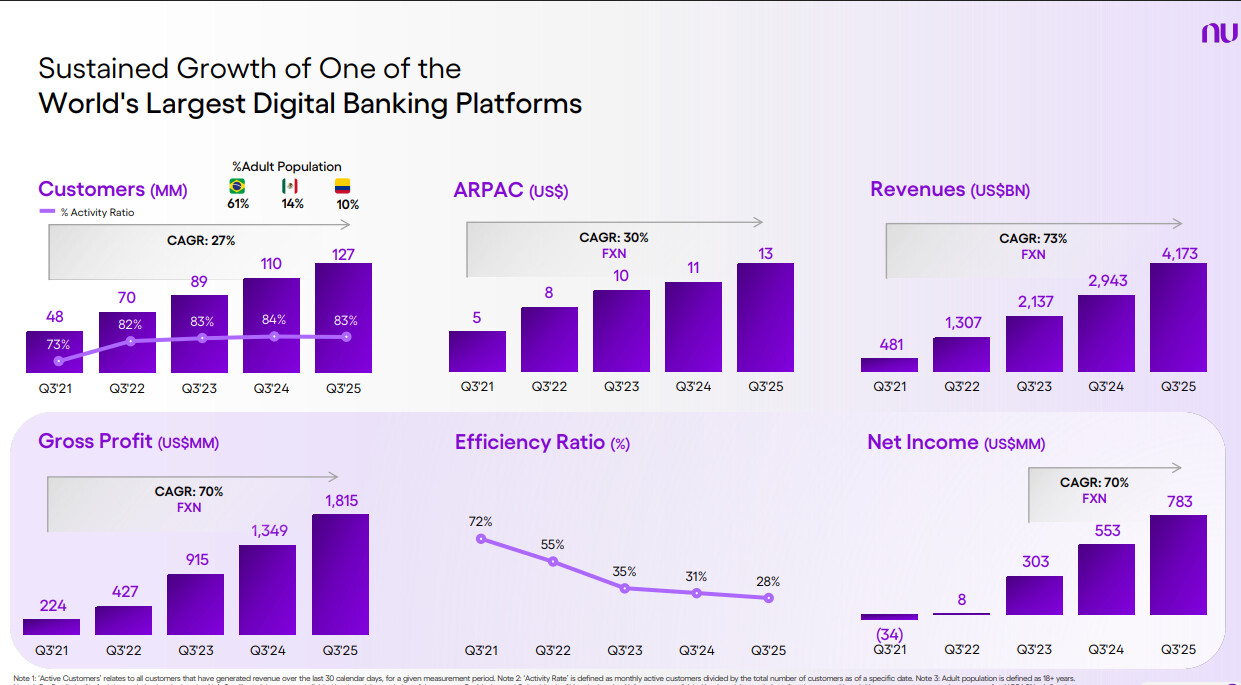
Nu continues its rapid growth and strengthens its position. The customer base has grown rapidly, users remain active, and the average revenue per customer is steadily increasing. Additionally, revenue and margin have improved dramatically, which indicates the overall effectiveness of the package on a large scale.
Efficiency has clearly improved, and the result has turned from a loss into a strong profit. Nu has successfully captured market share in Brazil, Mexico, and Colombia. The company now appears to be operating significantly more profitably than before.
I’ve been following this thread for quite a while now, and I’m seriously considering jumping on board.
At least these positive drivers have been on my mind in the big picture:
Growth and cost-efficiency are excellent quarter after quarter. For example, in Brazil, Nu is already the third-largest bank by customer count?
LatAm economies are growing, and with them, people’s wealth. If Nu can get a hold of a large customer pool now (which seems promising), this could pay off big in the coming years and decades.
US expansion: this doesn’t seem to be priced into the stock much at the moment? However, I believe there’s an incredible opportunity here. US banks are incredibly expensive, and their service is poor, especially for lower-income individuals. Nubank could certainly serve this segment cost-effectively and could genuinely gain a very large foothold, especially starting from the lower-income end. Additionally, they could have a good chance of attracting Spanish-speaking people away from mainstream banks.
From what I’ve heard in CEO interviews, he clearly seems like a passionate doer, which is always a plus.
Questions:
A P/E of over 30 isn’t bad for a growth company, but on the other hand, at its core, this is a bank (albeit a slightly different one) - is the price tag still quite high? On the other hand, if growth continues at this rate, that too will melt away over time.
I’ve never invested in LatAm companies. Although this is listed in the US, I don’t really have a clue how LatAm companies are valued in general from a market perspective (cf. e.g., multiples of Chinese companies, etc.).
The death/decline of traditional banks has been shouted about throughout the 2000s. Will traditional players really rest on their laurels in their core markets if Nu starts to seem like a threat, and won’t they be able to compete successfully against Nu? Nu’s operations, in my opinion, rely on extreme cost-efficiency, and tightening competition could probably easily undermine this.
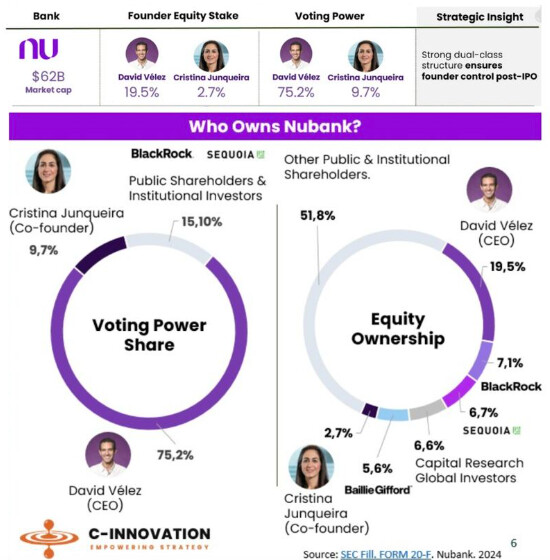
In Brazil, the SELIC policy rate is 15% and inflation is 5%, meaning the real risk-free rate is 10%, which does not directly attract risk investments. I cannot say how the ownership structure is distributed, meaning whether it is priced as a Brazilian stock, and there the historical P/E levels <10
Well, today we made another ATH again, and I guess we’ll go forward from here. Those banking things are quite old-fashioned compared to Finland. Some indicator could give big gains if you trust them.
NUBANK INTENDS TO OBTAIN BANKING LICENSE IN BRAZIL IN 2026
The Nubank brand and visual identity will remain unchanged; the company holds all required
operational licenses to offer its current suite of products and features.
São Paulo, December 3, 2025 - Nubank, one of the world’s largest digital financial services platforms, announces its intention to obtain a banking license in Brazil. The inclusion of a banking institution within the conglomerate complies with the provisions of Joint Resolution No.17, issued by the Central Bank and the National Monetary Council, which standardizes brand name usage for regulated institutions. With this decision, the Nubank brand and visual identity will remain unchanged.
This announcement will have no impact on clients, and all operations shall proceed normally. Nubank has more than 110 million customers in Brazil.
“Nubank was founded 12 years ago and has been responsible for the inclusion of 28 million individuals in the financial system. Our identity and mission to simplify our customers’ lives will remain the same,” states Livia Chanes, CEO of Nubank in Brazil.
Currently, Nubank fully complies with all applicable regulations, and operates with all necessary licenses as a Payment Institution, a Credit, Financing, and Investment Company (Sociedade de Crédito, Financiamento e Investimento), and a Securities Brokerage Company (Sociedade Corretora de Títulos e Valores Mobiliários). The inclusion of a banking institution within the conglomerate does not materially alter additional capital and liquidity requirements—the financial solidity and resilience remain unaltered.
In summary, the bank’s status is formalized from the current fintech situation. No changes to the customer interface.
Summary: why this matters
In short: Nubank is evolving from “fintech + multiple special licences” to “fully licensed bank + fintech platform.” The change is largely formal and regulatory — for customers and daily business, little will change. But it helps Nubank align with stricter regulation, likely improves trust and stability perception, and gives it flexibility for future banking-style expansion more like a traditional bank
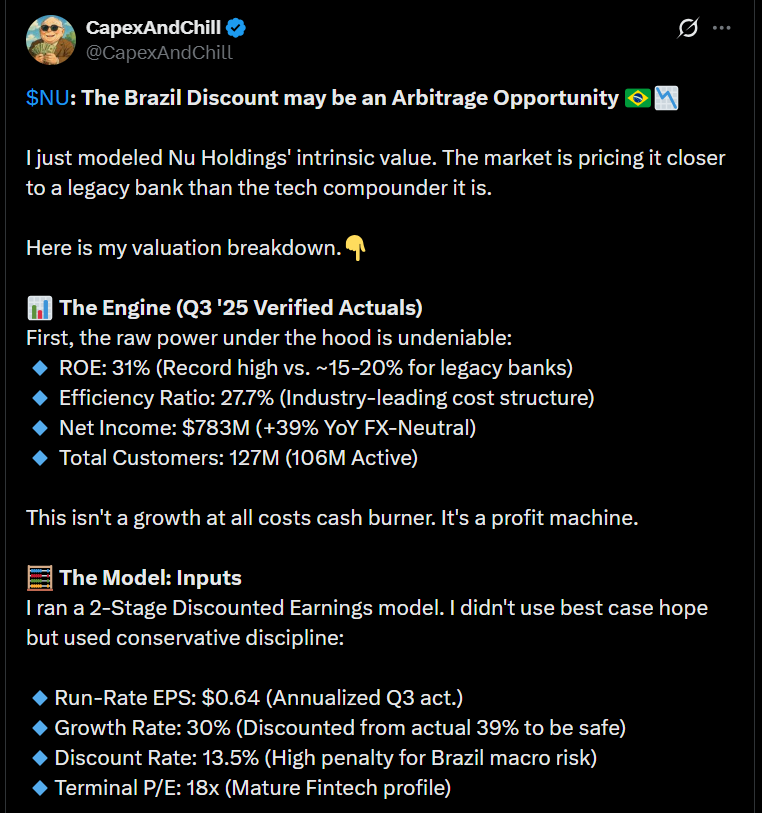
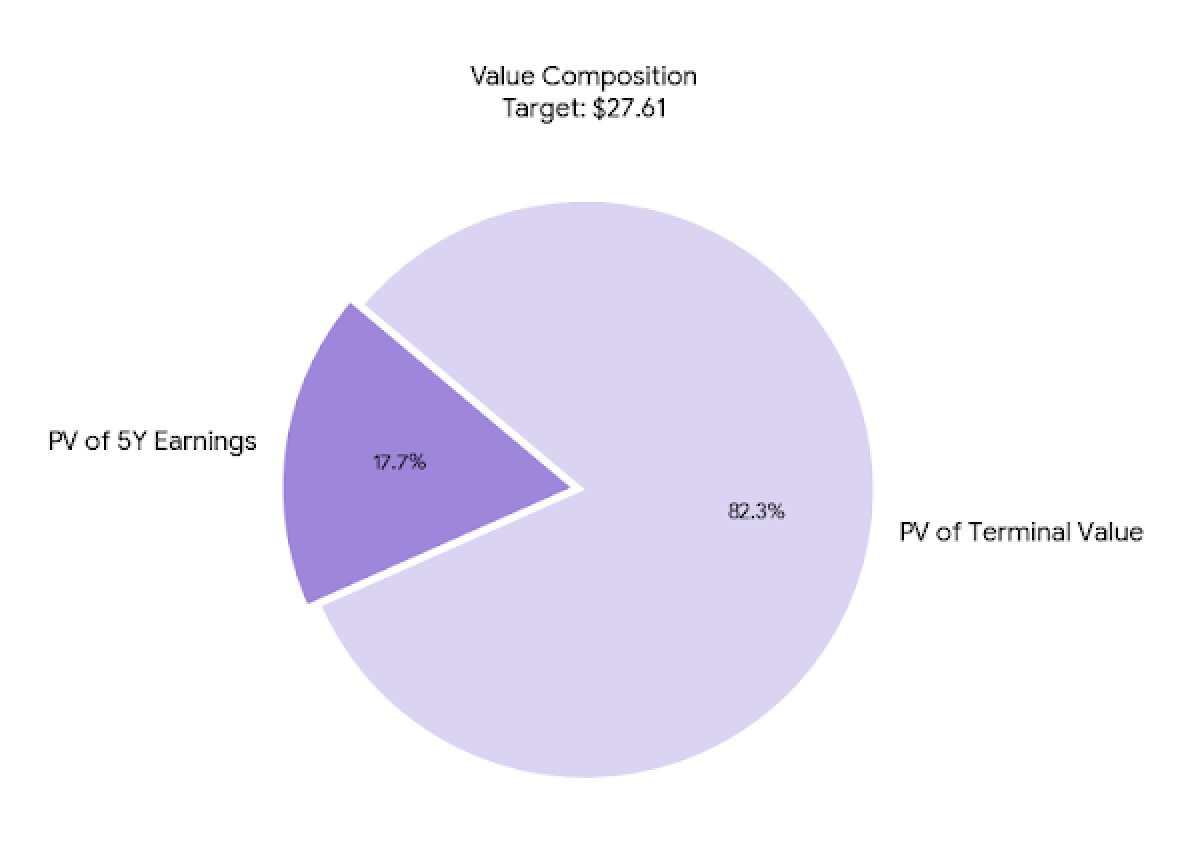
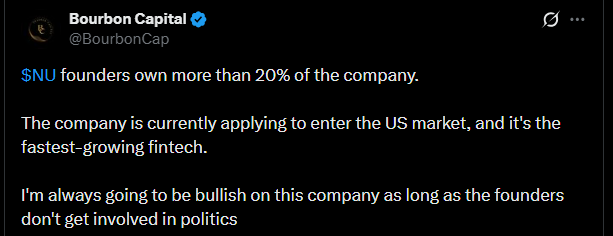
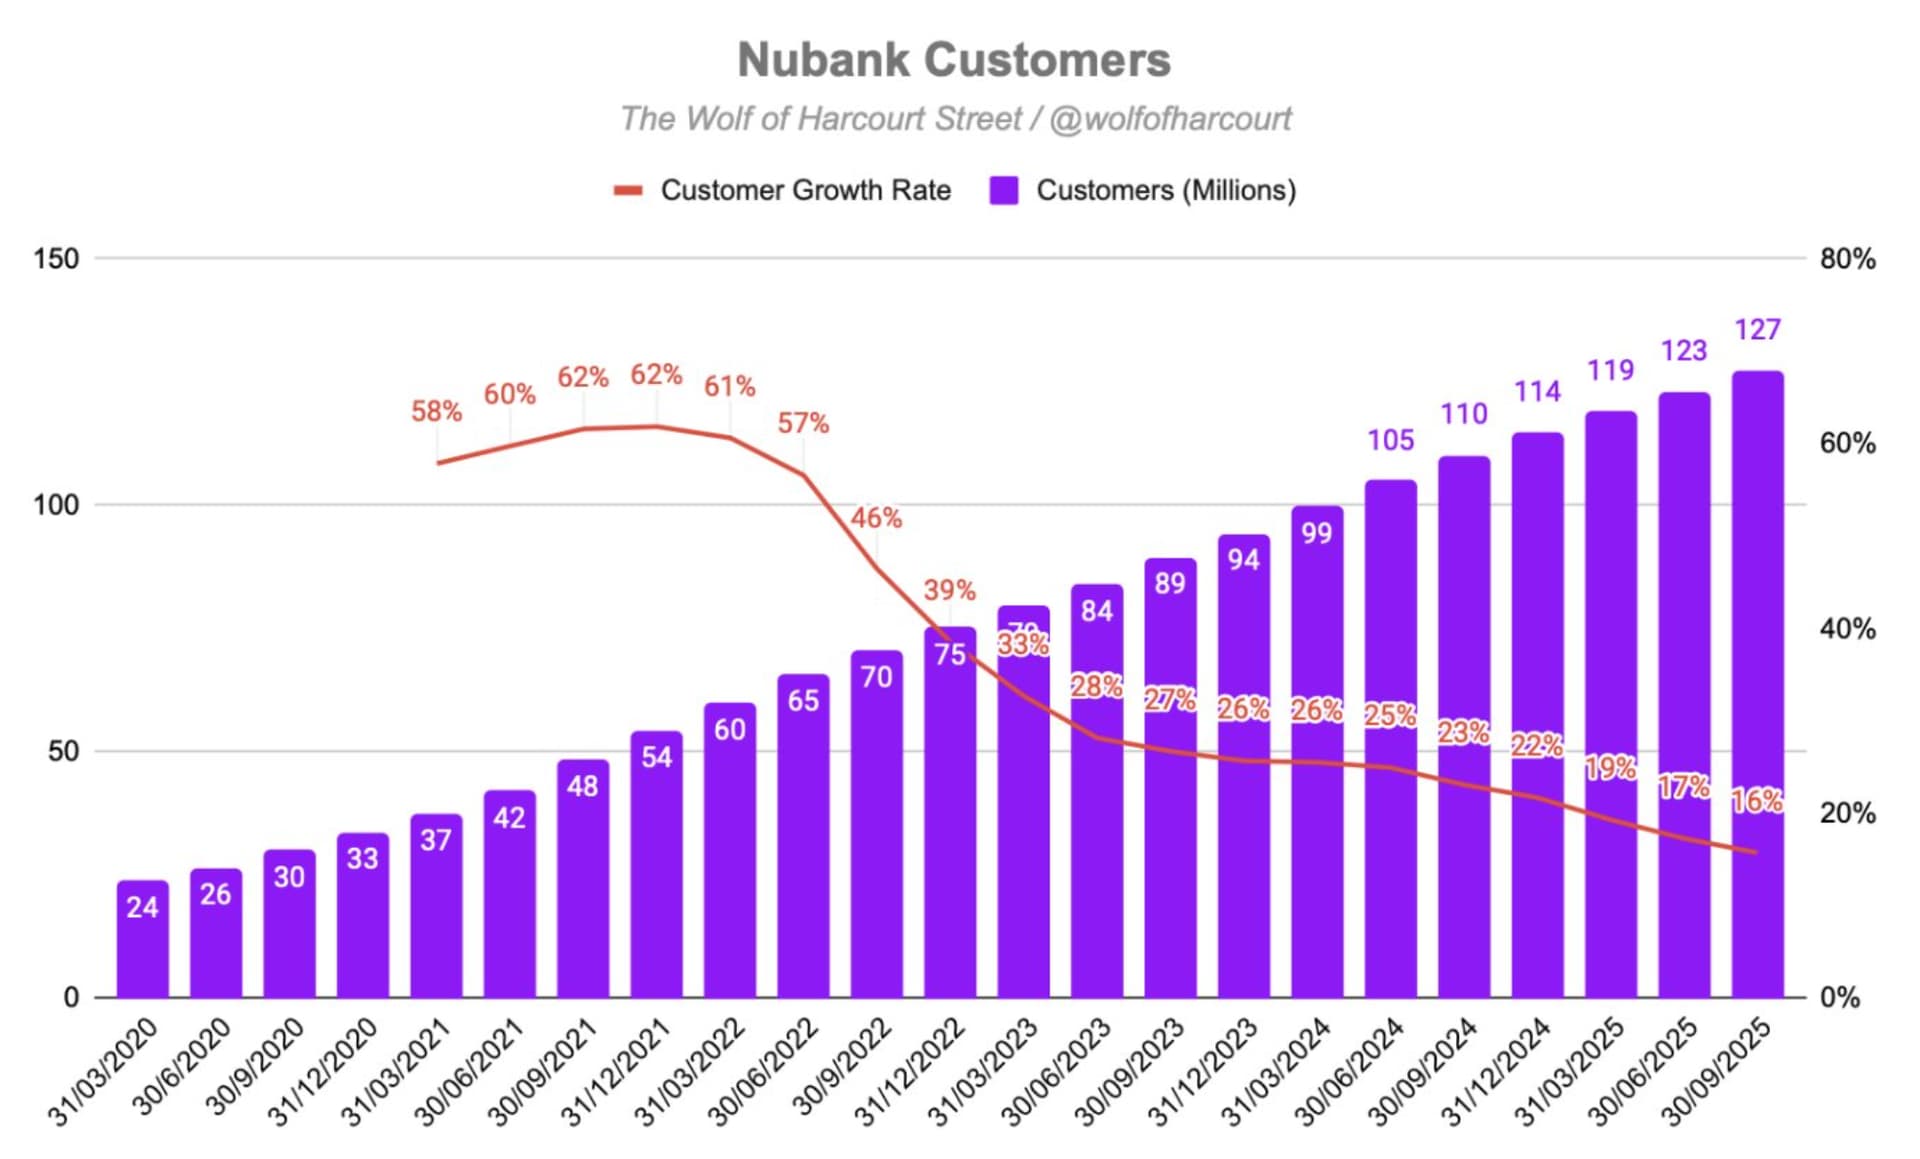
The tweet below states that Nuuuuun’s stock is priced in the market like a traditional bank, even though its profitability and growth are top-notch (ROE 31%, cost/income ratio 27.7%, customers 127M).
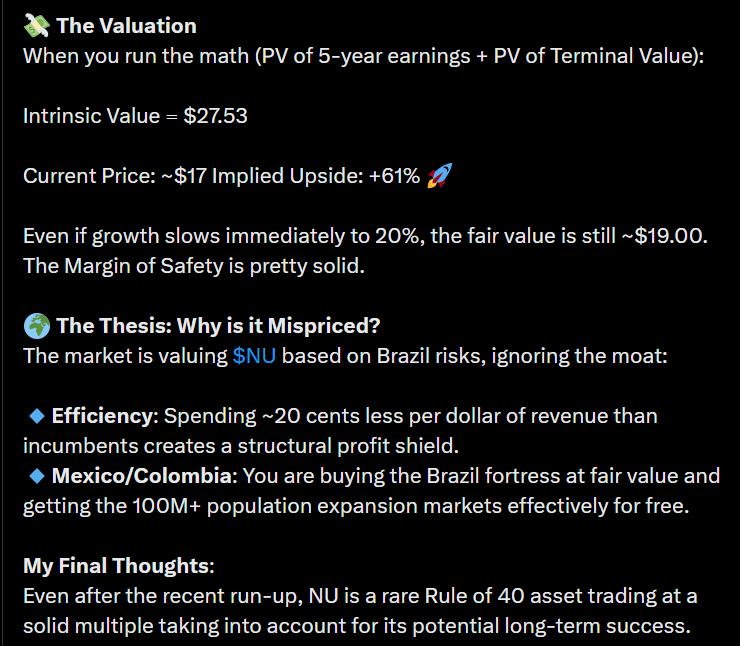
The “fair value” would reportedly be $27.53, which is 61 percent higher than the current price.
The market reportedly undervalues Nu’s growth and efficiency advantages, as well as its expansion into Mexico and Colombia.
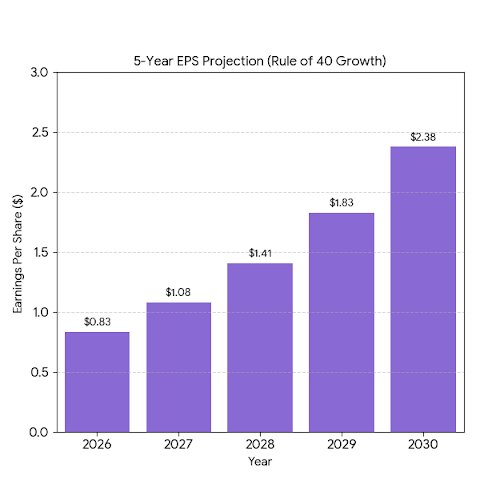
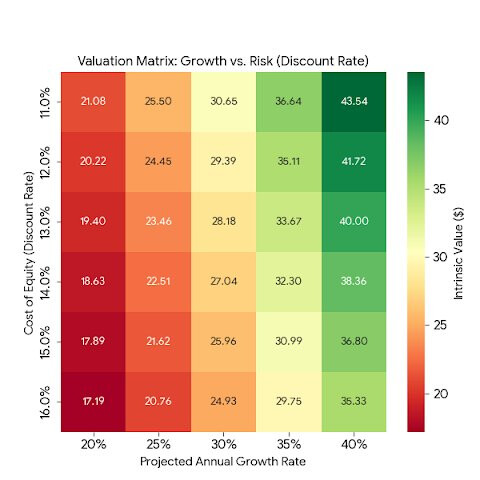
More on these and a bit more from the tweet below:
Conditional approval for US banking operations received
Nu (NYSE:NU), one of the largest digital financial services platforms in the world with 127mm customers, today announced that it has received conditional approval from the Office of the Comptroller of the Currency (OCC) of the United States for the formation of a de novo national bank, Nubank, N.A. The conditional approval represents a milestone in the company’s long-term strategy to expand its operational footprint and product offerings in the United States. Once fully approved, the national bank charter will allow Nu to operate under a comprehensive federal framework, facilitating the launch of deposit accounts, credit cards, lending and digital asset custody.
And it should be fully operational in a year to a year and a half.
Nu has now entered the bank organization phase, which involves satisfying specific OCC conditions alongside pending required approvals from the FDIC and the Federal Reserve. During this phase, the company will focus on fully capitalizing the institution within 12 months and opening the bank within 18 months, as required by regulators. Nu submitted its application to the OCC on September 30, 2025.
I believe it was mentioned earlier that the US market is not intended to be fully comprehensive, but rather, at least initially, to support the operations and customers of the main markets. So, it wouldn’t be a very significant growth platform, at least at first.
Could someone more knowledgeable confirm the following?
If a company operates mainly in a currency other than USD, but still reports its results in USD, isn’t it to the company’s own advantage if the USD weakens against that operating currency? Or at least an advantage for the stock price?
This was more of a general question. But if that rule applies, how well does it apply to Nu Holdings? Or have I misunderstood something, as the share price has also fallen along with the others?
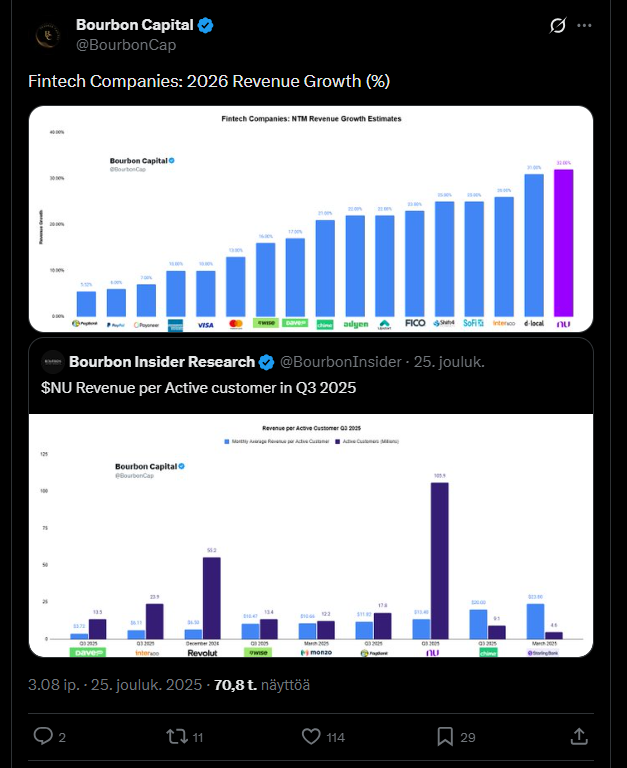
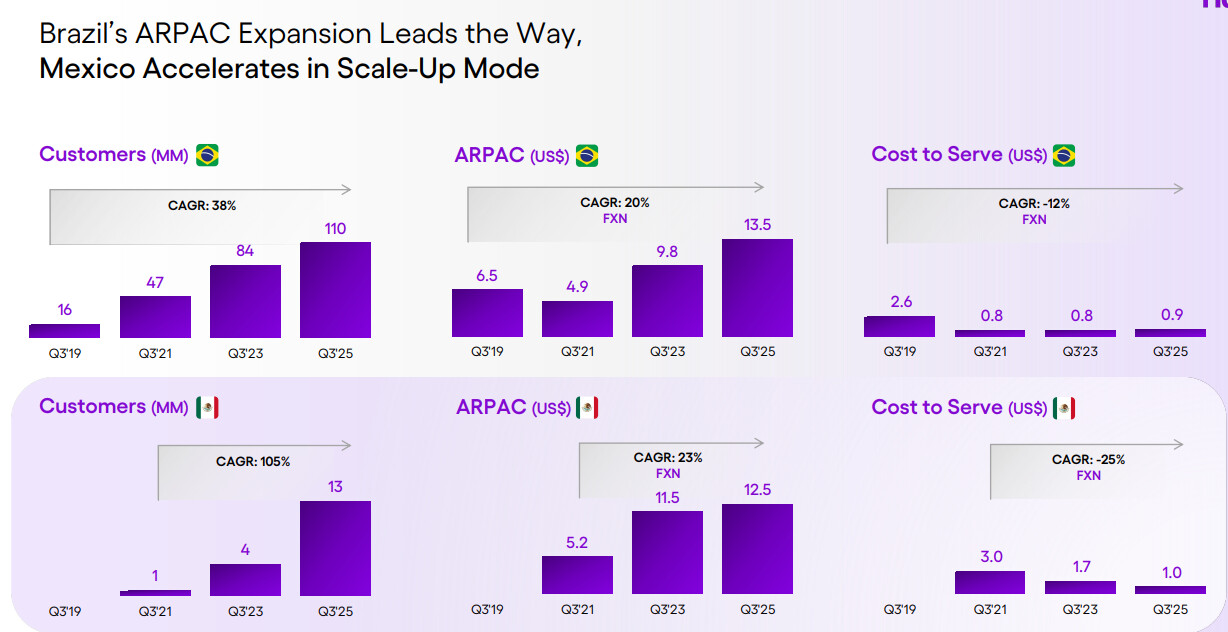
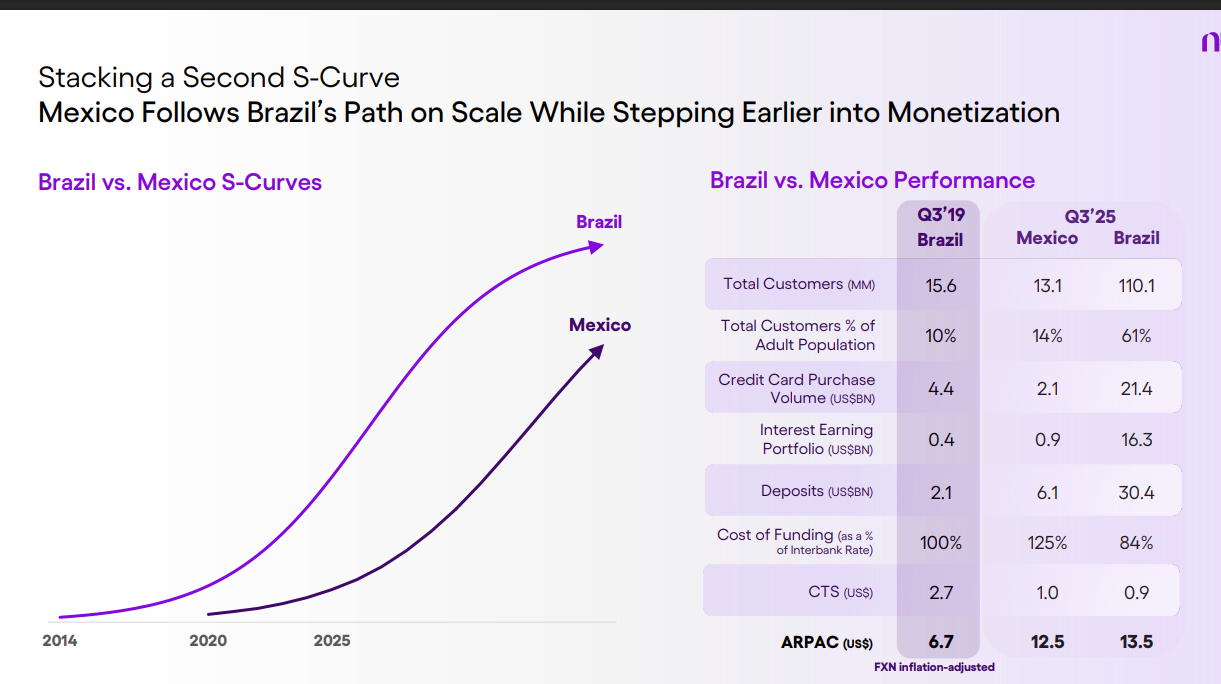
Some number cruncher could calculate what kind of growth figures could potentially be expected simply by comparing the left and right images. The company already has over a hundred million customers, so relative growth will inevitably slow down in Latin America. Revenue growth will certainly be something else entirely if monetization stays even close to historical levels.
SalkunRakentaja has a short article on Nu Holdings that can be read in a few minutes. Much of it is likely familiar to many, but I think it’s a good overview of the company.
Nubank’s management has emphasized that revenue per customer is still significantly lower than that of traditional banks. This means there is plenty of profit potential remaining even without new customer acquisition, simply by deepening existing customers’ use of services.
Subheadings:
Convincing and profitable growth
A moat built from many layers
Growth outside Brazil is only just beginning
Note.
The author owns shares in Nu Holdings. The article is not a recommendation to buy the company’s shares. The SalkunRakentaja website does not provide investment recommendations.
Nubank plans to invest around 8.2 billion dollars in Brazil this year.
The money will be used for AI, new services, offices, and growth in lending, among other things. The company already has 113 million customers in Brazil, and now it is also seeking a banking license. This probably refers to “full banking status” or broader rights that would allow for even more services, etc.
The investment will target four areas: development of artificial intelligence-based platforms and credit models, launch of new financial products and services, expansion of teams and office networks with over BRL 2.5 billion allocated to infrastructure over five years, and strengthening of the financial base to support portfolio growth.
The text is in Portuguese, but from what I understood, Nu Holdings is apparently moving from the Caymans to Abu Dhabi. Perhaps the goal is new emerging financial markets in Asia and Africa?
Here is a quote from an AI translator:
"The move to Abu Dhabi Global Market is not just geographical expansion. Nubank’s parent company, Nu Holdings, is registered in the Cayman Islands — a jurisdiction commonly regarded as a tax haven. Moving to Abu Dhabi follows the logic of tax planning: the Emirates’ tax benefits combined with ADGM’s regulatory prestige offer a more politically acceptable platform without giving up core advantages.
ADGM is an internal offshore financial center within Abu Dhabi with its own jurisdiction based on English common law, independent regulation, and zero corporate profit tax. For Nubank, this means maintaining an offshore holding structure but with a more credible address — and direct access to capital flows in the growing markets of the Gulf, Central Asia, and Africa."
Additionally, the article mentions an exodus of technology executives from the company:
"Behind the international expansion is an internal reality that Nubank is trying to keep hidden. The departure of the CTO in July 2025 — due to disagreements over David Vélez’s obsession with AI — triggered an exodus of top technical talent.
The mandatory return to the office in November 2025 hit engineers living outside São Paulo particularly hard. In one month, three out of six technology directors resigned. The communications director also left. For a technology company, this is not an HR issue but an operational risk."
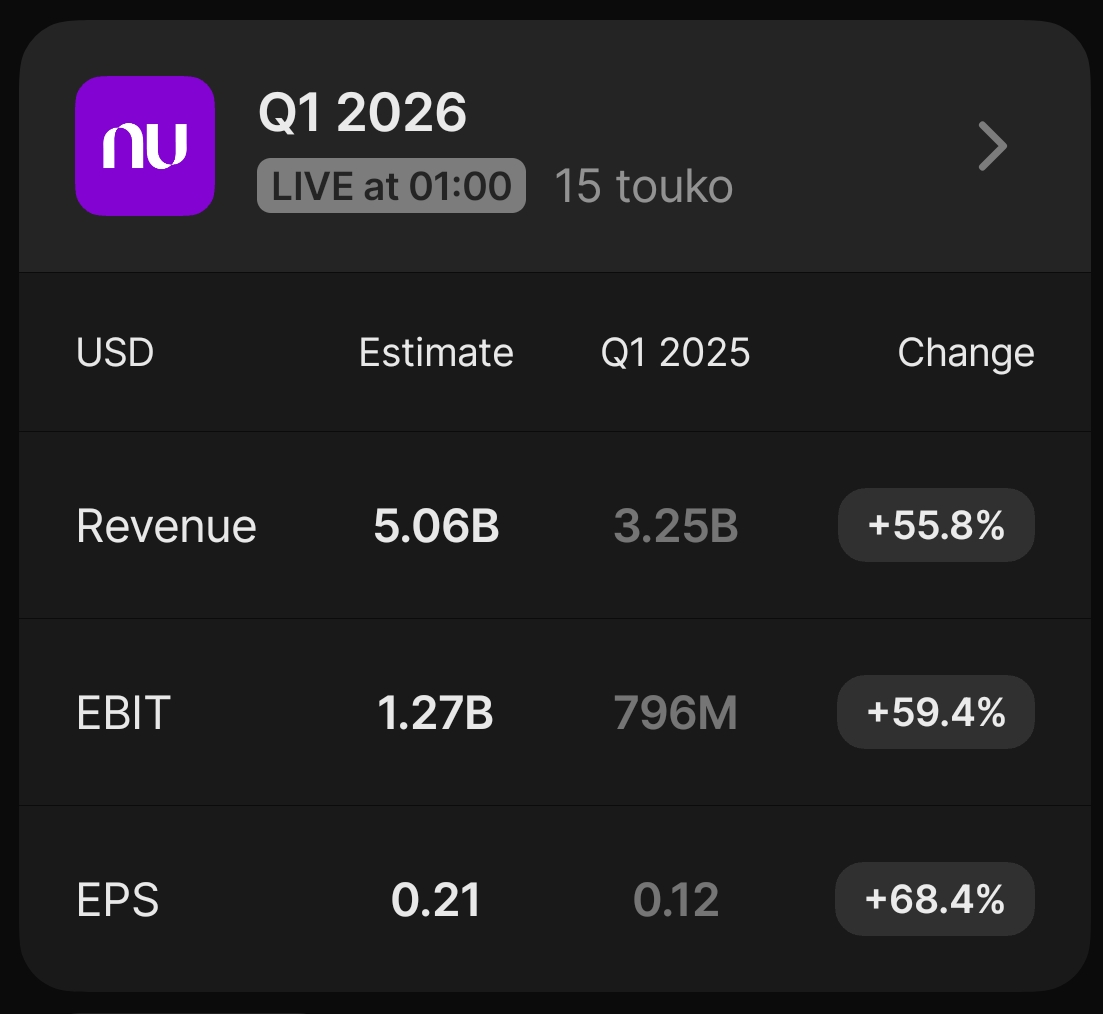
Earnings report coming out today after the market closes.
Once again, analysts have quite wild expectations for Nu Holdings’ earnings. As has been typical for these emerging market giants, revenue has quite often beaten expectations while profitability has been a miss. We’ll see what’s in store now.
The stock is currently at approx. 22x P/E, but if expectations are met, the forward P/E would be around 15x. The company is expected to grow strongly in the coming years at least until 2030.
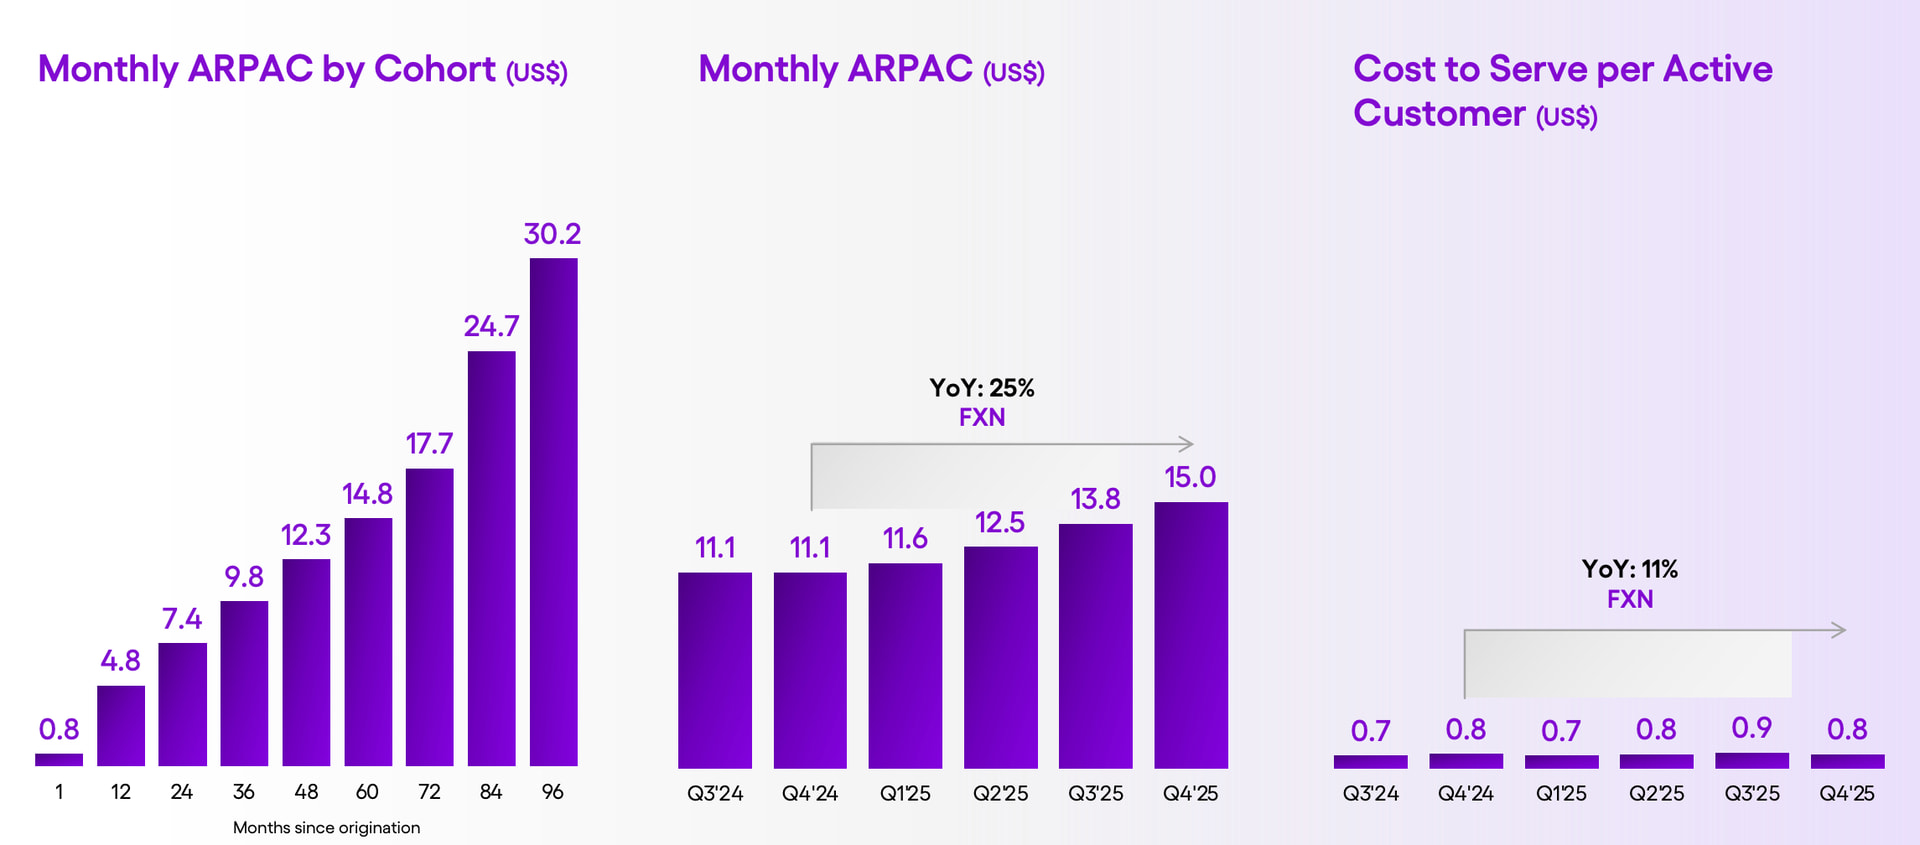
Hopefully, explosive growth continues across all markets, ARPAC (Average Revenue Per Active Customer) continues its ascent, and cost to serve stays around 0.8-0.9 (or preferably drops even further..)
It would be interesting to see misses on both lines just to see how this sour sentiment would treat it.




 Summary: why this matters