BBS reportedly grew organically by +15%, which is also good. This was for H1.
They are supposedly going to comment more on the BBS side in connection with the financial statements.
BBS reportedly grew organically by +15%, which is also good. This was for H1.
They are supposedly going to comment more on the BBS side in connection with the financial statements.
The management commented that the several openings falling within the quarter always have some impact on the earnings level. Otherwise, BBS’s development was said to have been in line with plans.
CEO Suominen was also interviewed on Kauppalehti’s Talousaamu:
Here is Jarno from NoHo’s interview from the Helsinki office. Includes one tennis easter egg 
00:00 How it went
00:44 Organic growth
02:00 Finnish economy
03:10 Norway
04:22 Synergies from acquisitions
05:20 M&A
06:50 BBS
08:06 Outlook
Based on the interviews, the webcast, and Suominen’s expressions, BBS’s expansion into a new country was perhaps closer in the spring than it is now. It seems the negotiations have hit a setback.
I think the reason is that expanding into a new country might be too big a risk due to the product and regional taste preferences. Or perhaps the situation is too comparable to starting a new chain from scratch.
I’m no expert on Norway or Denmark, but I could imagine that F&B wouldn’t necessarily work there. Germany/Austria, on the other hand, might be somewhat more similar to Switzerland, but there could still be differences.
We went to Switzerland for our summer vacation, and my only “must-see” attraction was Holy Cow  The burgers were alright, but for a Finnish palate, F&B beats them hands down – we had just visited Friends a week or two earlier, so it was a good benchmark. The price level in Switzerland did make me laugh; I recall a meal costing around €28, though at least it included a beer. You can get a meal at Friends for about €15–17.
Fresh report on NoHo from Sauli and Arttu:
Good analysis once again, but I still consider the forecasts for Q3 and the rest of the year cautious, given that there are several growth drivers, especially in Finland:
I personally see that there could even be room for a positive profit warning during the autumn; while the current guidance is for comparable EPS growth, we might end up with significant comparable EPS growth after all. Profitability should also remain at least at last year’s good level, if not approach 10% driven by the second half of the year. I don’t know, of course, what the thresholds are for when they deem it necessary to adjust the guidance.
Admittedly, though, it is often the case that when all the pistons in NoHo’s profit engine are firing, one of them soon starts to misfire for a while  That seems to be more of a rule than an exception in this industry.
Nordea adjusts its fair value range in its latest report from €9.0-11.6 → €10.1-12.8
NoHo Partners delivered a robust Q2 performance as the Norwegian operations normalised and the Finnish business rebounded, while Denmark continued its strong, broad-based growth. We believe the company has moved past its operational challenges and expect robust profitability levels going forward, supporting the 2026 guidance for the EBIT margin to remain at its current good level. With the Finnish market recovery showing positive signals, and new openings and M&A offering upside potential, we view the near-term outlook as back on solid ground. With our slightly higher estimates, we derive a higher fair value range of EUR 10.1-12.8 (9.0-11.6) by equally weighing our DCF- and SOTP-based valuation methods
Nordea is even more cautious than Sauli regarding Q3, so perhaps my own imaginings, which I painted in the previous message, were too rosy.
OP raises its target price ->€9.4 and reiterates Buy recommendation.
NoHo’s Q2 went excellently in several areas, and the success of the turnaround operations in Norway, in particular, as well as the return of revenue to growth, are extremely welcome developments. Despite some positive signs, the outlook regarding the timing of the strengthening of demand remains hazy. We believe that the conditions for growth exist for the coming years even in the current circumstances, which, together with the potential offered by the recovery of demand, maintains our positive view of the stock. Our target price rises to 9.40 euros (prev. 9.20), at which we reiterate our BUY recommendation.
The full report can be found here:
DNB Carnegie has adjusted its target price accordingly. Unfortunately, there is no access to the report:

@henrielo has produced an analysis of NoHo, which takes just a few minutes to read 
Both Suominen and CFO Jarno Vilponen stated on several occasions that they are particularly pleased with the turnaround in entertainment restaurants. In that segment, revenue grew by 7.2 percent to 21.6 million euros in April–June. Certainly, spring terrace weather that was better than last year helped with the turnaround.
The company completed renovations in late 2025 at nightclub restaurants in Helsinki, Tampere, and Seinäjoki, and the beginning of the second quarter for this business area was already strong, as we wrote in previous analyses.
Note.
IR Tracking is a channel for SalkunRakentaja and Sijoittaja.fi’s corporate partners to provide background and analytical articles as well as other interesting investor information. The article is part of a commercial partnership with the company. The article does not contain investment recommendations.
Eppu Normaali’s concert sales went well for NoHo:
Sales records were broken at Eppu Normaali’s concerts
NoHo Partners was responsible for the food and beverage service at Eppu Normaali’s farewell concerts.
The company would not comment on the volume of alcohol sold at the concerts, but the company’s CEO, Jarno Suominen, suspects that some kind of records were broken.
– I haven’t heard of an event held at Ratina ever having sold as much food and drink as was done this time.
According to Suominen, the sales volumes were in line with expectations, perhaps even exceeding them.
– The demographic was mature and had enough purchasing power that business went very well from our perspective. The event also had a positive impact on our other restaurants.
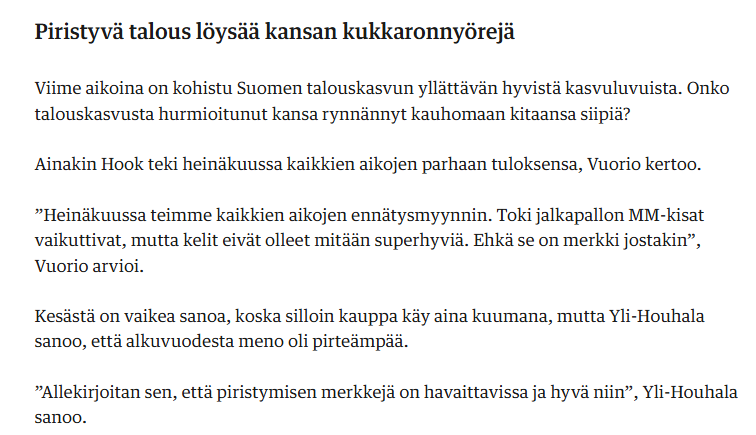
An article in Kauppalehti about the positive development of wing restaurants, primarily focusing on Siipiweikot and Hook (NoHo):
July seems to have gone great for Hook:
Jarno Suominen was interviewed in Talouselämä, albeit behind a paywall: Ison ravintolaketjun pomo: Suomalaisten käytöksessä tapahtui merkittävä muutos | Talouselämä
I will quote freely here and there from the interview; they are certainly the same topics that have come up before in management interviews.
I don’t know exactly what the headline refers to, but perhaps it is the “Europeanization” of restaurant culture that has come up in the interview and in many other contexts before—the idea that the younger generation is accustomed to using services more and it is more of an everyday thing; you don’t need a celebration or any other special reason.
The restaurant industry is highly cyclical, meaning NoHo’s customers react specifically to the real economy, not so much to economic forecasts. Consumers didn’t react when interest rates started to rise, but rather precisely when the adjustment date for their own loan interest rates arrived.
Classic restaurants like Elite and Sea Horse, as well as top-tier restaurants Palace and Savoy, perform well in any economic climate; the latter two even set sales records in 2025. Concepts must resonate with the customer.
Entertainment restaurants are seeing revenue growth for the first time in a long while, which was influenced by, among other things, the good weather in early summer. There are over 15,000 customer seats on terraces. People go to nightclubs a bit less frequently, but when they do, they spend a bit more on their night out.
When asked what would be a clear sign of an economic upturn in the restaurant business, Suominen replies: “It relates to business-to-business trade. When the organizer of a corporate event focuses more on the quality and what happens at the event than on what it costs. That is when we are heading in a positive direction in the economy.” And how far are we from such a situation? “Hard to interpret. A small positive vibe.”
On the growth of chains: Jungle Juice Bar is constantly active, new locations are being looked at for the Hanko Sushi (Hanko Asia) chain, the chicken wing restaurant chain Hook is an expanding chain, as is Stefan’s Steakhouse. The associate company Friend & Brgrs is also growing.
The turnaround in Norway was achieved when “support was given from Finland for restructuring measures, because the organization in Norway wasn’t really used to a situation where there is declining revenue.”
Suominen himself attended all three days of the Eppu Normaali farewell concerts at Ratina; on Saturday, he watched the entire concert. Such mega-events are quite rare even for NoHo, but they succeeded excellently, and we can definitely be satisfied with the whole experience.
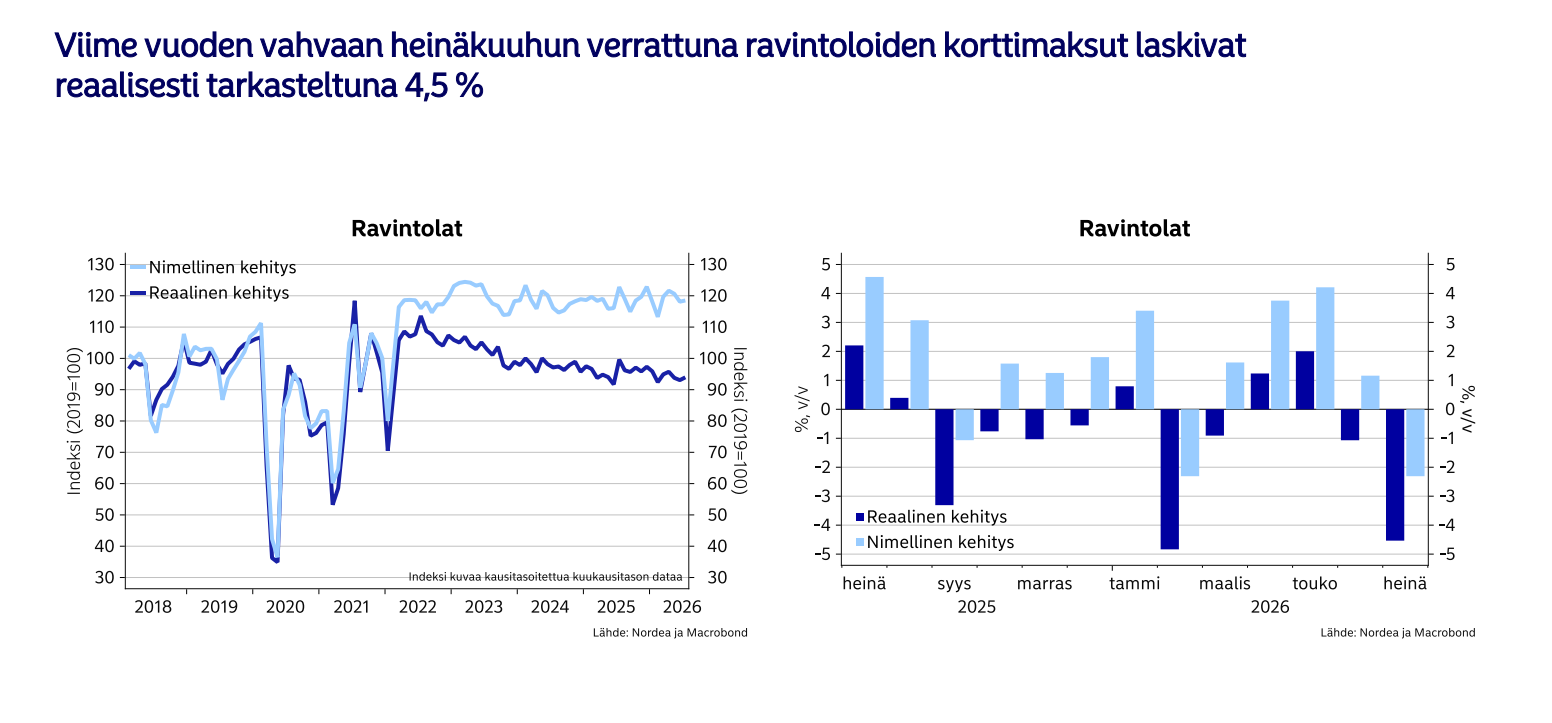
July was not great for restaurants in terms of Nordea card payments. The comparison period was a fairly strong, hot July:
However, Suominen did state that July went quite well for NoHo and according to plan.
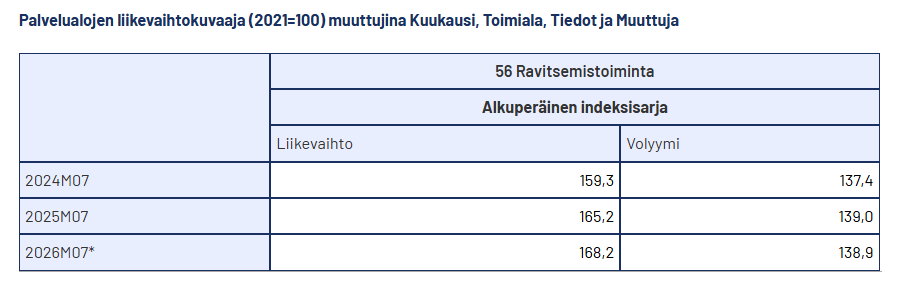
Statistics Finland’s food and beverage service activities turnover grew slightly from last July, but in terms of volume, it remained practically at the same level:
NoHo swaps bank financing for bonds:
I suppose this has been calculated to be a more cost-effective solution for the shareholders.
And there are Sauli’s comments already:
Thanks for those!
As I mentioned in my comment, I have mixed feelings about this. It’s really good that the maturity extends and the flexibility increases. It has been easy to read from management’s comments that the company is not satisfied with its previous package and the flexibility it provided. However, the fact that once again an important driver behind EPS improvement fails to materialize is, of course, negative. After all, EPS growth is the thing that drives the stock price, and without EPS improvement, the stock has no prerequisites to enter a sustainable upward trend. 
Hi Sauli, could you explain why, because of this, the EPS improvement won’t materialize if the cost of capital (rahan hinta) is the same?
Surely financial expenses aren’t the only EPS driver, especially since earnings (tulos) also improved nicely.
Sauli said that one important driver for the EPS improvement won’t materialize, not that the EPS improvement won’t happen at all.
Previously, Arttu and I had assumed that the cost of capital would decrease as the net debt/EBITDA ratio decreases. The company also commented publicly in this direction. Now, at least our interpretation is that the cost of capital will no longer decrease, because the corporate bond (JVK) is very likely more expensive money than a bank loan. The cost of this new bank financing is certainly lower than that of the old bank loan, but the bond brings the total up to roughly the current level. I would like to remind you that NoHo has a lot of large items below operating profit (minority interests, interest, taxes), and due to these, out of 37 MEUR of operating profit, only ~13 MEUR is left on the bottom line. Net debt is around ~120 MEUR, so if the cost of capital had dropped by, say, 0.5%, the impact on EPS would have immediately been +5%.
However, as @Critter1 said, this decrease in the cost of capital is only one component behind the EPS improvement. The most important component is, of course, the growth of operating profit, which relies especially on revenue growth.