Sunny summer to the forum! 
NoHo Partners’ half-year report will be published on Tuesday, August 4. The webcast will be held as usual on the same day at 10 a.m. here.
Read more in the press release.
Feel free to send in your questions! 
Sunny summer to the forum!
NoHo Partners’ half-year report will be published on Tuesday, August 4. The webcast will be held as usual on the same day at 10 a.m. here.
Read more in the press release.
Feel free to send in your questions!
It’s interesting that NoHo seems to be a clear “buy” according to analysts, as evidenced by Nordea’s target price estimate of €9–€11.60 today. Yet, the stock still seems to be dragging around the €7.50 level.
It doesn’t really matter much what the analysts are shouting about. After all, analysts have been hyping up, for example, Qt Group, and things have been different. According to one study, analysts are right 30% of the time, so it’s pointless to rely on someone else’s analysis.
In the long term, the development of cash flow drives the share price. In the short term, stock prices seem to fluctuate quite randomly.
It feels like NoHo has gone up on one side and down on the other. Target prices could be reached when all the gears are working at a “normal” level and the results show through to the EPS. Of course, there is the risk that the nightlife market, for example, will not return to its previous level. Then there are those clubs, which are a nuisance.
It will be interesting to see the figures from Norway. The whole country has gone crazy over football, and that will surely have some impact on the utilization rates of services and restaurants.
Additionally, I’m waiting for something concrete regarding the situation with BBS. When is the next acquisition coming? I would also be interested in knowing about acquisition targets in Finland. Are the asking prices so much higher than NoHo’s, or are the companies just in such poor shape that they aren’t interesting?
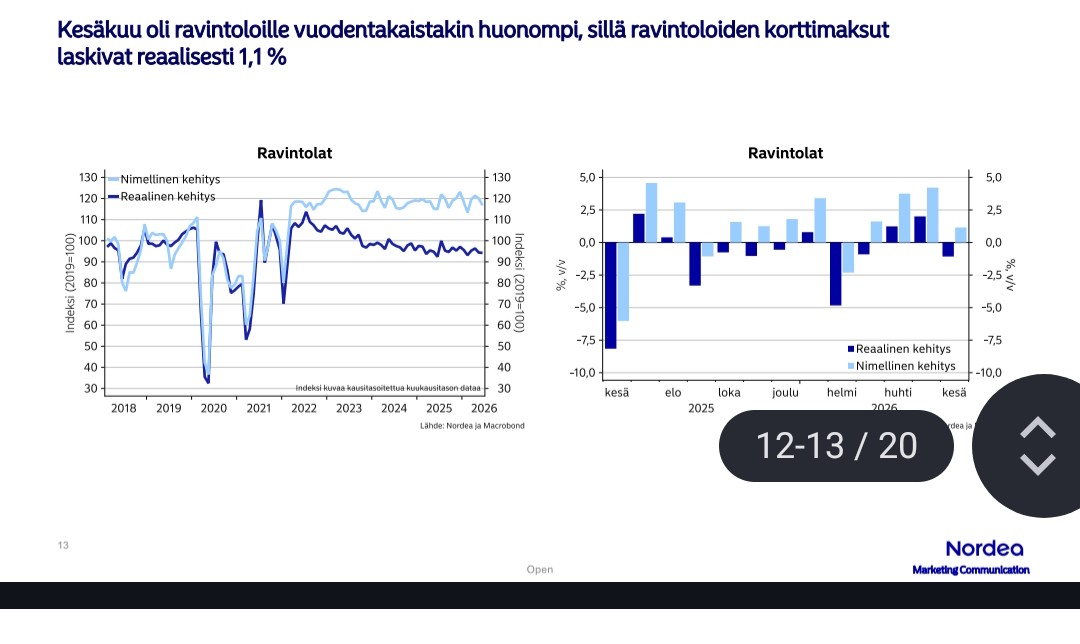
Weak June compared to my expectations according to Nordea’s card data for restaurants:
The comparison period is also weak.
These are also, preliminarily, the most interesting parts for me tomorrow. After the last CEO interview, I was relatively certain that a new acquisition would be completed on the BBS side during Q2, but we still haven’t heard anything about it.
Regarding NoHo itself, it’s also very interesting that it’s about to be 12 months since the last acquisition worth announcing (Jungle Juice Bar, Sep 2nd), and as far as I know, this is relatively exceptional for NoHo in a so-called normal market. 
Following the media, smaller restaurants continue to go under, and you have to read cries for help where people are shouting for support because trade hasn’t been as expected, even during the summer.
There is some good news coming from the economy and consumer confidence has started to recover slightly; we’ll see if this is the quarter where that already shows in NoHo’s figures, or if it will take until Q4, for example.
OP estimates in its earnings preview that the excitement surrounding the FIFA World Cup will support a turnaround in Norway. The “buy” recommendation and target price of 9.20 euros remain unchanged.
We expect revenue to have grown to 93.3 million euros (+6.5% y/y, consensus 92.7). Weather conditions in Q2 were more favorable than in the comparison period across all operating countries, which we expect to support top-line development.
Nordea also shares the following about card data from other countries in its own preview:
Market growth accelerated during Q2
Based on Nordea card data, the restaurant market in the Nordics accelerated in
Q2. In Finland, nominal growth was 4.0% y/y on average in April-May (Q1: 0.9%),
while real growth was 1.6% (Q1: -1.6%). In Denmark, nominal growth was 2.9% in
April-May (Q1: 1.0%) and real growth was 0.2% in April (Q1: -1.5%). In Norway,
nominal card spending was up by 5.1% y/y in April-May, on average (Q1: 5.2%).
We expect Denmark to continue to be solid and Finland to improve its
performance on the back of improved weather conditions y/y (which bodes well
for terrace sales), while the challenges in Norway are still likely to be present in
Q2. We pencil in a Q2 sales growth of 6.6% and an EBIT margin of 8.5% (stable y/
y), and our estimates are 1-2% above post-Q1 Vara Research consensus.
The reports can be found for everyone here:
Here are Arttu’s and Sale’s pre-game comments ahead of NoHo’s Q2 results announcement next Tuesday 
We expect the company’s revenue to have grown, supported by acquisitions and a slight recovery in the restaurant sector. We expect the operating result to have remained at the level of the comparison period, weighed down by profitability in Norway, which is still at a weak level. We believe the company will reiterate its guidance while highlighting an improvement in earnings performance for the remainder of the year. Consequently, our focus is particularly on the progress of the turnaround in Norway and the realization of synergies enabled by the acquisitions made.
And it would be great to get more info on this BBS pattern. Has the expansion to the third country progressed, and what are the plans after that?
Yes, in the Q1 announcement, it clearly seemed that the expansion would take place in the near future. So, there are certainly deals in the works, but for one reason or another, they haven’t been finalized yet.
BBS (BBS-Bioactive Bone Substitutes) still has plenty of acquisition capacity (or debt capacity), as their net debt/EBITDA is somewhere below 1x.
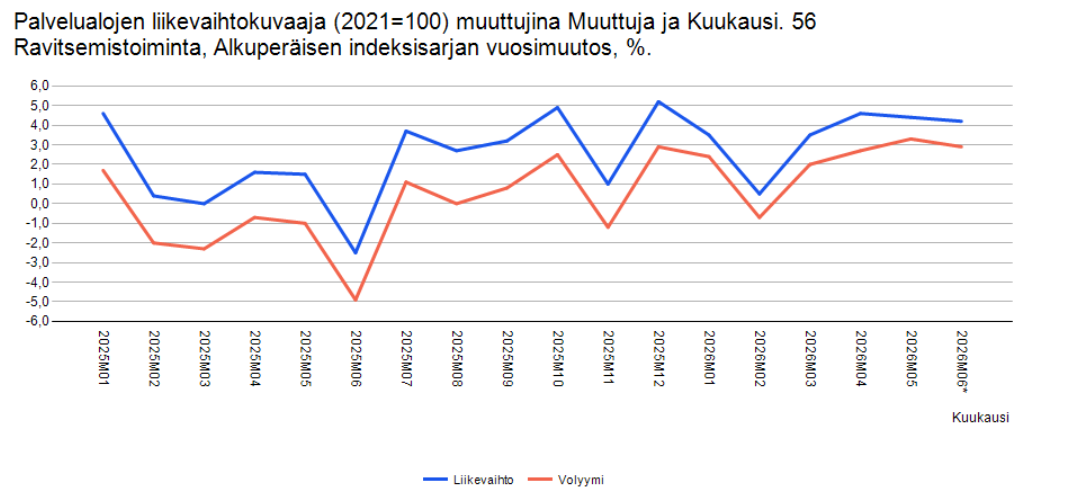
Catering industry revenue continued to grow in June:
4.2% in euros and 2.9% in terms of volume.
This Q1 has indeed been the strongest quarter in terms of growth since Q1 2023.
Well, that’s the most boring recent list of shareholders ever, since there wasn’t a single change in the top 50.
On the other hand, Verbier Invest 3 Oy, a.k.a. Max Laine, had increased their stake a little, but no stock exchange release has been issued regarding insider trades. Previously (in May), the entity in question did make a notification.

It looks like they have acquired more shares than were previously reported in stock exchange releases anyway. Perhaps they determined that they are not subject to the notification requirement or something similar.
Good morning! 
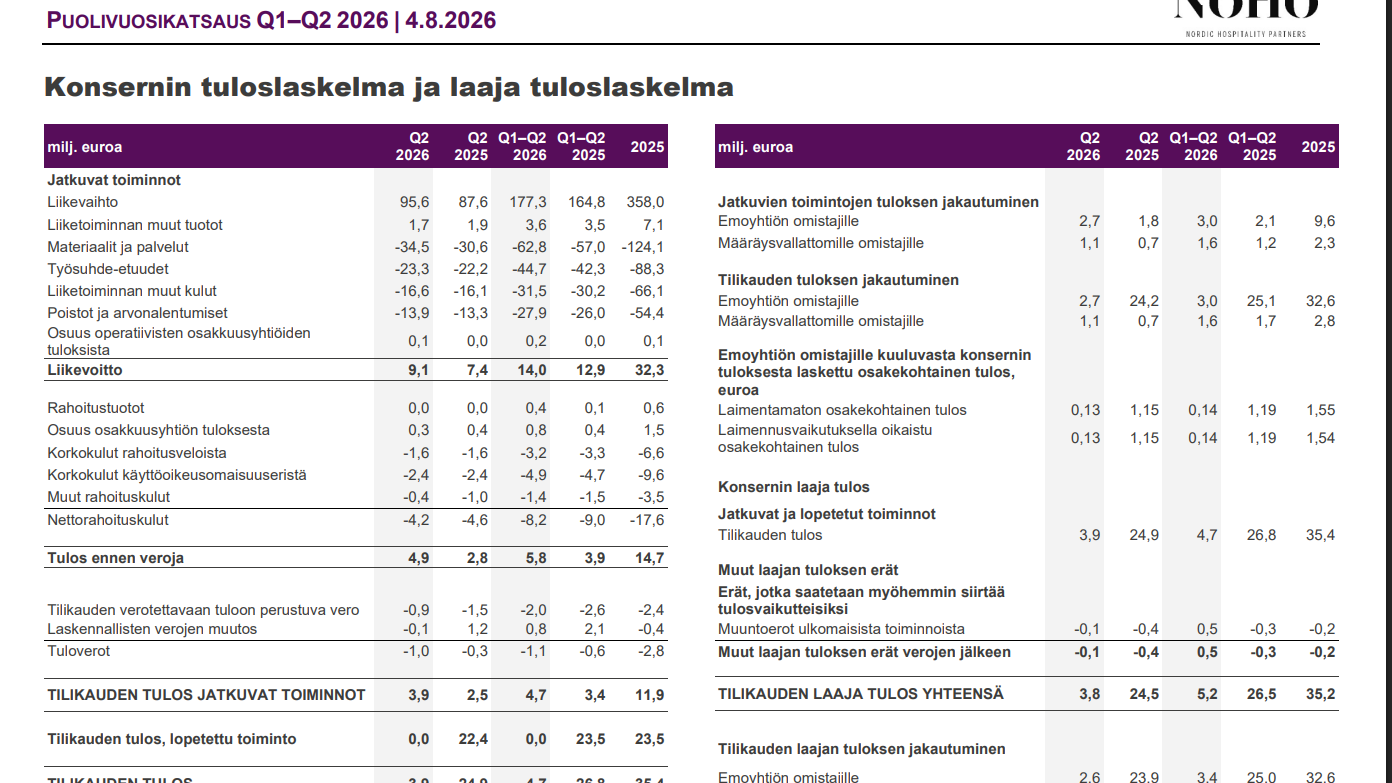
The half-year financial report for 2026 is out! We succeeded in all market areas, and revenue, profitability, and earnings per share were all on the rise. You can access the report here.
See you at the earnings webcast today at 10 a.m.!
**
Revenue was 95.6 (87.6) million euros, an increase of 9.2 percent.
Why is the result of discontinued operations at zero; is there some larger expansion underway (BBS)? Otherwise, it looked good, and it’s also good to continue from there in H2.
I assume it’s just a matter of NoHo no longer counting the result from its investment in BBS, as it’s unlikely that BBS’s own result is exactly zero!? Of course, the question arises as to how investors will get visibility into BBS’s development? Well, maybe someone wiser can shed some light on this!?
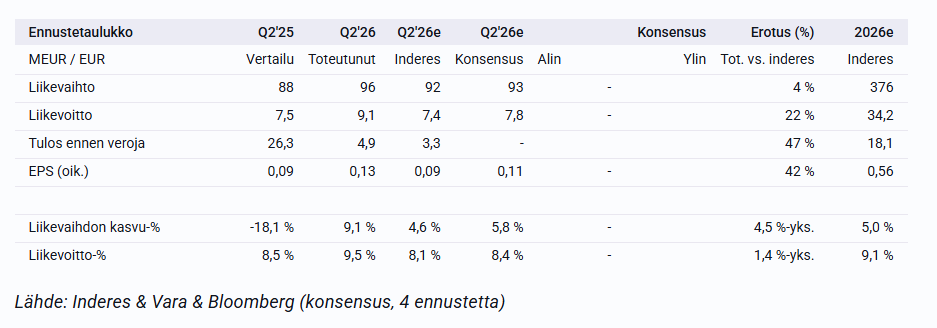
An excellent result, although I considered Inderes’ forecasts very conservative from the start. The operating profit margin is in the black, and most importantly, the result in Norway is positive (though it was already in Q1).
BBS’s earnings are reported on the income statement under “share of profit/loss of associates.” The result was soft this quarter compared to Q1 and last year, but I don’t know how those new initiatives are affecting it.
I’m sure that will be asked about in more detail during the webcast, and we’ll get to hear how things are progressing.
NoHo certainly put in a strong performance in Q2. The figures have already been gone over by the company and analysts, but I’ll pick out a few highlights:
The CEO’s comments on the outlook are also promising, and it’s worth noting that in Tampere, the “NoHo capital” of Finland, it’s shaping up to be an all-time great August in terms of events:
“The recovery of consumer purchasing power has remained cautious, although some positive signs were already visible in the market during the quarter. However, the development of our company’s business provides a good starting point for the rest of the year. The highlights of late summer include three sold-out farewell concerts by Eppu Normaali in Tampere, for which NoHo Partners is responsible for all restaurant services. The events are expected to bring tens of thousands of visitors to the city and thus provide additional momentum for the business in the third quarter of the year.”
Furthermore, in the webcast, Suominen stated that July went according to the company’s plans. According to management, Norway’s sales in June weren’t really impacted by the Women’s World Cup yet; that has been more visible in the July sales.
Although the figures are certainly strong, I think the best part of the report was that many uncertainties/concerns (Denmark, Norway, entertainment restaurants) have faded away.