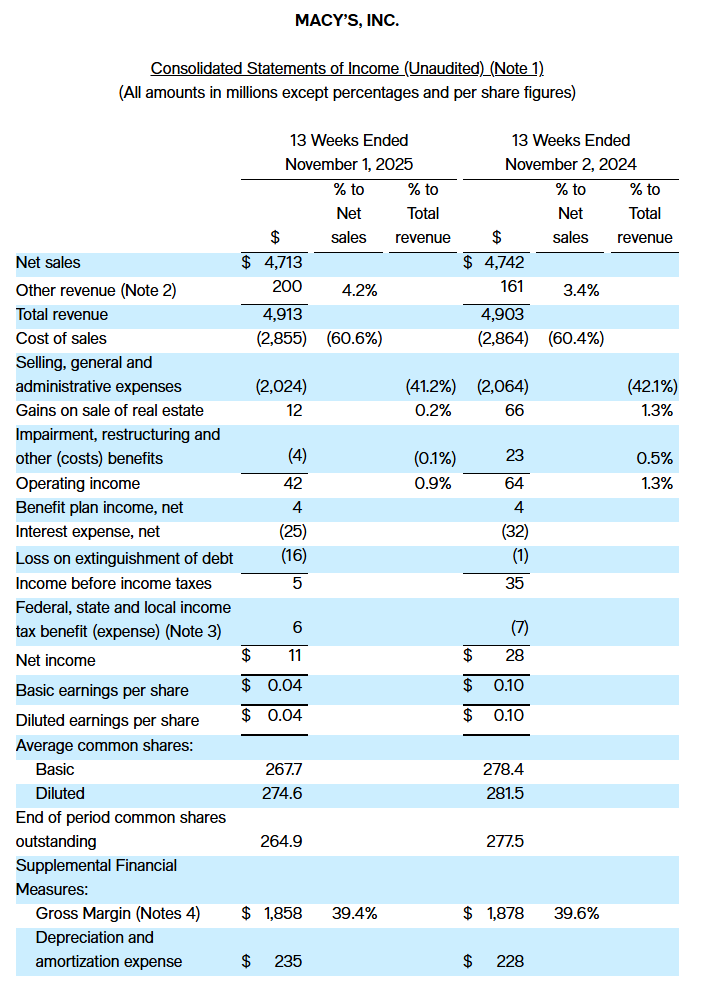
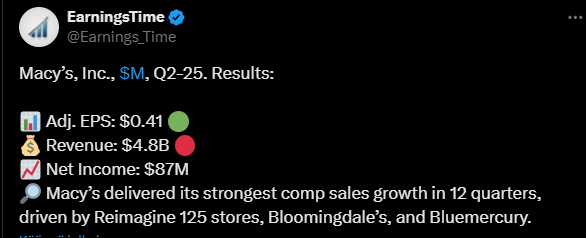Macy’s announced that a company employee had intentionally failed to report $132-152 million in shipping costs to customers from Q4 2021 - Q3 2024. This is estimated to have had a 20 basis point positive impact on the gross margin that Macy’s has reported. The next analyst call should be listened to carefully.
Over the year, Macy’s has piloted a new store concept focusing on customer service. Revenue for these “First 50” stores has grown, and customer satisfaction has reached an all-time high. The total number of stores will be reduced, and lessons learned from the pilot will be applied to the remaining “Go Forward” stores.
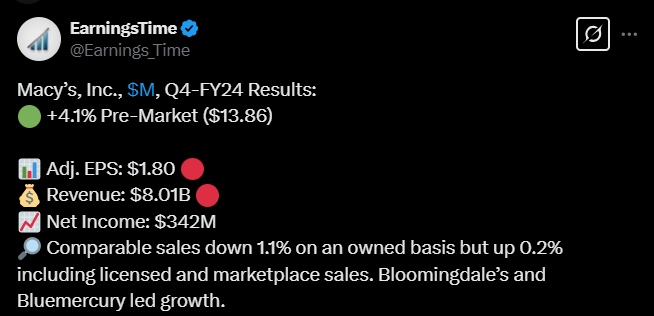
Macy’s business has strong operating leverage, meaning changes in revenue significantly impact results. This year, the profits on the income statement have come solely from asset sales, but it’s important to remember that Q4 is by far the most significant quarter for profitability. Within the group, Bloomingdale’s and Bluemercury have performed well. Revenue for both chains has grown. Macy’s chain revenue, on the other hand, has decreased as a result of store sales.
Regarding accounting errors: an employee acted alone, intentionally misrecording shipping costs for customer deliveries, and did not seek personal gain. The employee is no longer with the group. The erroneous entries made by them have not caused harm to suppliers, and cash flow statements reconcile.
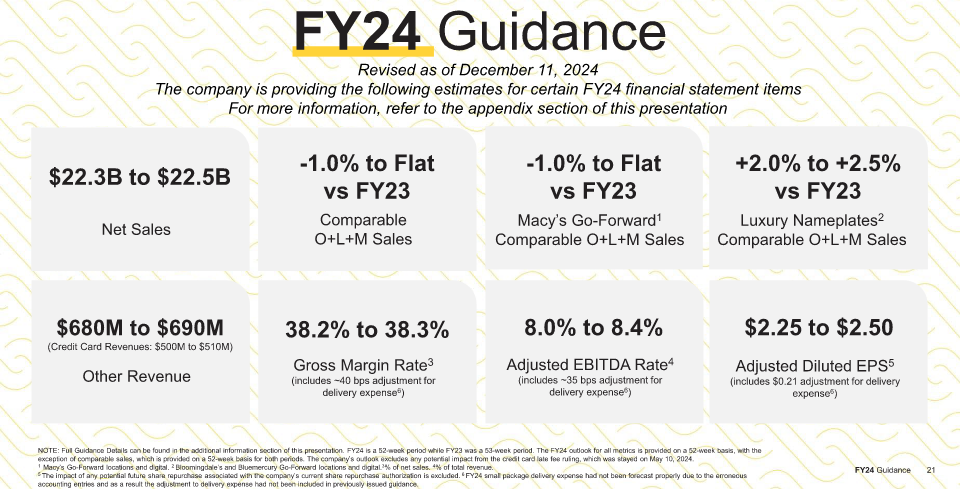
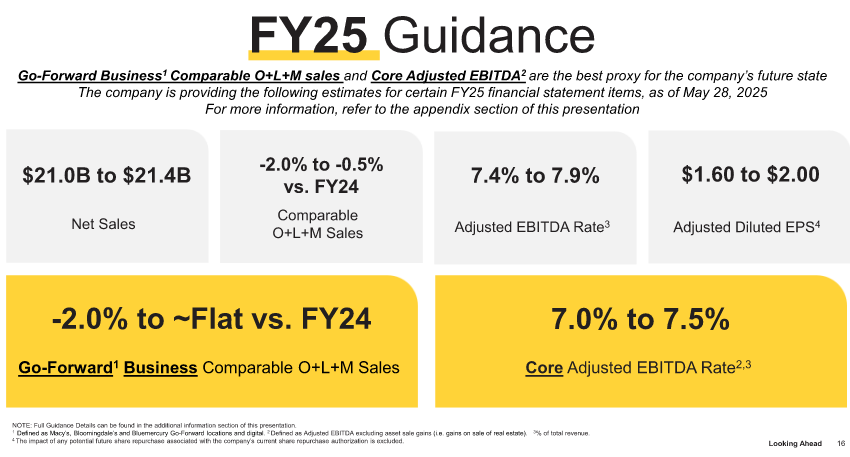
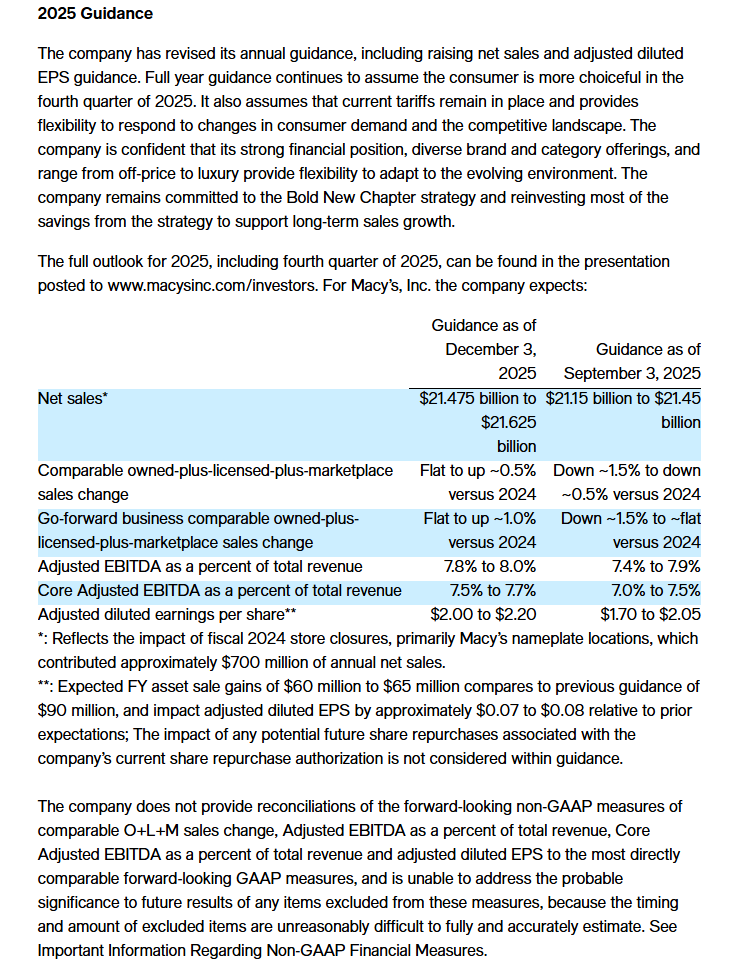
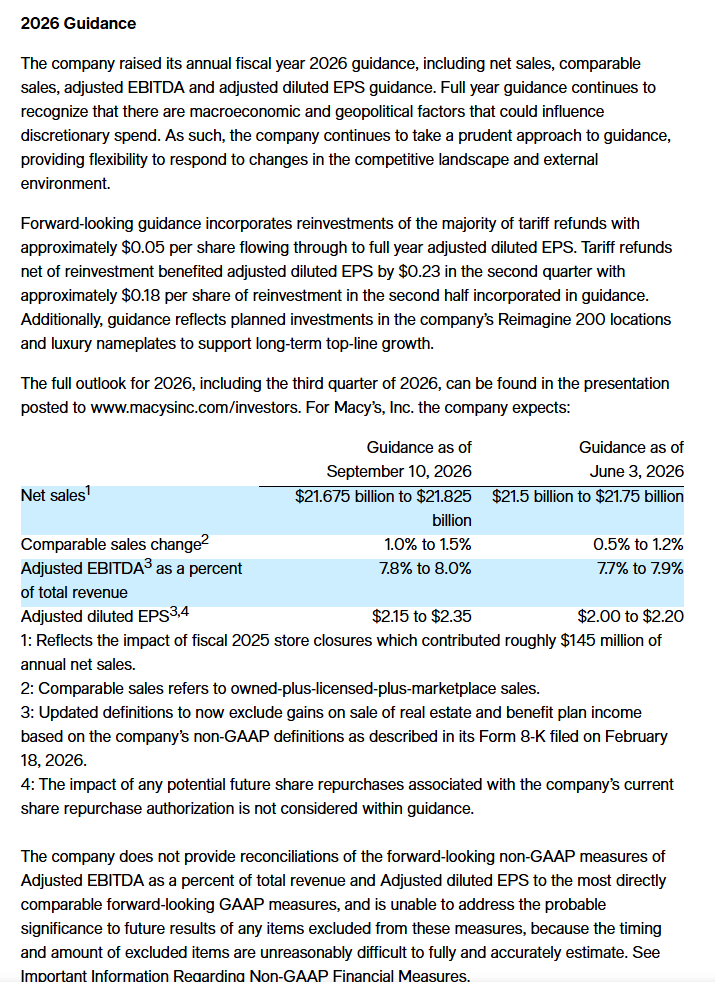
Guidance:
Comparable O+L+M refers to the development of comparable sales for owned + licensed + marketplace.
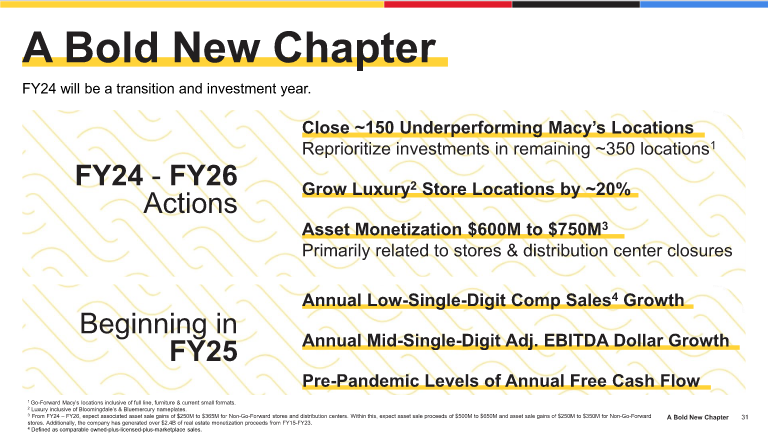
Bold New Chapter is the name of the new management’s transformation program. The program’s objectives are outlined on this slide:
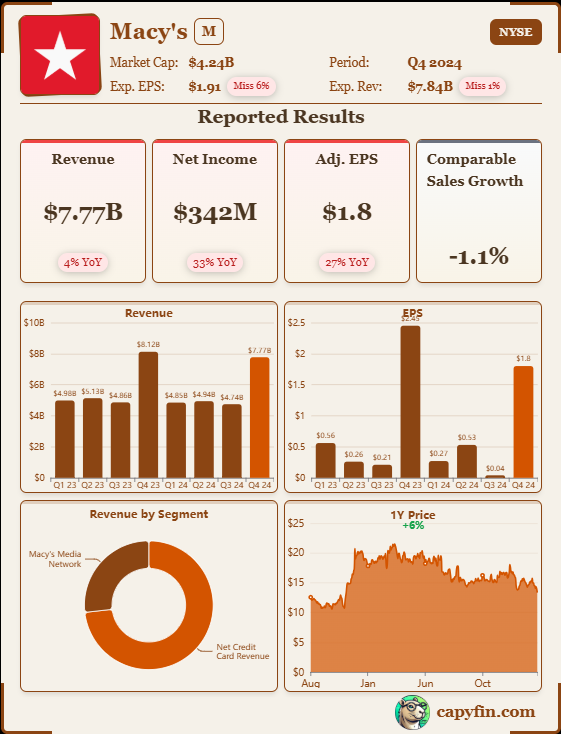
Macy’s has warned that Q4 sales have not picked up.
Macy’s sounds alarm on its holiday sales performance
Now that the holiday season has come to an end, Macy’s has provided a grim update on its fourth-quarter sales performance, which will be unveiled in early March.
The company warned that its comparable sales were roughly flat quarter-to-date as its “non-First 50 locations,” inclusive of “non-go-forward locations,” performed below expectations and generated negative comparable sales, according to a new press release.
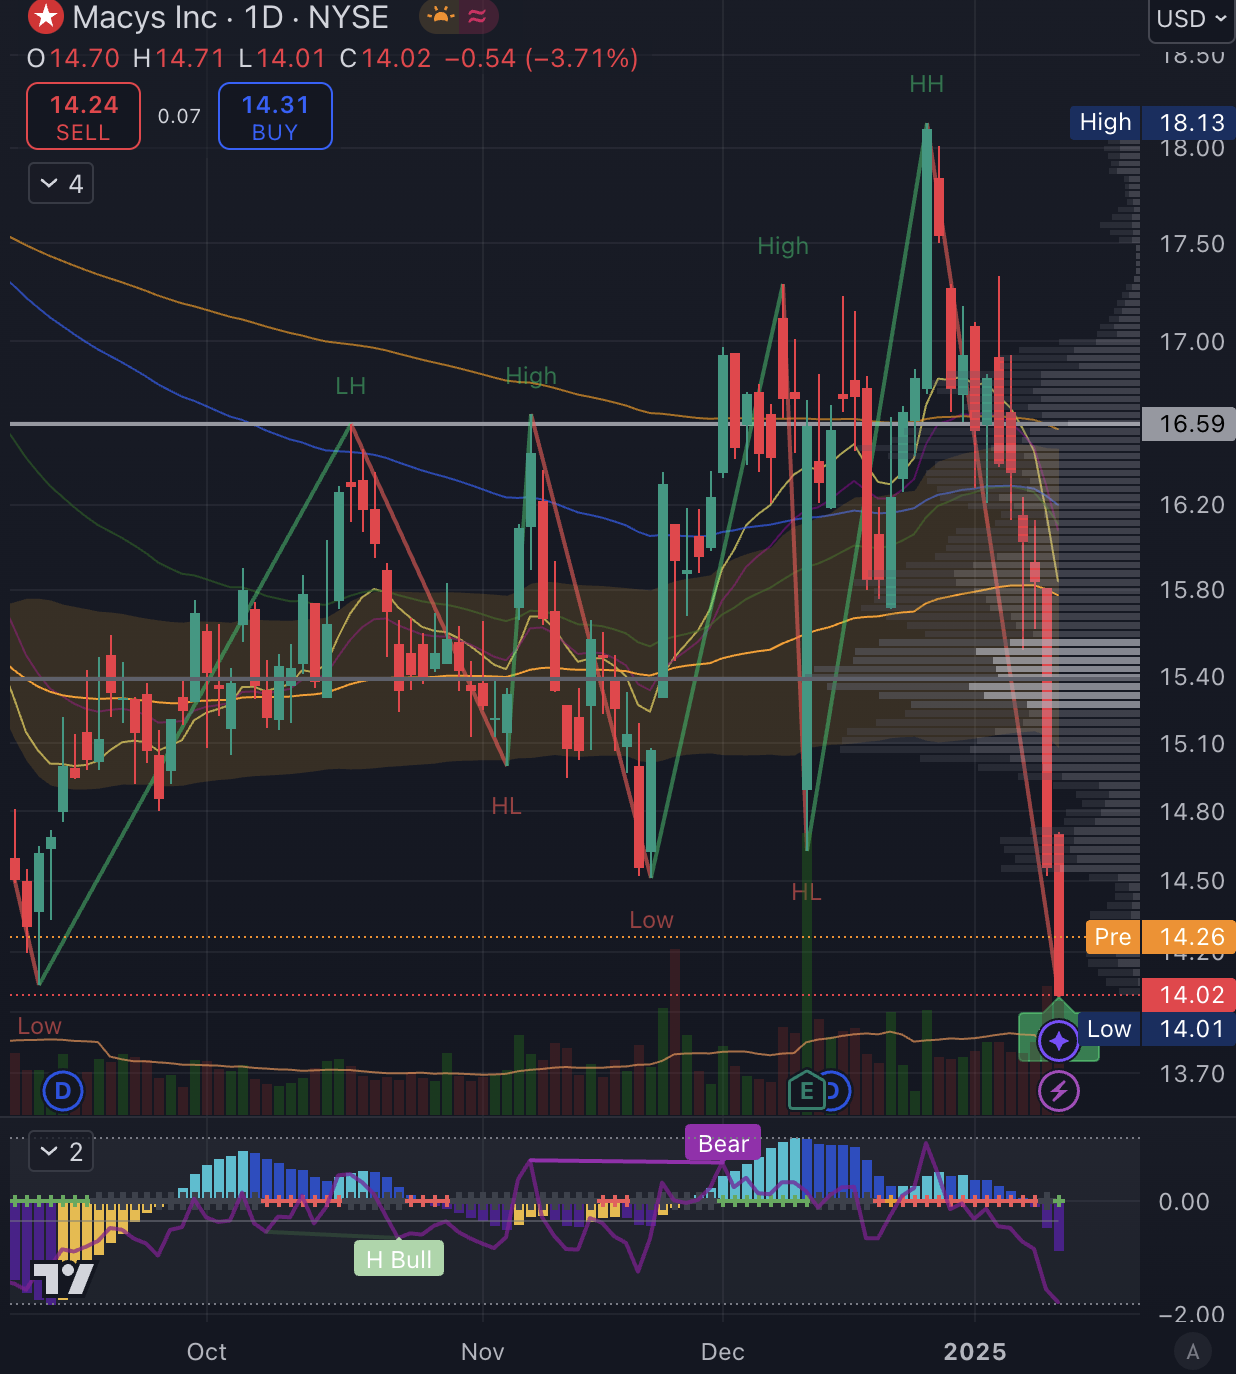
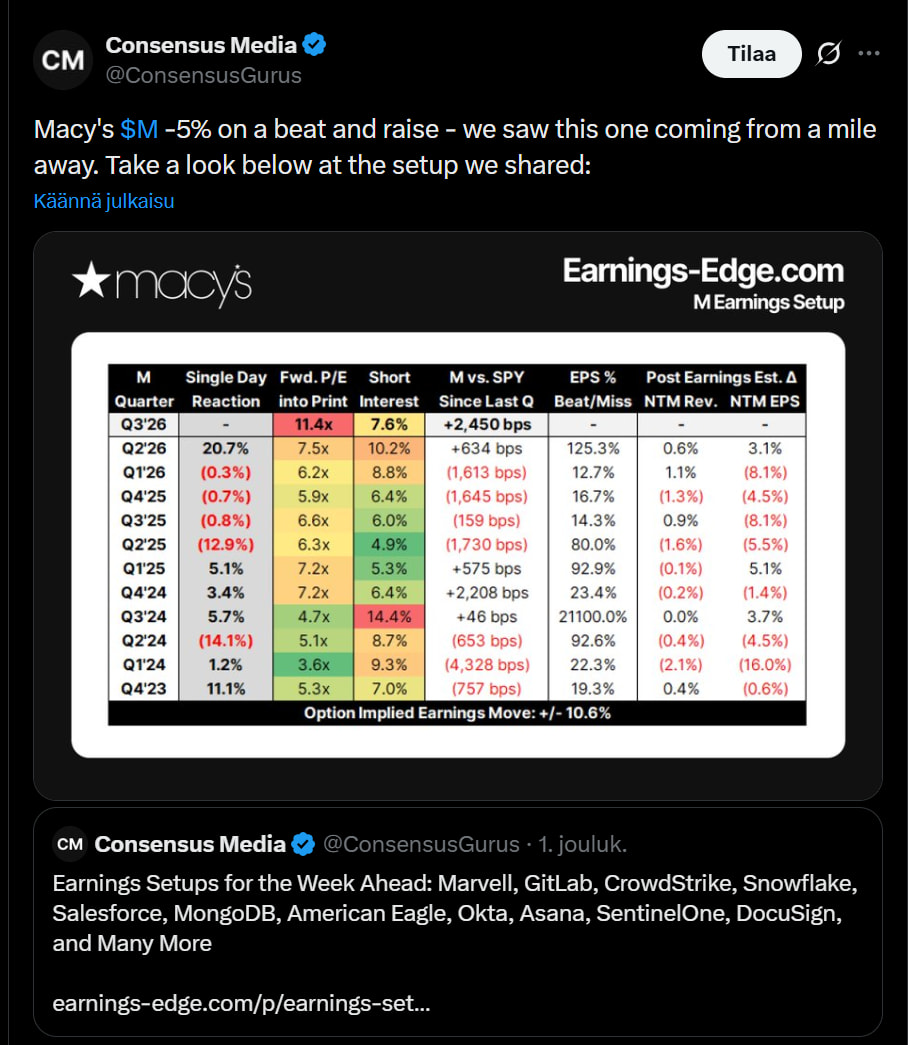
$0.86 earnings per share were made in the first three quarters, and now an additional $1.40 - $1.65 is expected, meaning we would reach the $2.26 - $2.51 range that was given in the Q3 results. P/E 5.5 - 6.1. It feels like the market is overreacting again.
Full-year earnings were 582 million ($2.10 per share) and free cash flow was 679 million. The current year’s earnings are expected to be somewhat similar to the previous year. A shift towards a smaller but relatively more profitable company is underway, and the sale of business premises that are more valuable as real estate than as business operations will continue in the current year.
Macy’s balance sheet reached a post-pandemic record high in terms of equity ratio (27.75%) and low net gearing ratio (32.36%). Return on equity was 13.65% and equity per share was $16.4. Net debt remaining at the end of Q4 was 1473 million.
Free cash flow yield:
679 million free cash flow.
1473 million net debt.
Share price: $13.41
Shares outstanding: 277,635,790 units
Market cap: 3723 million
Free cash flow yield: 679 / (1473 + 3723) = 13.07%.
Sorry for intruding here as well, as this company has come up often, but then the thread has been quiet, so I wanted to come here to continue the discussion.
Revenue did decrease slightly, but the digital channel (a growing driver?) and the growth of certain stores partially compensated for weaker performance elsewhere. Luxury brands performed well, and strategic investments in “customer experience” yielded results, which should continue to be visible in the future.
Management emphasized plans to expand successful experiments, and additionally, management naturally aims to accelerate profitable growth. The company continues to focus on efficiency, improving customer experience, and also on the sensible use of capital. And a strong cash flow enables rewarding shareholders through, among other things, dividends and share buybacks.
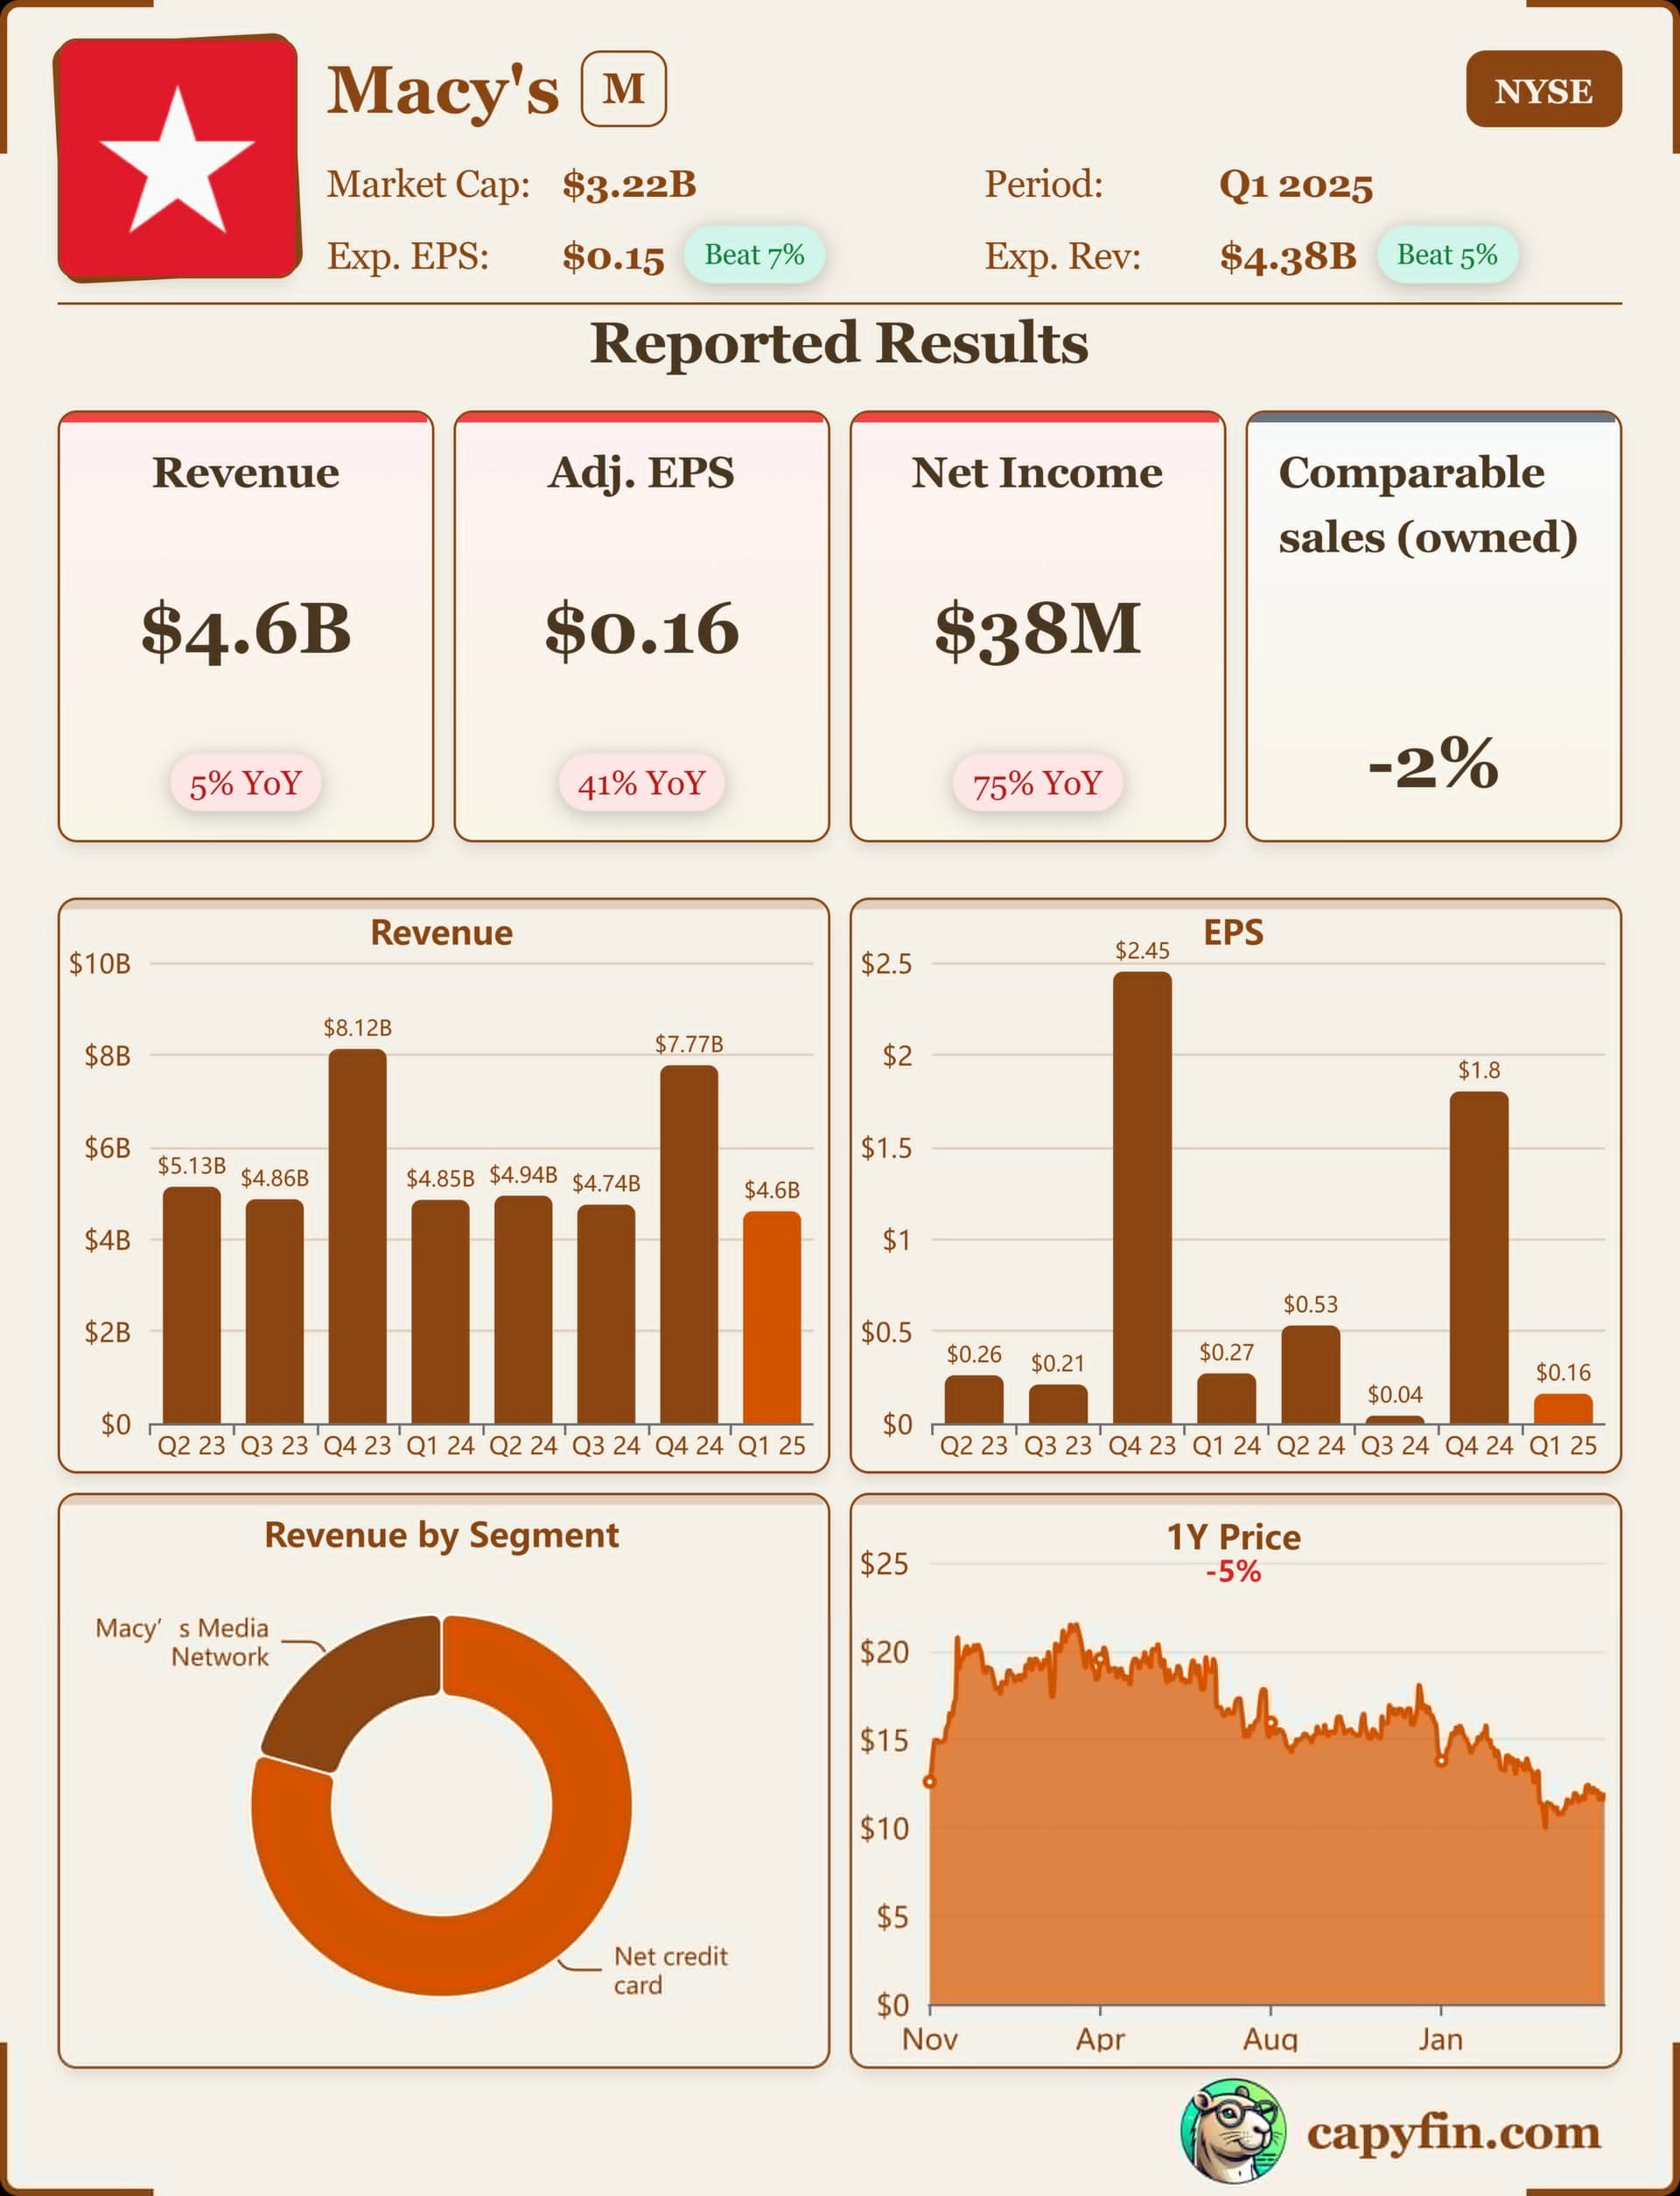
The company had a good first quarter, meeting expectations in terms of revenue and profitability.
The company has successfully improved its services and performed well in various areas. Bloomingdale’s and Bluemercury have grown well, although sales slightly decreased on Macy’s own channels, but the overall result was better than expected.
Management believes in the effectiveness of its strategy and sees good prerequisites for continued profitable growth. Not much AI hype was encountered.
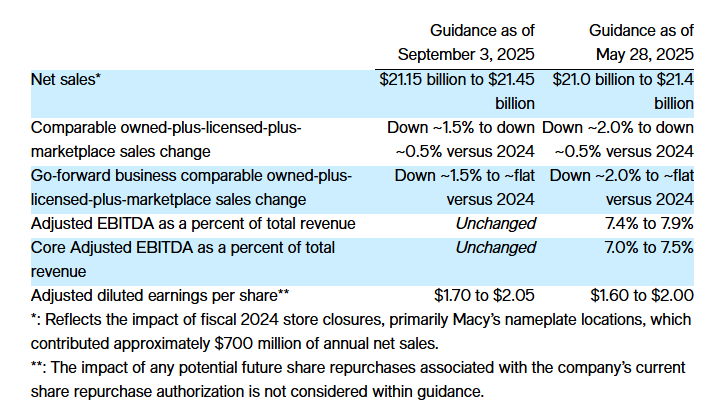
Thanks @Sijoittaja-alokas for sharing these numbers. The company lowered its guidance due to tariffs and expectations that consumers will become more selective towards the end of the year:
Own shares were bought back for 101 million. Currently, the equity per share is greater than the company’s share price, so as a result of the share buyback, the equity per share will increase. The return on equity for the previous 12 months was 12.92%.
The company also held an analyst call, where the CEO and CFO answered tough questions. CFO Adrian Mitchell, who has done a good job during the pandemic, is leaving the company. I was disappointed by this. The company’s management repeatedly emphasizes the strength of the company’s business model, which is flexible in terms of a strong balance sheet, supplier selection, and import channels. Today, only 20% of the company’s goods come from China. The share of domestic deliveries has grown to 18%.
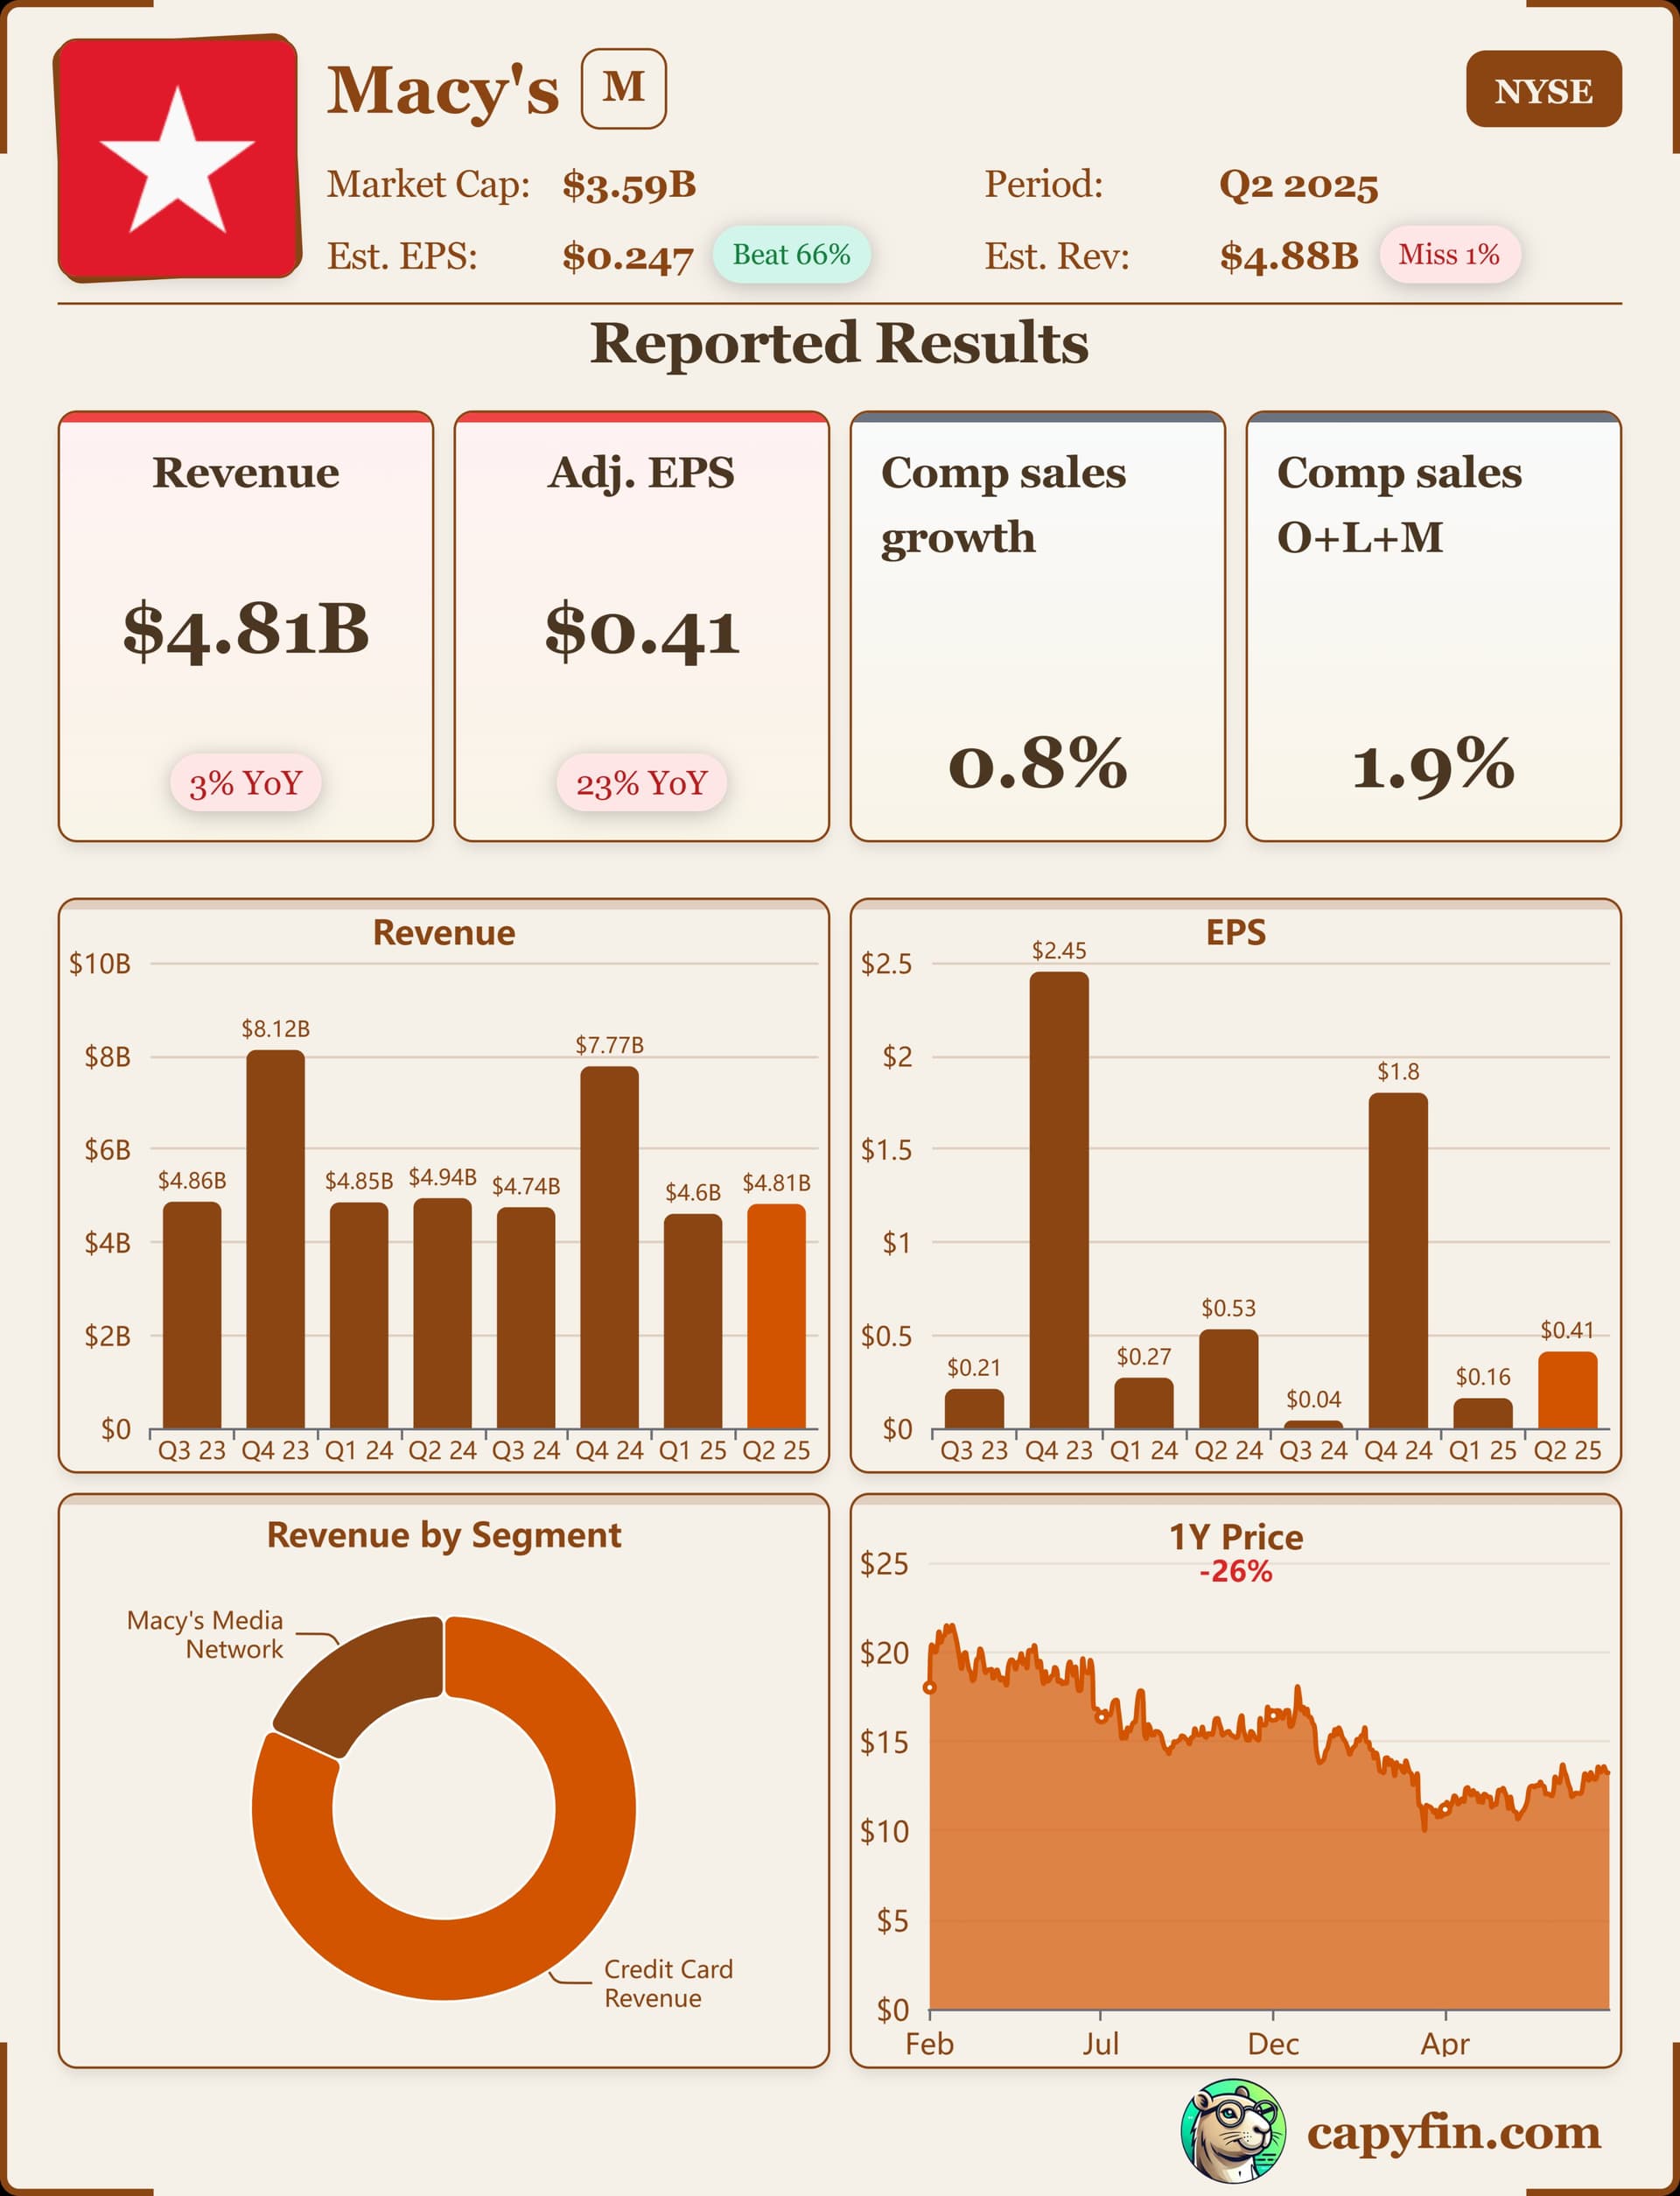
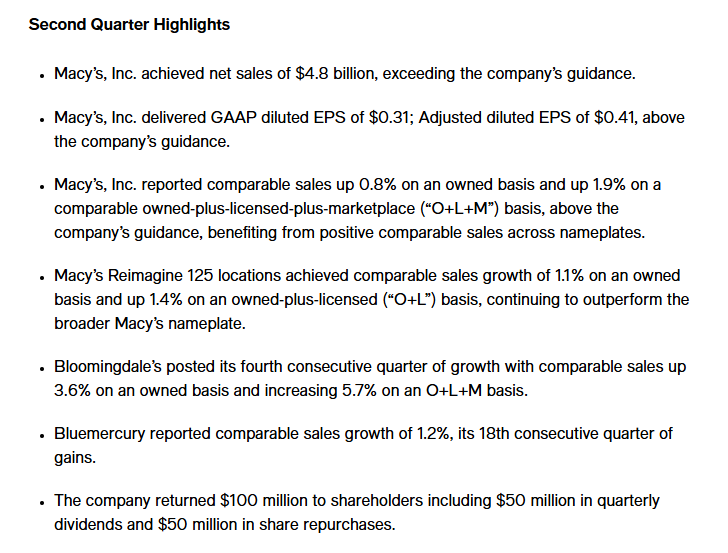
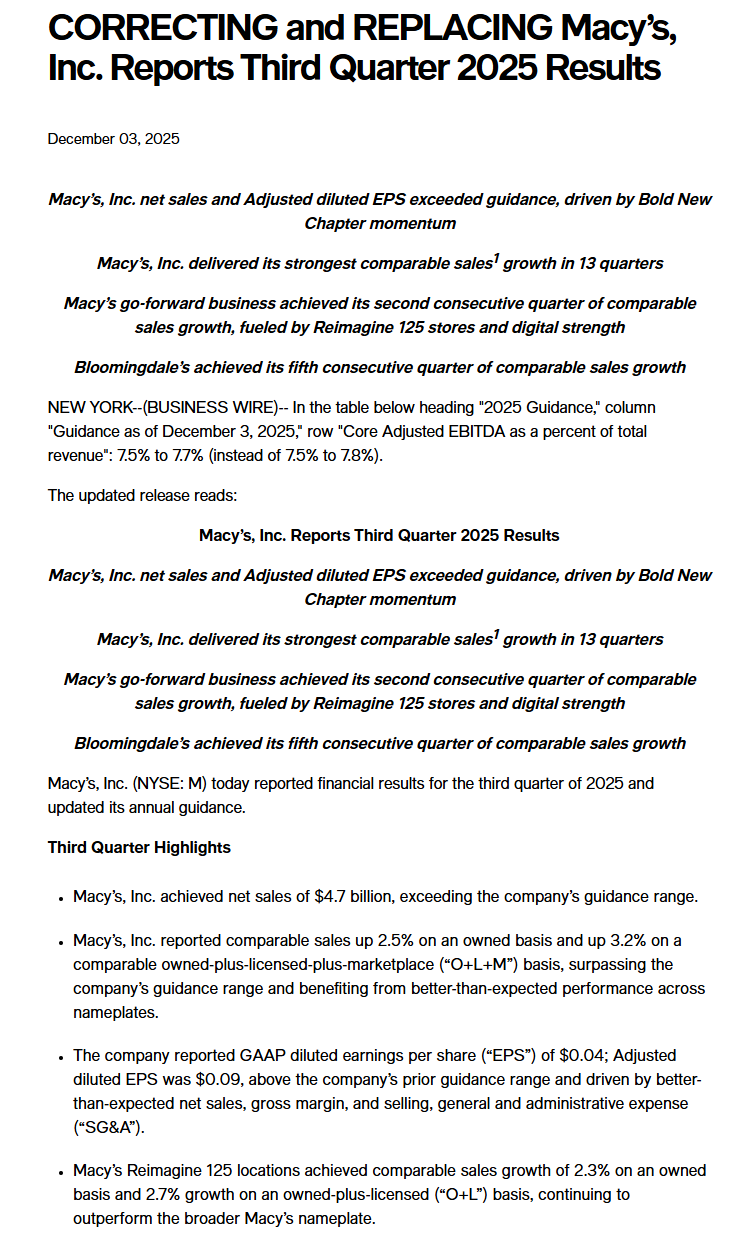
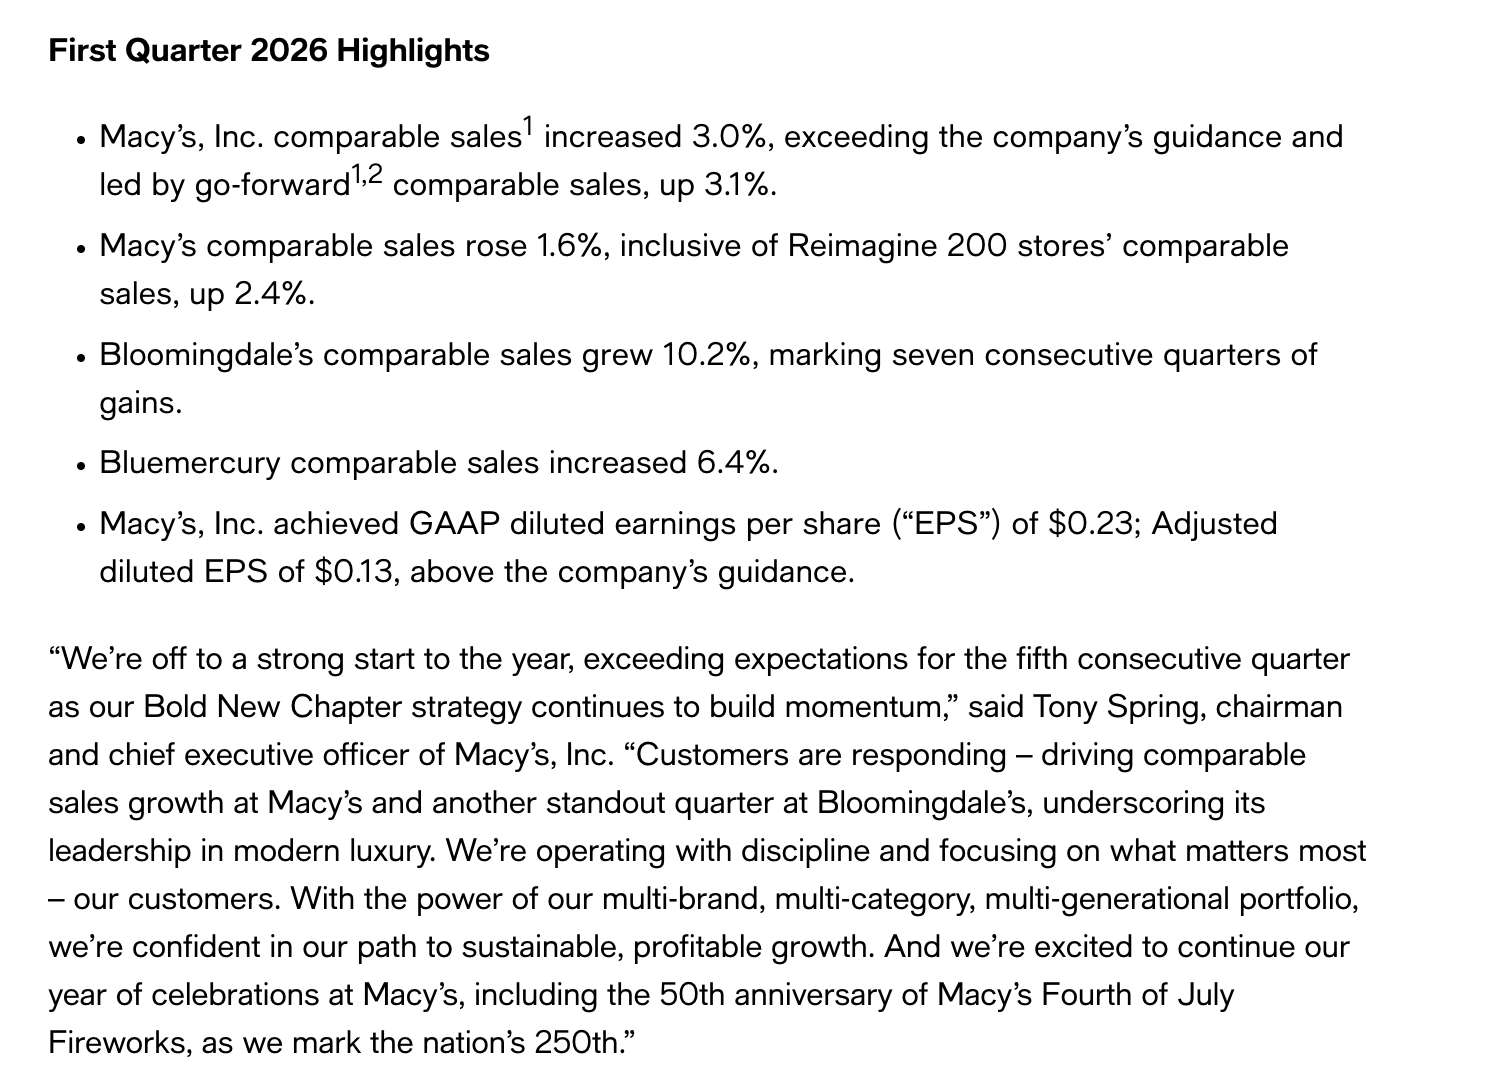
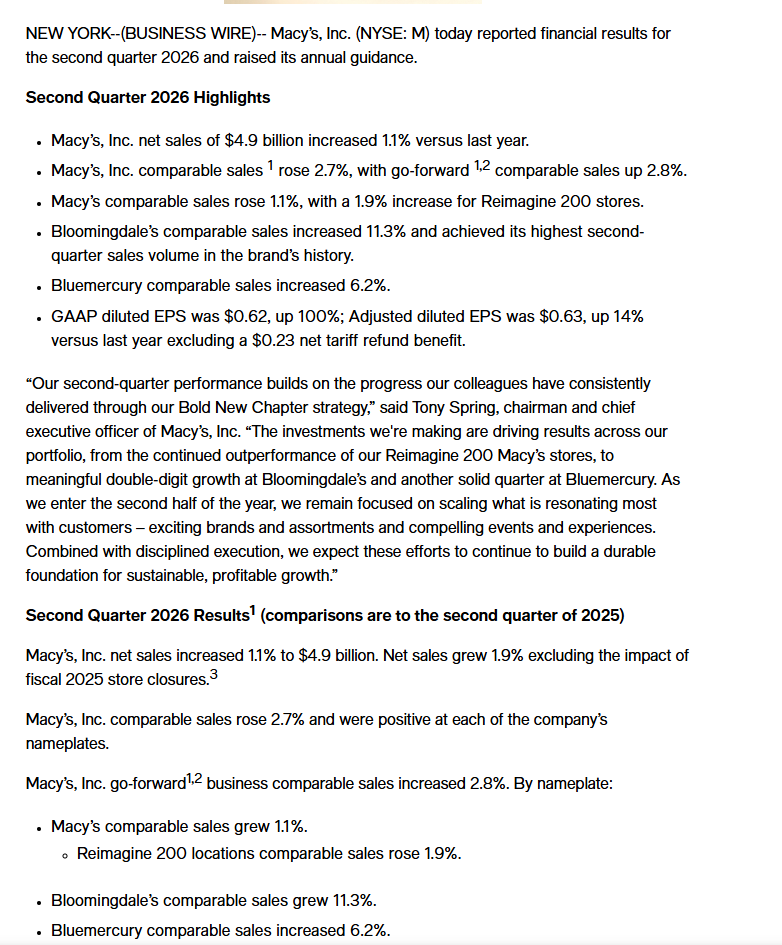
Macy’s clearly delivered better-than-expected results, e.g., sales grew across the board, and the company exceeded its own forecasts in both sales and earnings.
Improved demand was visible across different brands, and profitability also improved as costs remained under control.
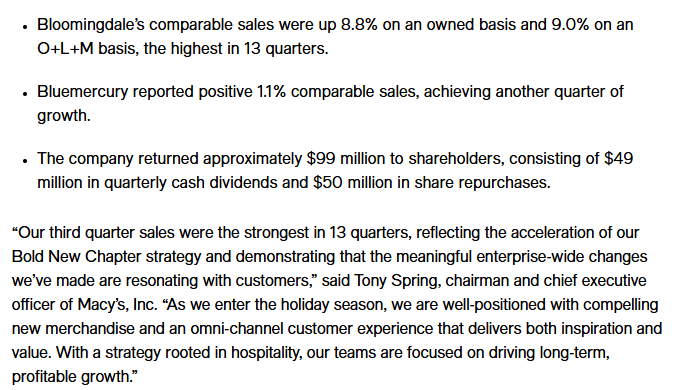
According to CEO Tony Spring, it was the company’s strongest quarter in a long time. He stated that the new strategy is working, customers are enthusiastic about the selection, and also how Macy’s is heading into the season from a strong position with its omnichannel customer-centric approach.
Macy’s continues its aggressive ”Bold New Chapter” strategy by closing 14 underperforming stores this year.
The chain is concentrating its resources on pruning 150 stores and subsequently renovating the remaining units.
At the same time, investments in luxury brands such as Bloomingdale’s and Bluemercury, as well as improvements to the store experience, have reportedly begun to yield results and accelerate sales growth.
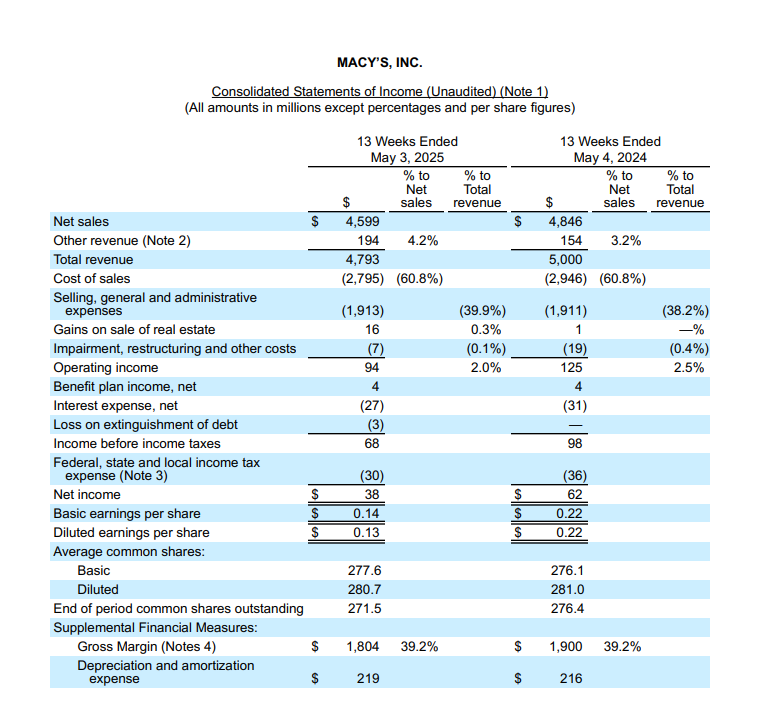
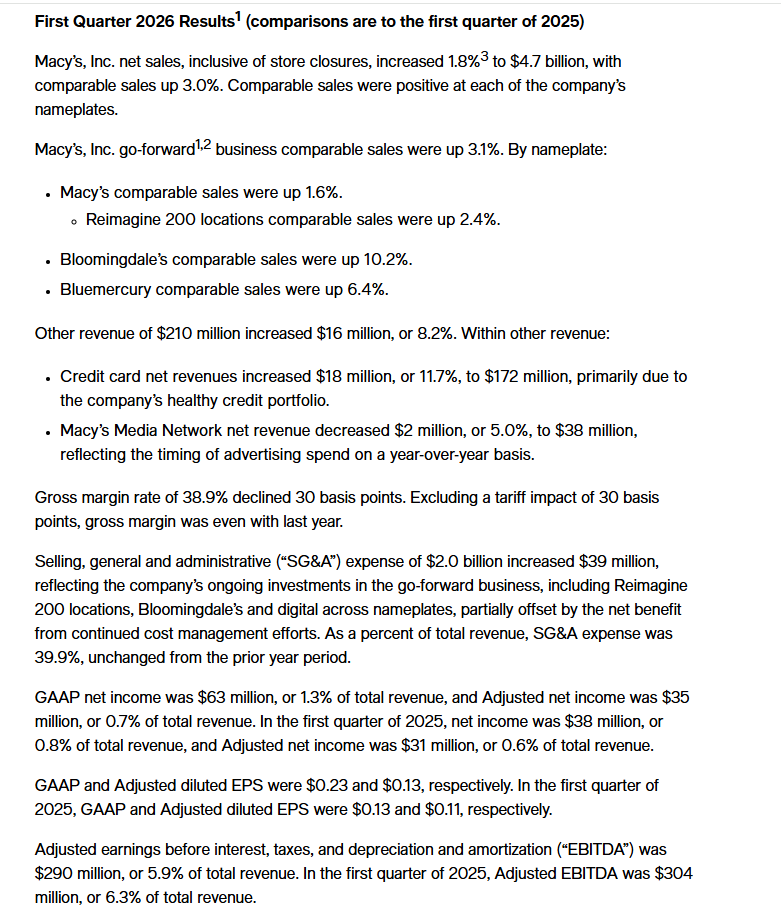
Macy’s Q1 looked two-sided; sales picked up, which reportedly suggests that the company’s turnaround strategy is gaining traction. Bloomingdale’s is performing particularly strongly, and the renovated stores are also supporting the main brand’s turnaround. On the other hand, profitability was simultaneously under pressure; tariffs, investments, and rising costs are eating into margins even as revenue grows. The increase in inventory was also a minor warning sign.
In any case, management raised the full-year outlook, which signals confidence in consumer demand and cost management.
Macy’s has appointed Alexandre Choueiri as the new CEO of Bluemercury, effective August 1st.
He brings over 25 years of experience in the luxury beauty industry, having worked at companies including Kering Beauté & L’Oréal. Going forward, Choueiri will be responsible for Bluemercury’s business operations and growth strategy in the United States.
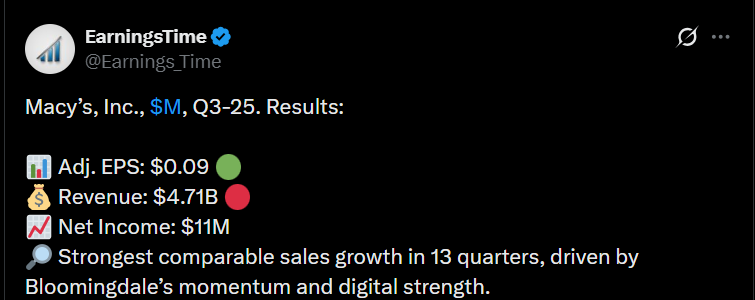
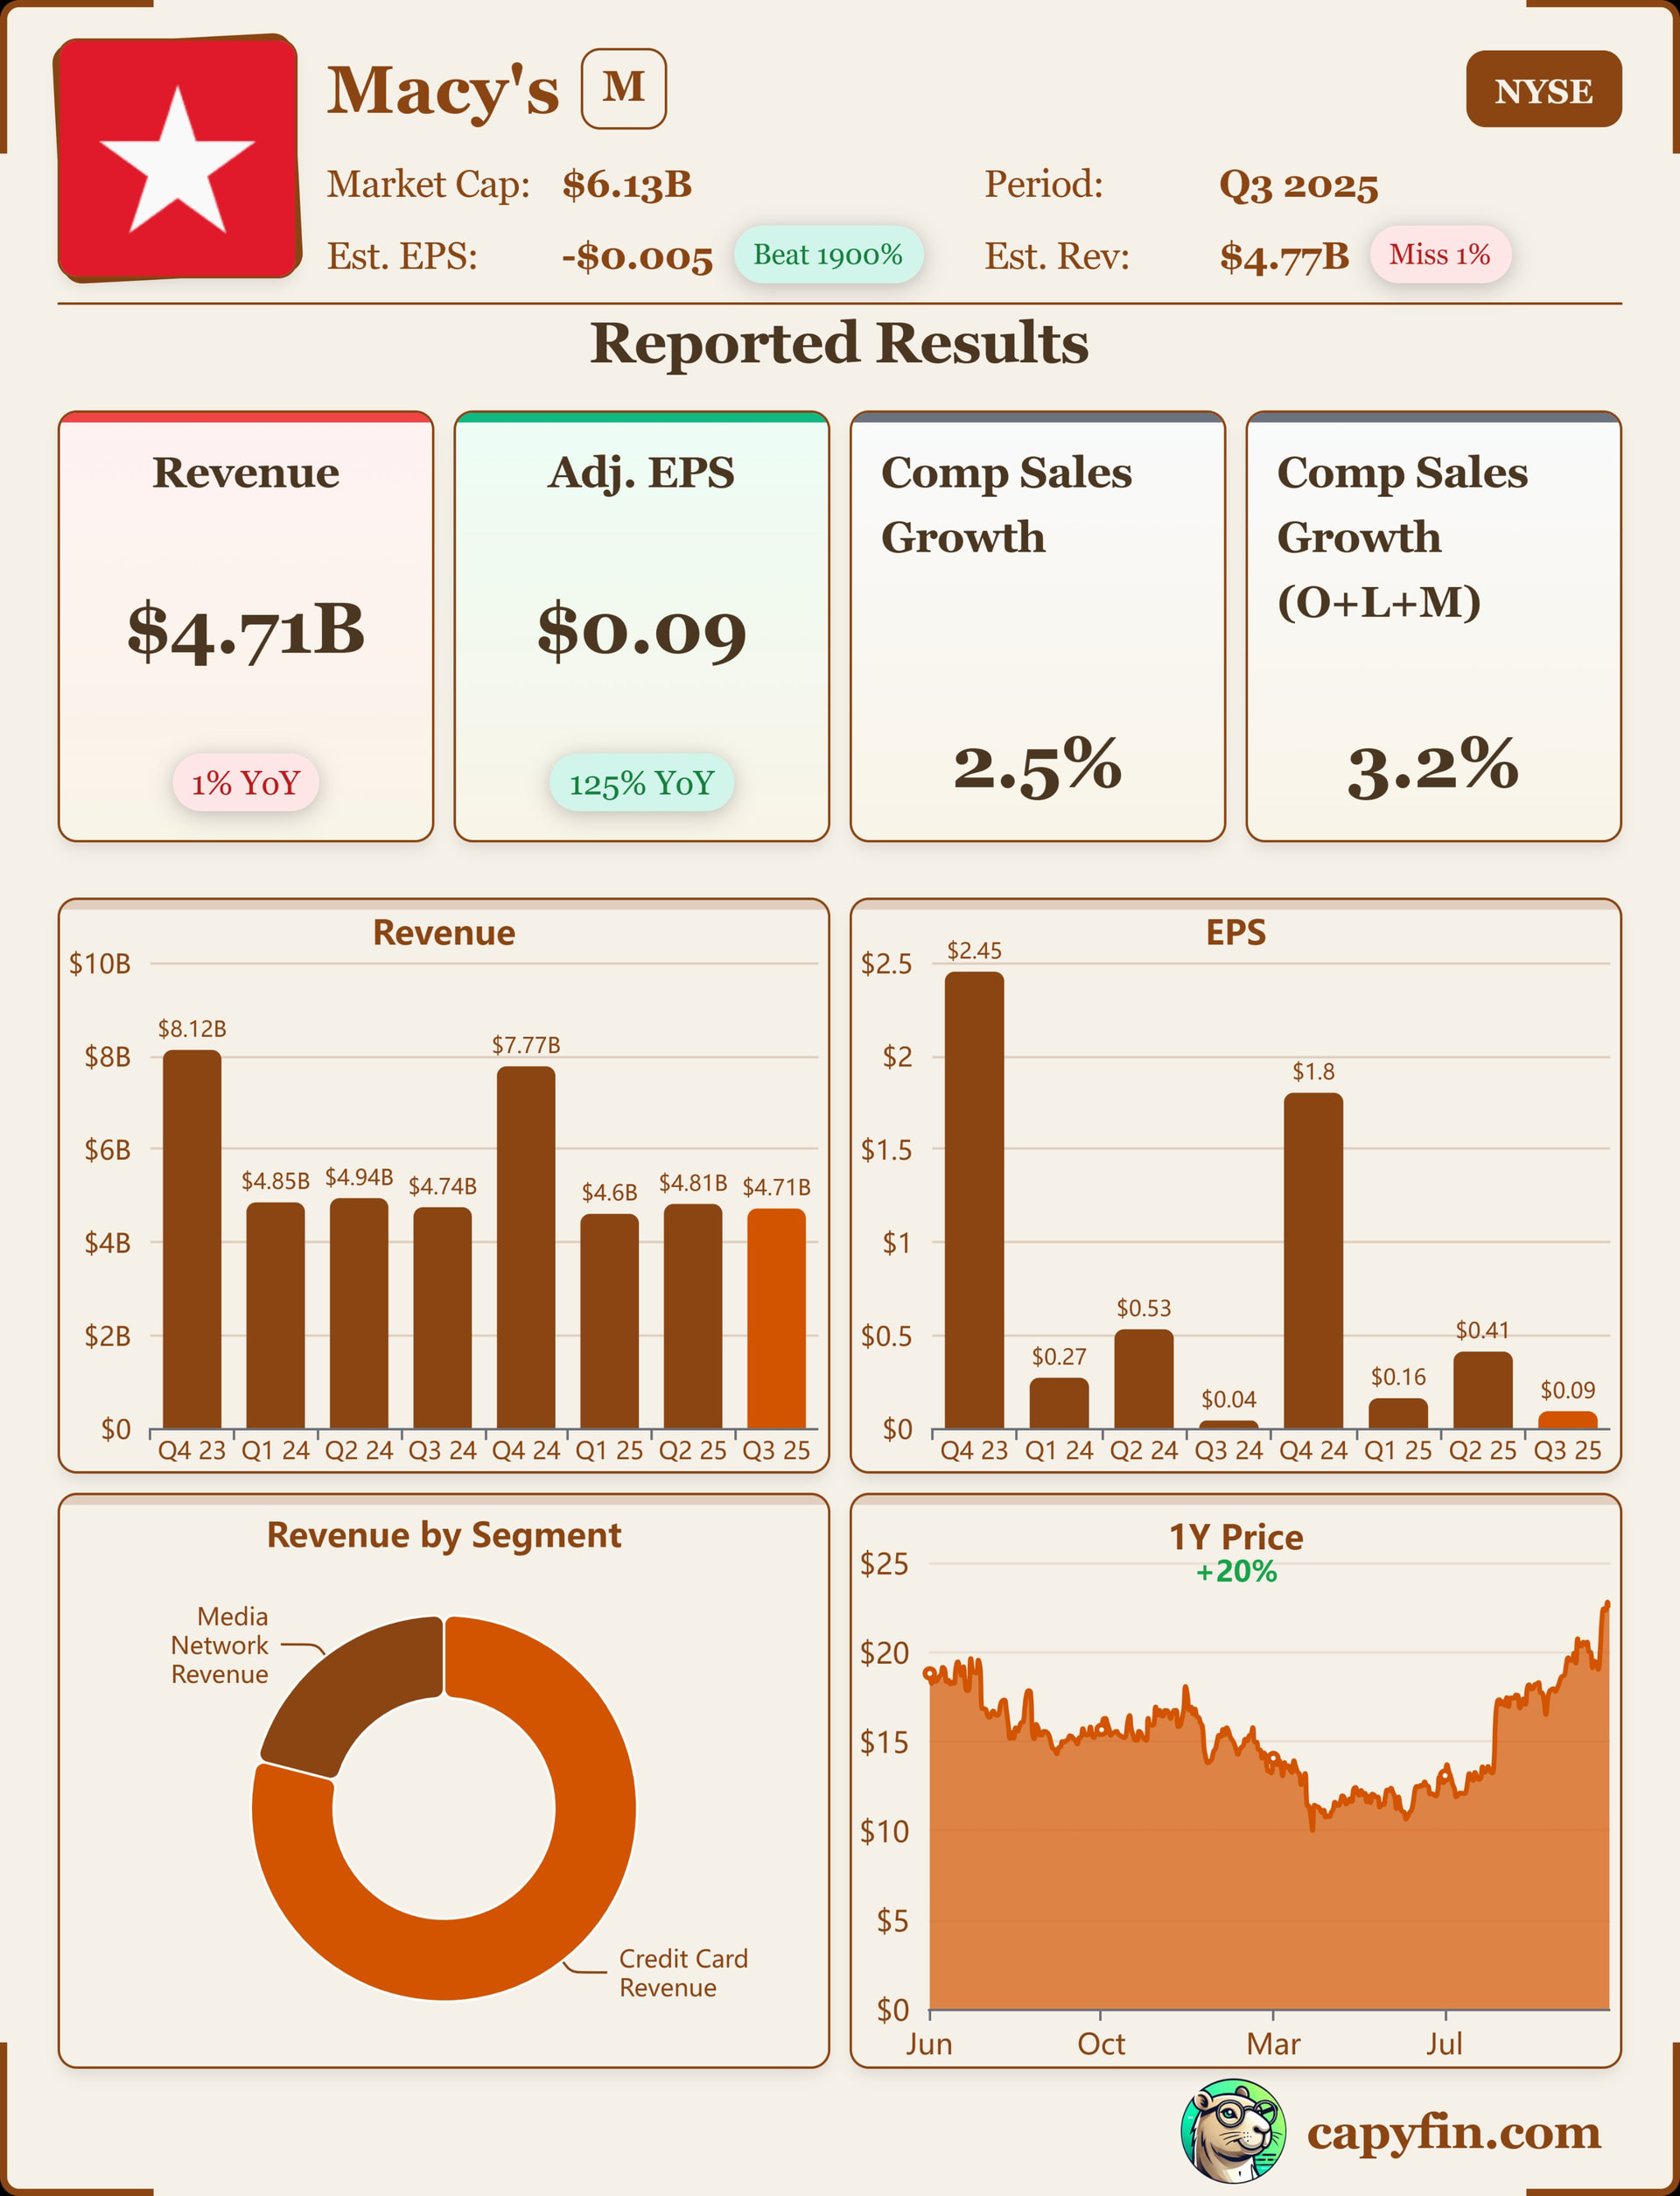
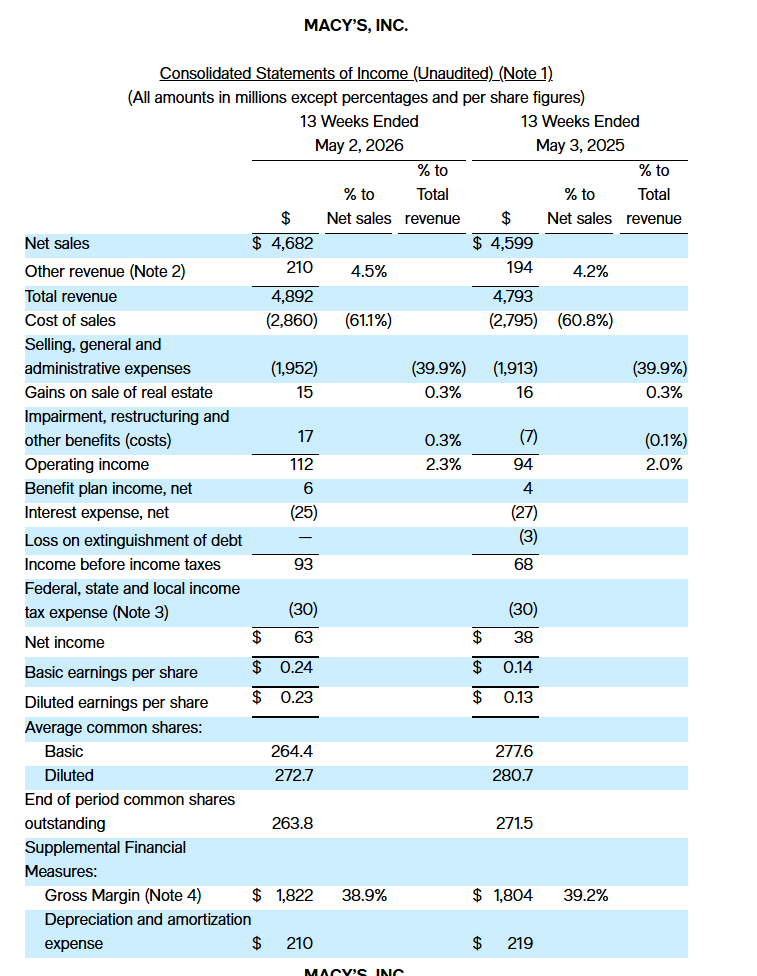
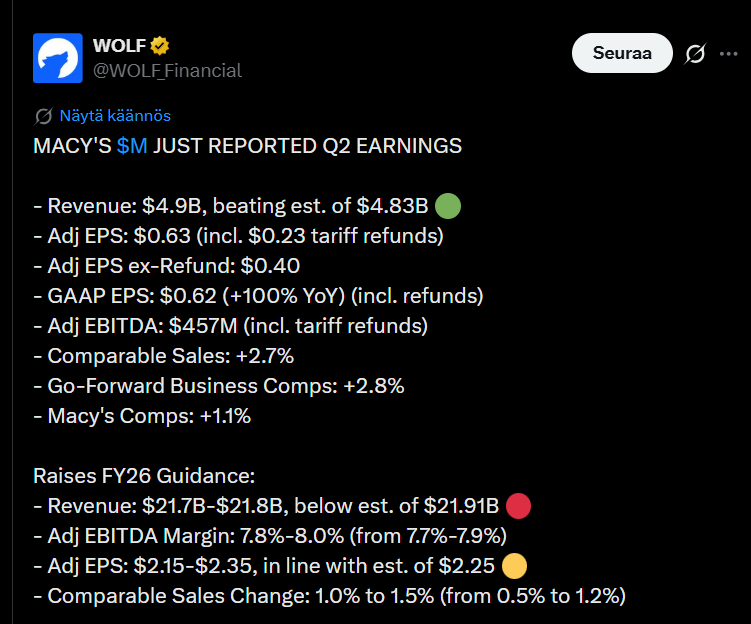
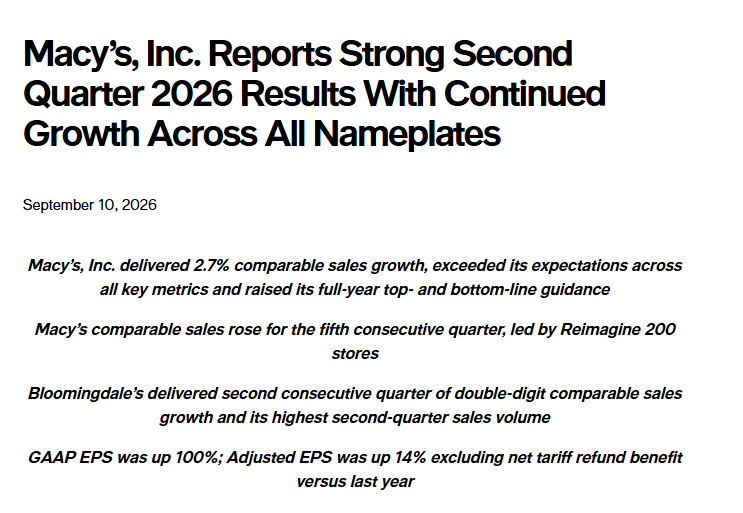
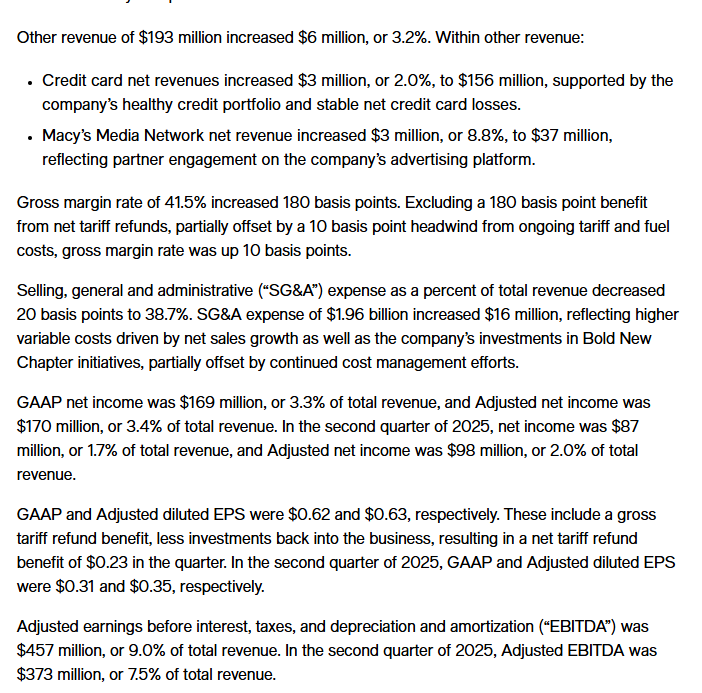
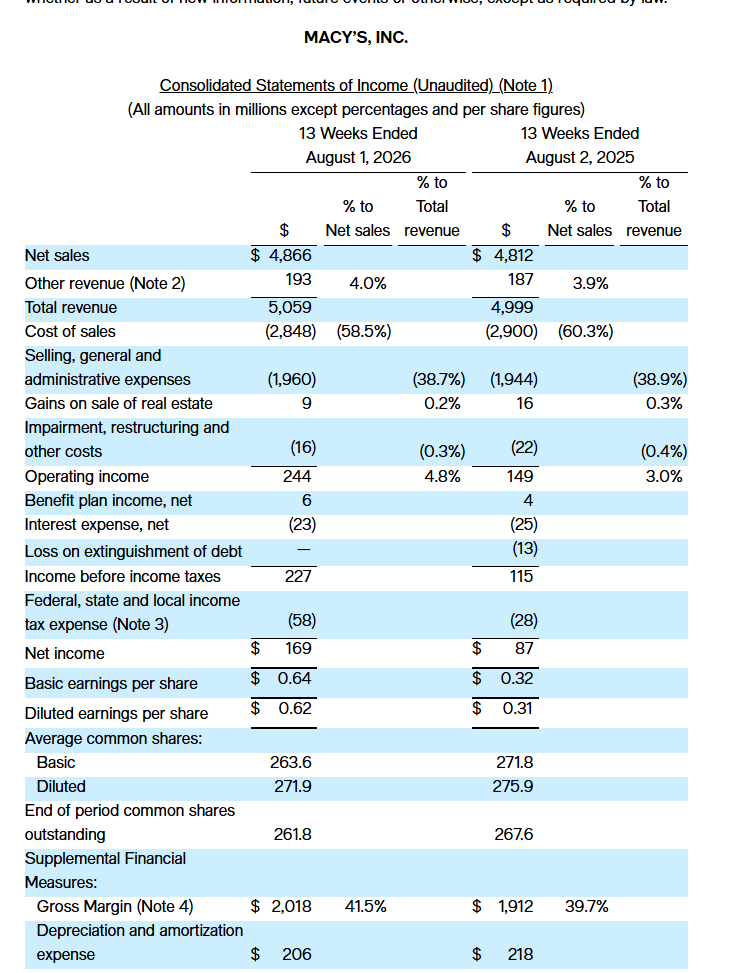
Macy’s sales performed better than expected; particularly Bloomingdale’s and the renovated department stores showed strong traction. But, but… it should be noted that the earnings still look better than they actually are due to tariff refunds. Even without this one-off benefit, profitability improved, but in any case at a clearly more moderate pace.
The company raised its outlook and plans to invest a large portion of the refunds into business development. Among other things, consumer caution still poses a risk, but on the other hand, the overall picture remains satisfactory because the core business is moving in the right direction.