Bitcoin has now risen above last year’s opening price. We considered this important for an impulsive upward movement to be possible. Our vision is discussed in our weekly video starting from the 26-minute mark. (link to the video https://www.youtube.com/watch?v=je9JdS6wab8).
Below is a screenshot from the part of the video where we reviewed last week’s situation. The red line represents last year’s opening price, and the thin yellow line is the 30-day moving average. The thinner red line is the idea of an impulsive movement drawn by Atte-Ville.
Views for crypto-themed videos, follower counts for influencer social media accounts, and similar metrics correlate perfectly with altcoin booms.
The graph below illustrates well how, in the cycle that began in January 2023, there have been only two brief periods when the retail crowd has participated even slightly.
One was in the spring of 2024, when Bitcoin reached new ATH (all-time high) levels. The other was after Trump’s election victory. Both lasted for about 2 months.
I could also track cryptocurrency prices just by looking at the view counts or page loads of Bitcoinkeskus’s social media posts, and I would be completely in the loop about where things are heading.
Benjamin Cowen @intocryptoverse
Here is a 30 day moving average of new followers to various crypto accounts on Twitter (X).
The price of the largest cryptocurrency, Bitcoin, has risen above $95,000 in the last 24 hours. This suggests that the sideways movement within a tight range, which lasted for about two months, might be coming to an end, and the price could potentially be turning into a new uptrend.
Also within the broader context of the investment markets, the situation in the crypto market appears quite interesting. The S&P 500 stock index is currently at record highs, as is the price of gold.
Cryptocurrency prices, on the other hand, are still far from their own record highs but are currently showing the first signs of a potential return to an upward trend.
The price of the largest cryptocurrency, Bitcoin, has retreated slightly after last week’s sharp rise and returned to the “range” of recent months.
The next interesting question is whether the price stays above $90,000. As long as the price remains above this level, it continues to form a “higher low” and maintains the interpretation of a continuing uptrend.
A drop below this level would, in turn, suggest a break in the uptrend and would make last week’s upward movement look like a “fake-out” instead of a “break-out”.
For now, however, Bitcoin’s price has remained above $92,000, and thus provides no grounds to question the continuation of the uptrend.
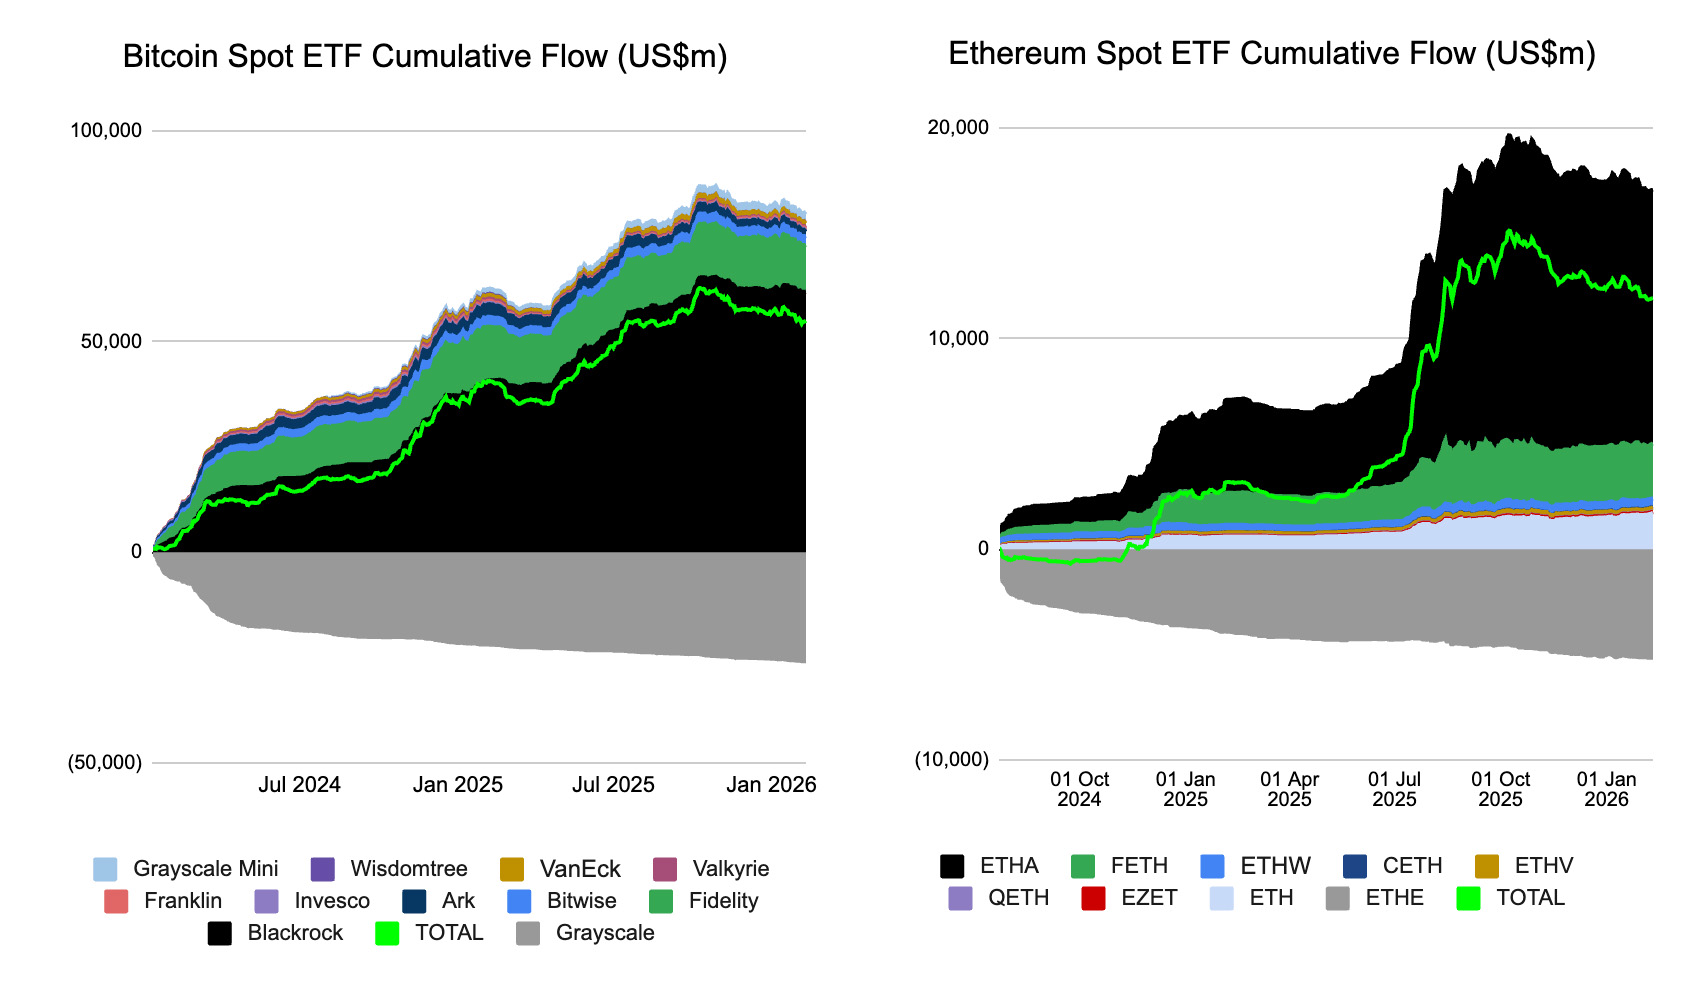
The beginning of 2026 has been favorable for bitcoin, although geopolitical tensions have brought challenges, as well as the sharp decline of the last few days. But here is a good graph showing the revitalized interest from institutions.
Last week, U.S. ETFs attracted a total of approximately $1.4 billion in assets. Q4 of last year was quite sluggish, which was the last time similar weekly figures were recorded. since the beginning of this year, investment flows have been in the neighborhood of a billion dollars.
Investor interest in bitcoin can be viewed from many perspectives, and particularly noteworthy is BlackRock’s IBIT, which saw an inflow of about a billion dollars last week. Additionally, ether and solana ETFs have maintained good levels, and net inflows for solana ETFs have been almost continuously positive except for one day (on January 16th, the overall situation turned into a net outflow of $2.2 million; so far, net inflows have accumulated to about $0.86 billion, which is clearly lower than the corresponding figures for bitcoin).
The growth in ETF flows provides positive signs. Fortunately, institutional investors are starting to better recognize the importance of bitcoin.
The price of the largest cryptocurrency, Bitcoin, has fallen back below $90,000 over the past 24 hours.
This increasingly makes last week’s “break-out” look like a so-called “fake-out.”
It would seem that the Bitcoin price is returning to the trading range between approximately $84,000 and $94,000 that has become familiar over recent months.
In this situation, we again believe it is wisest to treat price movements between $84,000 and $94,000 primarily as noise, and only draw stronger conclusions once the price breaks out of this range in one direction or the other.
China’s digital yuan (the e-CNY) has grown over 800 percent since 2023, becoming the world’s largest live central bank digital currency experiment, with cumulative transaction value exceeding $2.3 trillion by late 2025.
The adoption of the digital yuan is progressing rapidly, and China aims to increase its use in cross-border payments as well through the “mBridge” project.
Even CNBC, which is among the world’s largest financial media outlets, doesn’t seem to find any clear reason for the crypto market’s downturn.
The digital gold narrative no longer really works for Bitcoin, and when regulation soon makes it just like any other currency among all the others, what is it needed for?
This video offers an interesting perspective on the Bitcoin market.
The guy has worked on a trading desk and as an investor for, if I remember correctly, 46 years. Personally, I’m happy to listen to someone more experienced, as I’ve only been stock picking for 30 years.
One key message is that the Bitcoin market has changed since ETFs and big players entered the scene. The change is not for the better, contrary to what crypto investors had hoped.
“Crypto is all about narratives, it’s about stories,” he said. “Those stories take a while to build and you’re pulling people in … so when you wipe out a lot of those people, Humpty Dumpty doesn’t get put back together right away,” he said.
This sentiment was the complete opposite for the previous two years when the Bitcoin price was on the rise “Wall Street is pumping our Bitcoin bags”
The fact is that spot ETFs have opened an easier path to Bitcoin (and now other cryptos) for a great many investors. Especially in the US, there are many institutions and other entities sitting on big money that haven’t been able to invest in Bitcoin for various reasons, even if they wanted to.
If Bitcoin (and cryptos) are to grow as an asset class, big Wall Street money and eventually state-level players must get involved. Otherwise, it will remain a niche market. It is an absolutely good thing that spot ETF products have been launched.
In addition to this, regulatory clarity is another very significant factor.
For example, Bloomberg’s Eric Balchunas posted an interesting fact a week ago:
Only about 6% of the assets in the bitcoin ETFs have left (= 94% hanging tough), despite nasty 40% downturn and many being underwater.
So spot ETF buyers have arguably HODLed their bitcoins much better than even OG Bitcoin whales, who have been dumping their coins.
Even if the situation were different and spot ETFs had bled dry, the outcome would have been the same regardless. They could just as well have bought bitcoins through other channels and dumped their coins the same way.
Good insights. These news and market comments reflect well the stage Bitcoin is currently in. It has become integrated into the broader financial system, which has changed its nature on the exchange.
From an investor’s perspective, however, it is noteworthy that Bitcoin is managed in very different ways today, which is also reflected in the risk profile of the products:
Exchange-listed products (ETFs and ETPs): These are effective tools for price tracking, but they are structured as contracts that carry issuer risk. Experience of this has been gained, for example, from the price difference of Grayscale (GBTC) relative to the underlying asset or the counterparty risk faced by CoinShares in connection with financial crises.
Direct on-chain ownership: This is the original way to own Bitcoin directly on the blockchain. It is independent of banks or fund management companies, which is particularly emphasized when there is uncertainty in the market regarding the solvency of intermediaries.
How do different actors manage their investments? The market shift seen now also shows a difference in how different actors operate. Institutions often use Bitcoin as part of broader portfolio management, where automatic risk management models drive selling along with the rest of the market. This creates a new kind of mechanical selling pressure. For the retail investor, decision-making is often more flexible, but news flow and price volatility can affect sticking to the plan.
Why is the 21 million cap practically immutable? The discussion has touched upon Bitcoin’s necessity relative to other currencies. In the light of history, changing the rules in Bitcoin is a very slow process, which creates predictability:
SegWit (2017): Proposed in December 2015. Activation eventually took about 20 months (August 2017) and required an exceptionally broad discussion between the community and miners.
Taproot (2021): First ideas in January 2018. The code was completed and activation only occurred in November 2021. The process lasted nearly 4 years, even though there was a high degree of consensus regarding the change.
In addition to the slow technical process, there is a strong economic incentive behind the 21 million limit. Miners, node operators, and investors are all in the same boat: increasing the supply would dilute the value of their own holdings. It is difficult to imagine a situation where a majority would vote for a rule that would weaken their own financial position.
Ultimately, it is about whether you want a contract for value in your portfolio or the asset itself, whose foundations have been reinforced by such a multi-layered process. Both have their place, but in market turbulence, the difference between the two may become concrete.
Doom and gloom stories started in the media surprisingly quickly. These are usually a good gut-feeling indicator of a bottom, but it’s hard to believe that we’ve seen the bottom yet. There is no bear market without capitulation.
“we have concluded that the time is right to offer cryptocurrency-related investment products to customers who want to invest in this asset class and accept the very high risks associated with cryptocurrencies”
Investors are the only ones who do not benefit from continuous low inflation. For miners, a better option would obviously be, for example, a steady 1% inflation. They wouldn’t be dependent on transaction fees in the future; instead, cash flow would be more predictable. Just as, for instance, Ethereum offers a steady yield for stakers.
Exchanges, banks, and ETF issuers would also benefit from low inflation. It would keep things moving. There would be more buying and selling, and these entities would collect percentages here and there.
And as mining and holding gradually concentrate toward these institutions, they might have completely different incentives to change Bitcoin’s 21 million hard cap in 10 years. It would be naive to think that at that point they wouldn’t at least consider pursuing their own interests.
One can be, and perhaps should be, worried about Bitcoin, but not necessarily Ethereum. Post-quantum transfers are already being run on testnets there, and the Ethereum Foundation has made quantum computers a top priority. Things move quite quickly there and they understand technological upgrades. Unlike Bitcoin, which clings to its religion.
“Quantum computing is moving from theory into engineering,” said Thomas Coratger, who leads the Ethereum Foundation’s (EF) Post-Quantum (PQ) team. “That changes the timeline, and it means we need to prepare.”
Earlier in January, the EF formally elevated post-quantum security to a strategic priority, creating tjat dedicated PQ team to drive research, tooling and real-world upgrades to protect the network’s cryptographic foundations.
For the EF, the move toward post-quantum security isn’t about sounding an alarm, but it’s about not getting caught flat-footed.
Coratger has spent the past year quietly working on post-quantum research within the EF, before the effort was formally announced this month. The creation of a dedicated team made public what had already become a growing concern internally: if quantum computers arrive sooner than expected, Ethereum needs to be ready well before that moment.
“We already have test networks running with post-quantum signatures,” Coratger said.
One thing that has stood out to Coratger over the past year is how quickly the underlying science is advancing.
“New breakthroughs are happening all the time,” he said. “Sometimes it’s hard to keep up.”
To keep up, the Ethereum Foundation is working closely with outside researchers and developers on post-quantum efforts.
For Coratger, the takeaway is that post-quantum security has crossed an important threshold.
It’s no longer a distant thought experiment or a purely academic debate. For Ethereum, it’s becoming a long-term engineering project, one that will shape how the network evolves over time.
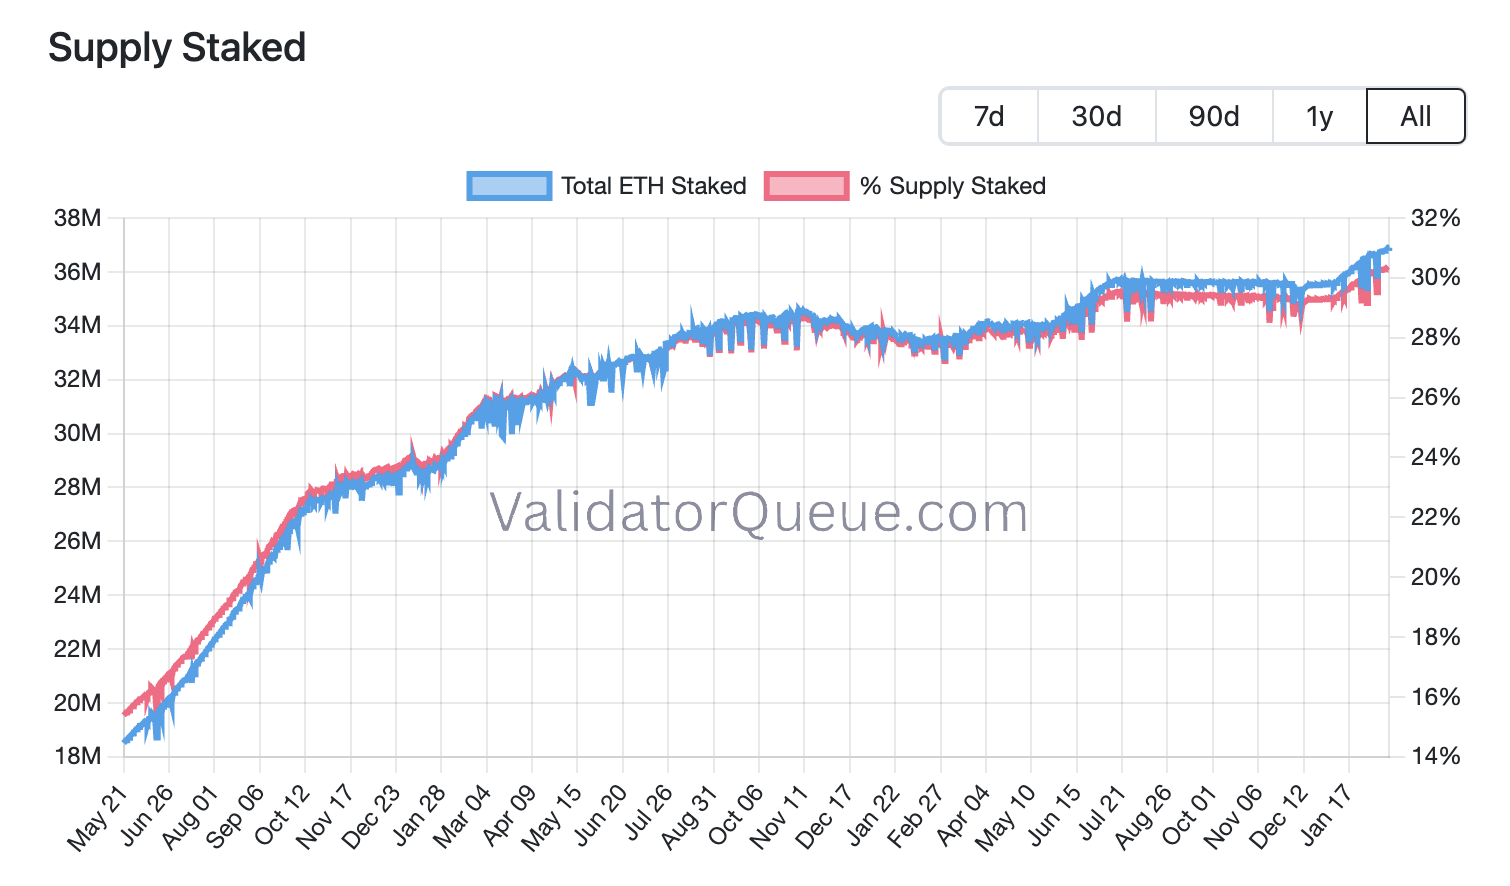
I have summarized a few key takeaways here regarding what this growth and ETF development mean for network security and the financial market:
1. Growth of network security and credibility
Increasing cost of attack: The more ETH tokens are staked, the higher the threshold for hijacking the network. An attacker would need to control more than half of the total staked amount, which would require an investment of tens of billions of dollars. This makes compromising consensus extremely unlikely and expensive.
Blockchain finality: A large number of validators ensures that transactions are confirmed quickly and irreversibly. This is a critical factor when considering Ethereum’s role as a platform for banking services and RWA (Real World Assets) projects, where transaction finality is an absolute requirement for investors.
2. ETF applications and the staking component
Return to the conversation: The market is now closely watching whether a staking option (staking yield) will be approved in the later stages of Ethereum ETFs. If ETFs were able to benefit from this approximately 3% annual yield, it would change the nature of Ethereum from a passive investment asset to a yield-bearing asset. E.g., BlackRock (ETHB).
Institutional-grade demand: With ETFs, it is easier for institutions to allocate capital to Ethereum, but without staking, they miss out on the cash flow provided by the network. This creates pressure for regulatory clarity regarding staking.
3. Economic impacts and risks
Decrease in liquidity and scarcity: When nearly a third of the tokens are locked in staking, the amount in free circulation decreases. If ETF demand hits the market at the same time, the supply shock can be powerful. On the other hand, lower liquidity can increase price volatility.
Centralization risk: While the staking amount grows, the distribution of power must be monitored. If power becomes too concentrated with certain actors, it creates a structural vulnerability. Regulatory pressure or a technical error in one large service could be reflected in the operation of the entire network.
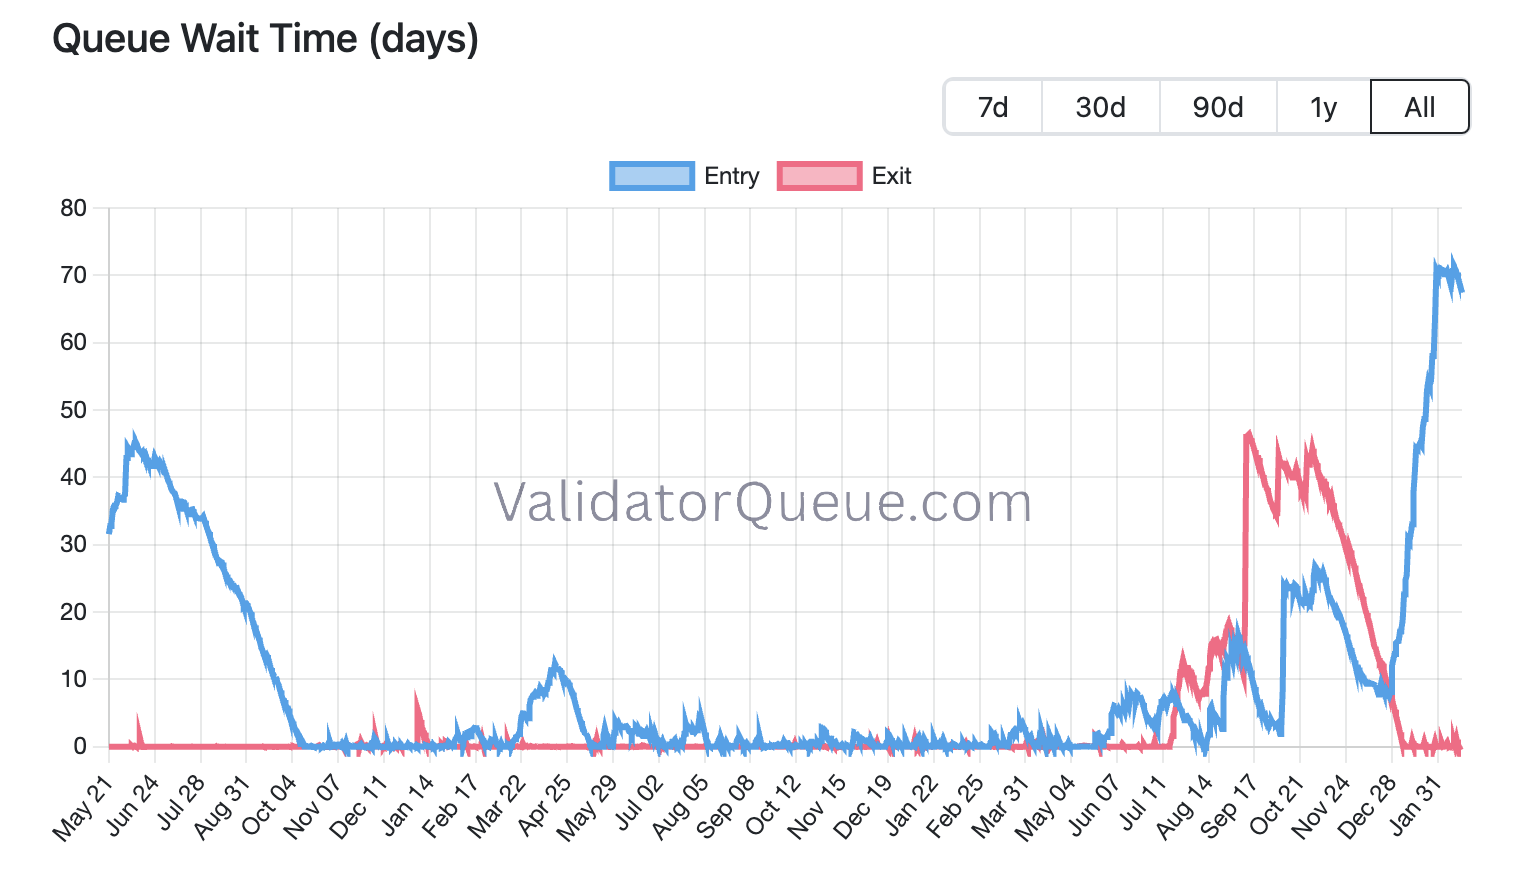
The long queue is a very bullish sign. It indicates that the demand for “interest/dividend-like yield” is massive and capital is flowing into the network faster than it can be accepted. This locks ETH away from the sell side for a long time. What do you think?


 “Wall Street is pumping our Bitcoin bags”