Incap as an Investment

Could someone ask management what caused the doubling of financing costs from last year, even though the company has a large cash reserve and Incap is net debt-free?

1–9/2025

Financial income 2,608

Financial expenses -5,651

By my calculations, a net debt-free company with a large cash reserve should generate more financial income than expenses…

6 Likes

Non-cash entries caused by currency exchange rate movements are the main reason. If you look at the paid financial expenses, the development is more stable. However, Incap is unable to generate (proper) returns on its cash

35 Likes

Do changes in working capital indicate that the rest of the year would be better?

6 Likes

No. Inventory grew only slightly from June, and it has indeed decreased since the beginning of the year, so it certainly doesn’t support the idea that large quantities of goods would be leaving “right away.”

The performance is indeed surprisingly weak. Of course, the valuation multiples have also melted again compared to the summer, and it seems that huge expectations are not baked into the current share price again.

10 Likes

This was soft, and we fell short of analyst forecasts. On the other hand, a quick glance at the numbers reveals nothing surprising in itself. Everything seems to be in line with normal, but business was just smaller than in the corresponding period last year. Could this be some kind of defensive victory, where the current situation is a disappointment, but comments about the next quarter are cautiously positive and thus cover up the worst disappointment?

We thank:

  • Strong cash position and thus good room for maneuver, e.g., in acquisitions
  • Profitability was defended excellently, even though revenue was under heavy pressure
  • Better performance is already anticipated for Q4, and since almost a month of Q4 is already done, perhaps this optimism can be cautiously trusted

In the future, we see signs of improvement in our business. Our sales pipeline for the fourth quarter looks promising, and we expect some improvements in the coming months. We will continue to closely monitor global developments and react to them agilely.

The valuation for this year is tight, but if growth is achieved next year and profitability also improves slightly, the valuation would already be on the neutral side.

That’s how it seems to be going. Below is a quick summary if anyone is interested in the peers but doesn’t want to dig up the numbers.

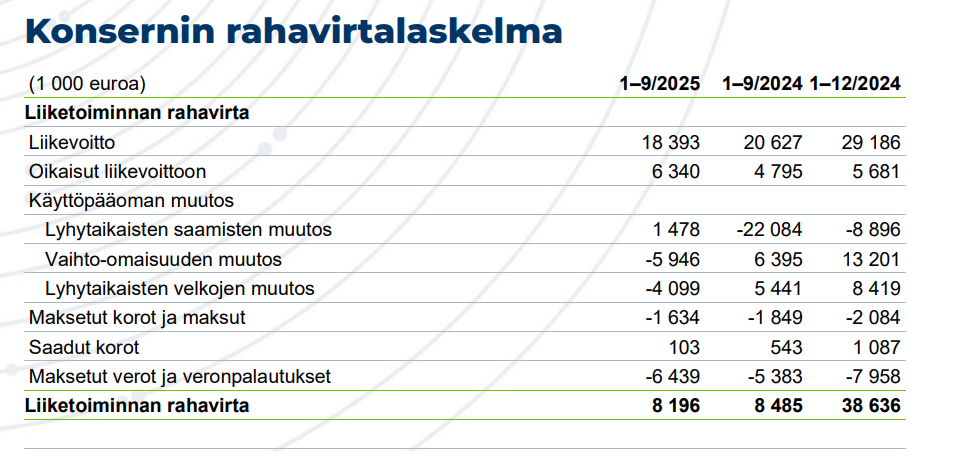
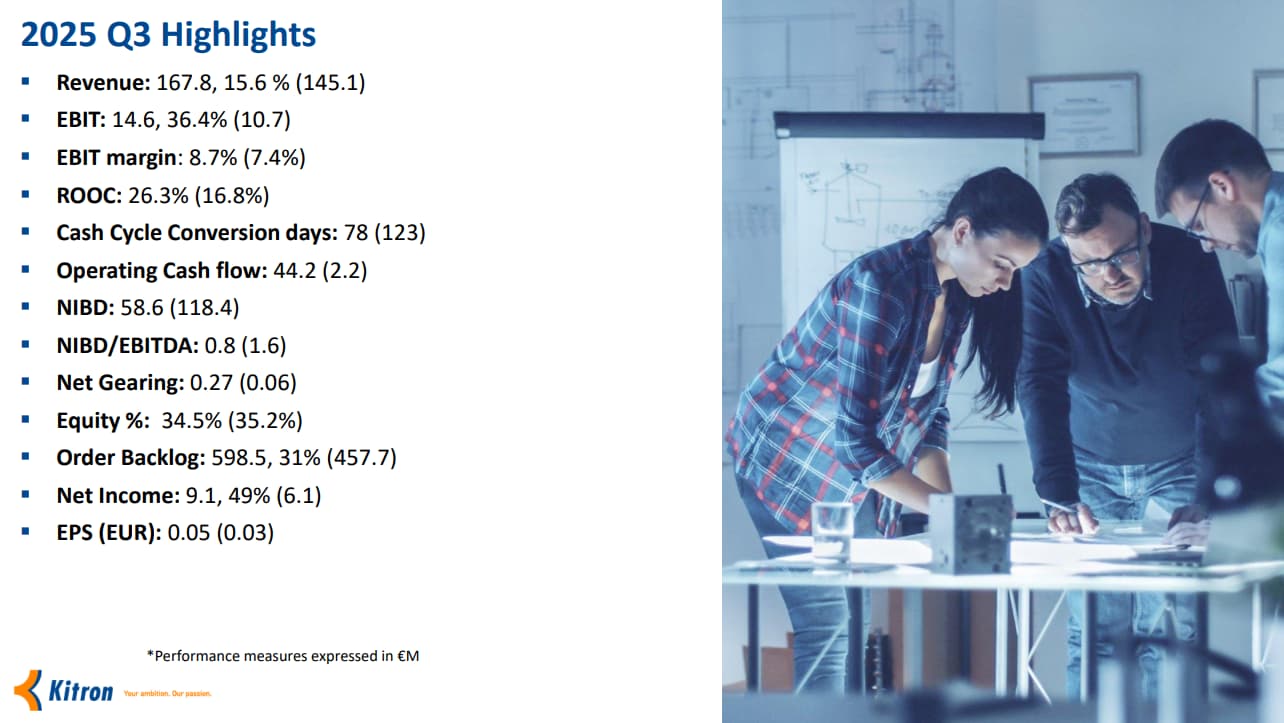
From Norway, Kitron posted strong numbers and raised guidance:

Swedish Note also grew and improved its profitability:

Scanfil also delivered good numbers and positive development on every line:

I didn’t check to what extent these include inorganic growth or one-off items, so direct comparison is not advisable. But this gives an overall picture.

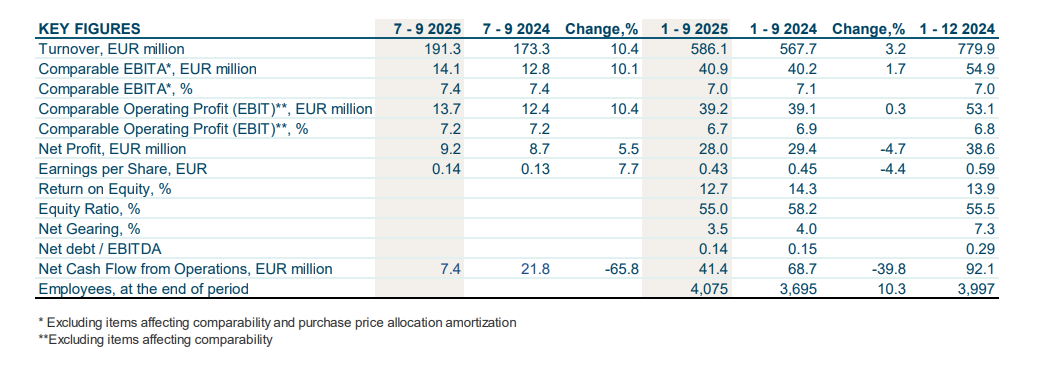
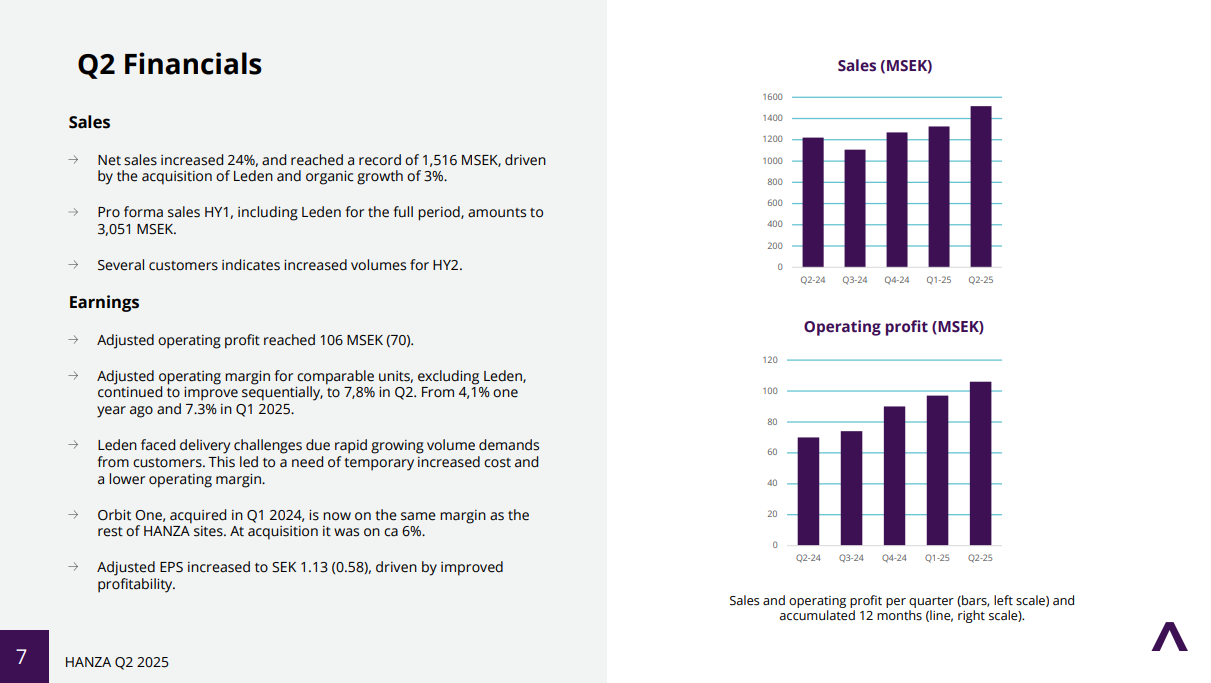
I noticed that Hanza has acquired BMK, and according to this press release, it would become Europe’s largest EMS player. Q2 report went well (Q3 will be published next week):

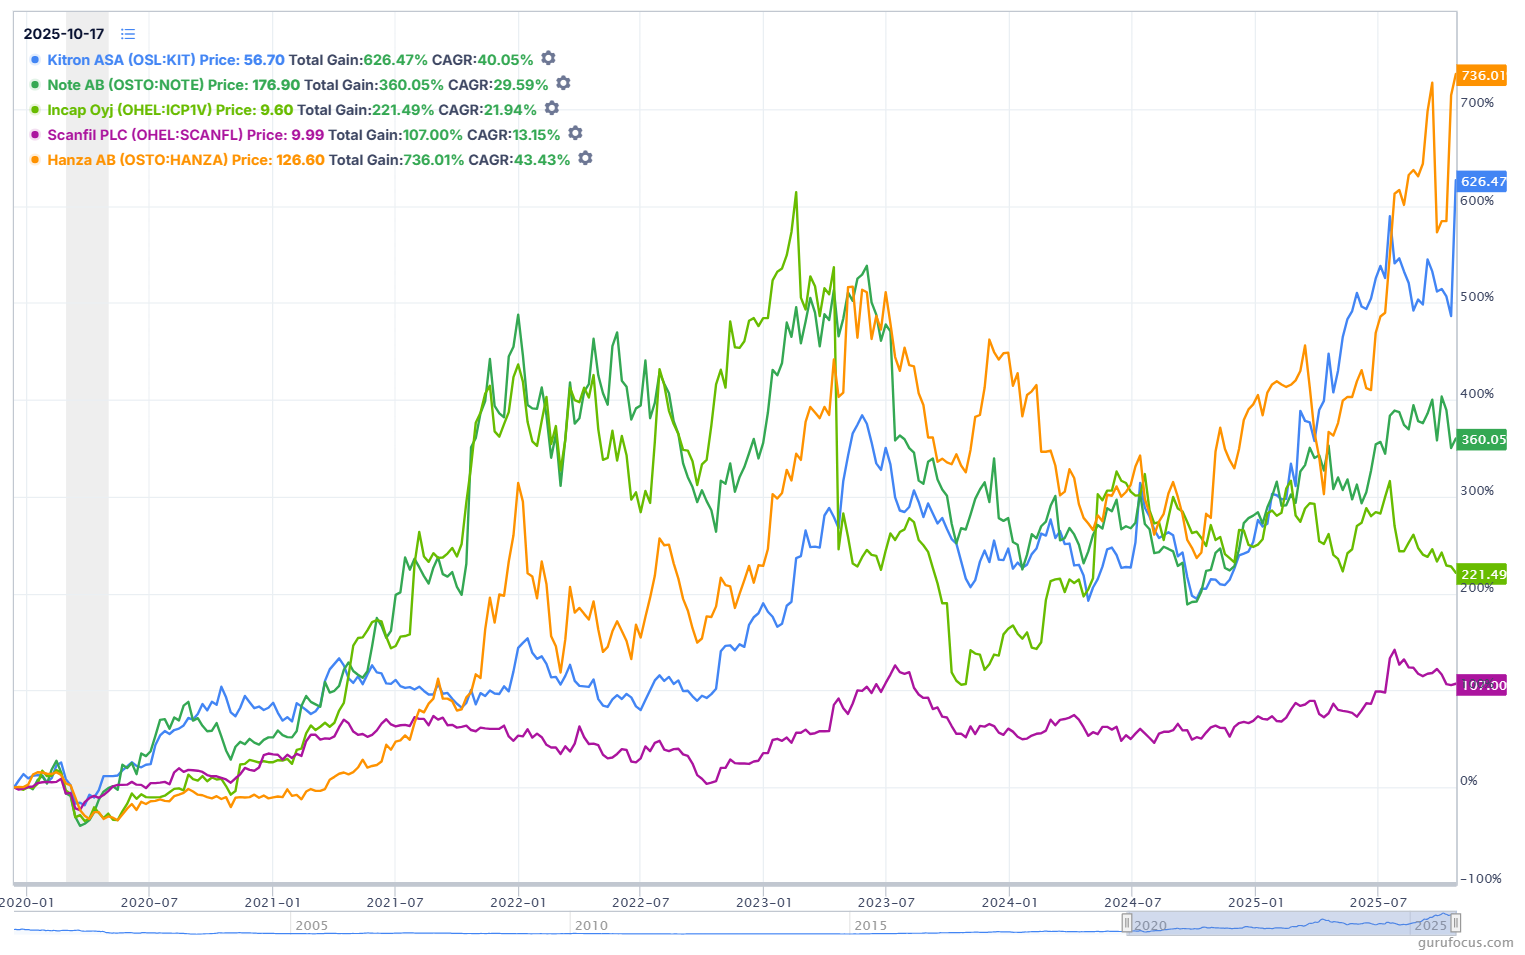
Here are their returns for the 2020s, followed immediately by valuations. Good returns have been made across the board, although it’s been quite a ride up and down if you examine the shorter-term percentages. The valuation chart is clearly not entirely up-to-date or complete in terms of data, but a quick glance shows that the big picture is quite relevant. Where performance has been good for many again after the 2023-2024 dip, valuation multiples have also started to stretch.

33 Likes
  1. How has revenue developed by unit? Has the decline been consistent across the board, or has any unit performed relatively better/worse than others?
  2. And similarly, how about revenue development when examined by customer sectors? Has there been significant development in different customer sectors relative to each other?
2 Likes

Quick greetings from the webcast: Regarding Q4, quite comprehensive internal analyses had been made, and based on agreed deliveries, a positive final quarter and achievement of guidance were dared to be anticipated in the report. The deepest trough in business has been surpassed, and now we are heading towards the light. Something can always happen, but Otto mentioned that now that the quarter is already a bit behind us, there is no reason to touch the guidance. Would Viljakainen’s forecasts still be up to date, and no significant changes needed?

Such greetings to @Pauliina_Tennila & @Antti_Pynnonen & @Otto_Pukk, that even though Teams serves its purpose in the sense that one can barely live with it, please take Inderes’ Videosync back into use as soon as the purse strings allow even a little. It is just such a superior solution for interim reports. :wink:

39 Likes

Antti interviewed @Otto_Pukk after the Q3 earnings release. :slight_smile:

Topics:

00:00 Introduction
00:13 Sales
02:16 Delayed projects
03:08 Profitability
03:56 Financing costs
05:00 Sales pipeline
05:40 Outlook
07:22 AI and data center markets
08:35 Acquisitions

9 Likes

It’s a BUY case, says Viljakainen

29 Likes

Hello Everyone here at Incap forum! First of all, Thank you very much for the interest in Incap, excellent questions during the Q3 Webcast and the activity here! Please find below summary of the Q&A:

Q: Incap’s guidance assumes a strong Q4. What gives you confidence that the target is achievable?

A: We are within the Q4 already and we know well what orders we have. So, we have quite high confidence when it comes to the outcome. Of course, something can always happen but it’s very unlikely that we wouldn’t hit our marks.

Q: Is the guidance based on already confirmed orders or is it more based on the signals about improving customer demand in the Q4?

A: It’s based on confirmed orders. When we talk about the running quarter then we are already talking about actual orders. As I’ve said before, in the period of three to six months we know quite well where we’re going because of the orders. In our business, material lead times often are as long as three months or sometimes even longer. So, we are very well aware of what we are going to do in the coming months, and this is production we have already planned a few months back. We just internally finished a quite extensive forecasting round in the beginning of October, and the feedback and the overview we received is very much supporting this statement on Q4.

Q: Can you comment about potential differences of revenue and profitability across the units or segments, and their development?
A: We normally don’t report those separately or comment in detail on segments or units. But, of course, there is always differences and variation between the different units depending on their customers.

Q: How would you comment on the demand situation across different geographical regions?

A: I think we still see some effect of the US tariffs and uncertainties from some regions. It also needs to be kept in mind that the trade deals are still not in place in all regions. That is still in the background of some of the plans and the demand situation. In general, we see some growth in defence and aerospace sector which we still have a quite small exposure to , even if it has grown over the years. There’s also increase in demand around the data centres and AI, and of course that infrastructure is normally taken by the bigger tier ones. But we see demand in projects around the infrastructure and there we are also active. The general market demand is quite flat what comes to classic industry, and we don’t see any huge increase in demand besides these two sectors where we see growth currently.

Q: What is the reason behind high financial expenses?

A: It’s a large number that we reported under financial expenses. Financial expenses consist of the unrealised currency rate effects, realised currency rate effects, leasing related financial expenses, and typical bank loan related interest expenses.
The whole amount of EUR 5.5 million is not only loan expenses paid to the banks, cumulatively we paid about EUR 700,000 for the loans in interest fees. The largest item is unrealized currency rate effects, totalling EUR 3.5 million. They relate mostly to internal foreign currency loans that we have granted to subsidiaries and then re-evaluated at the end of month. So, these fluctuations explain the majority of that part. Then smaller amounts are related to the leasing liability, amounting to some EUR 300,000. A bit over 10% was realized currency rate effects. So, the largest amount by far are the currency rate fluctuations and minority are the real financing fees.

Q: Could you explain the effect of the US dollar and the Indian rupee in more detail, and how it affects your top line?

A: Approximately one quarter of the revenue difference between this quarter and last year’s comparable quarter is explained by currency fluctuations. The units report their figures to the HQ and we consolidate the values with the average rates and then compare them to the last year Q3 figures.

For example, Indian rupee has weakened quite dramatically against euro and there’s over 10% of fluctuation. We receive their figures in rupees as that is the functional currency of Indian entity and then we mathematically convert the figures to euros to consolidate the subsidiaries. So that is the explanation behind this impact.

In India we buy and sell mostly in US dollars which are then converted into rupees for the reporting which are then converted into euros. So, there’s a lot of mathematical exchanges that take place in the reporting. We have three large factories in India where business is mostly in US dollars and of course our US factory as well so the majority of the business in Incap is in US dollars and not in euros. In our UK unit we have of course British sterling, and it is converted into euros for the reporting.

Q: Are you planning to increase inventories in the coming quarters?

A: If the volumes go up then of course inventory goes up as well. That said we have been working on reducing inventories as we were overstocked some time ago. Also, material availability is better on the market and that means that inventory levels can be taken down as we don’t need to buffer up materials as much as in the past. Our current inventory level, which was a little bit higher than the previous one, is some kind of indication of the volume level, but you can’t take it one-on-one because there are more factors into it.

Q: Can you comment on the volumes for your largest customer and how do they look going forward?

A: Our volumes to our largest customers are stable and we continue to serve them on a high level. That said, we have been working very much together with them to reduce the cost for their products and to find alternatives when it comes to different components that are cheaper. Of course, that takes down the product price even if we earn a percentage-wise the same money. If the bill of material cost goes down in the product, we will in absolute terms earn less. So, that has a little effect when looking at this year compared to earlier years. We are producing the same or even higher volumes, but we earn less because the work has been done with the product prices to get them optimised and cheaper. It’s part of our service and we try to help our customers to achieve their goals when it comes to cost levels.

Q: How much do you ship from India to the US and are you currently suffering from the higher tariffs from India?

A: The volumes going from India to US are about 20% so far this year. So, it hasn’t impacted so much directly, but India and US are still settling their trade and have not the trade agreement fully in place yet. So, let’s see how it ends up – but we continue to ship to US from India and will hopefully do it in the future as well.

Q: Are there any regulatory or structural challenges for you in getting a larger share of revenue from the defence sector?

A: There are no hurdles posed by law or regulations, and we’re working on increasing the defence segment as well. Defence sector companies are quite old and conservative. It takes time to qualify, and even if we have now qualified with several of these bigger defence giants, it still takes time before it will become a vital part of our business. That said, in the newer defence segments like drones and other start-up companies in the industry, the hurdle is much lower and there we have quicker developments. The defence industry is quite conservative so it takes time. The defense market is still expected to go up and peak somewhere around 2030. So, I think the work we are doing will pay off.

Q: How much cross selling potential do you have from the US Pennatronics acquisition and how much of that potential has already been realized during the first two years you have been operating as one unit?

A: I think we have quite good development when it comes to cross selling opportunities, and we have several customers out that are or have been exploring the possibilities, and we also have some production started with them. When we did the Pennatronics acquisition, several of our customers realized that we are now more globally positioned and they look into possibilities to take advantage of that. So, I think it has gone very well.

Q: You have a lot of cash on your balance sheet – what plans do you have with that? How is your M&A pipeline, and how do see the valuation of the potential acquisition targets?

A: We, naturally have plans for the use of the cash. M&A market is currently more active, and we have a good pipeline. Incap is looking for different ways of growing through organic growth, which is something we explore very aggressively. On the other hand, we see also the consolidation giving a lot of opportunities on the market through acquisitions. Recently, within past three to six months’ period, there have also been bigger size acquisition targets, let’s say around EUR 100 million and even higher revenue companies, available. With the firepower and a very healthy balance sheet and cash position we are of course keen to explore all the potential targets out there. Growing through acquisitions obviously needs a lot of cash and it also helps to move quickly when the right target arises. In that sense, we are ready if there’s a good opportunity and the valuations and cultures match. So, we are looking and ready to move quickly in that field.

Q: How do you see the valuation has developed with a lot of market activity – has that driven the target valuations up?

A: I think we see somewhat higher expectations in that sense that there is more activity and also more competition for some of the targets.

Q: How do you see the alternative uses for the cash and buying back your own shares?

A: If we are not successful with the M&A’s, there will be possibilities with share buybacks and dividends, but that is more up for the Board of Directors. In the management, we want to keep the money to have possibilities to make moves with it. From the management perspective, we also see that the bigger the company gets, the better possibilities it has succeeding also in the future. When buying bigger quantities of materials, the company gets better prices and payment terms, and it will be more competitive in the market. This is why the management sees that we should invest in the business and growing it through different ways: both organic growth, investing in the lines and latest technology, and inorganic growth. To be a sustainable business also ten years from now, it is key that the business is growing and staying competitive.
42 Likes

https://incapcorp.com/fi/osakkeenomistajat/

Fresh shareholder list. No striking changes. Twin engine and Joonas Korkiakoski have made small additions to their holdings.

7 Likes

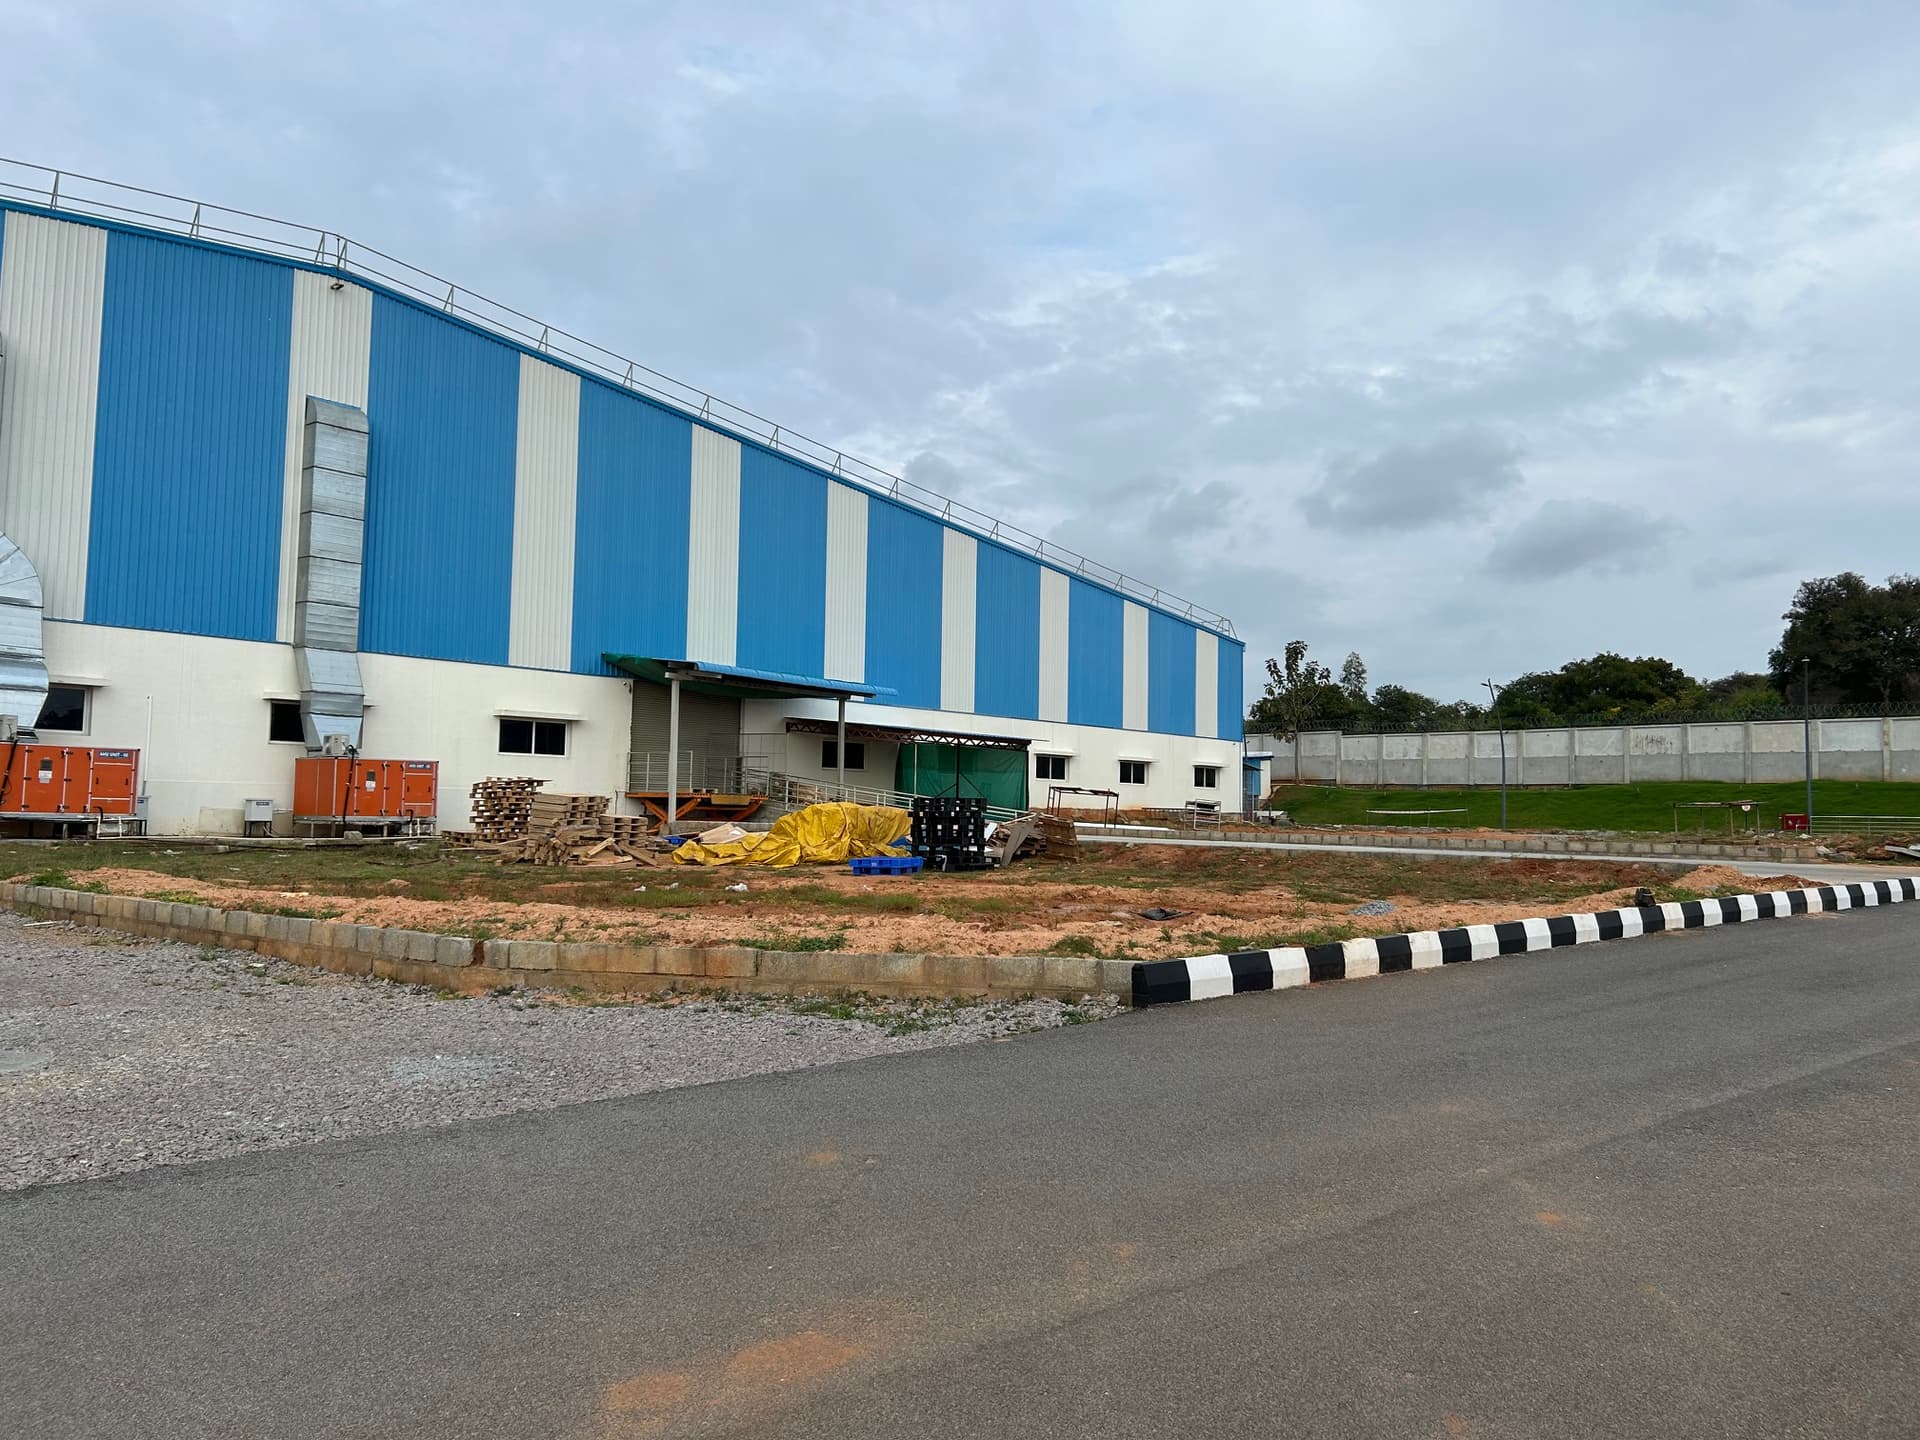
@Otto_Pukk invited me to visit ages ago, and today we finally toured and filmed with @Ville_Kivinen at Incap’s domestic factory and the older export factory in Tumkur. Tomorrow we’ll continue the tour at the newest (export) factory and interview Otto and the factory’s local management for a video.

If anyone has questions about Incap’s Indian factory, please post them in this thread or via DM, and I can inquire about the answers.

62 Likes

Otto is unlikely to answer this with anything but jargon, but he can try :slight_smile: :

With what kind of production mix would the Indian factory operate most optimally?

Why is Incap so profitable compared to other EMS manufacturers?

What kind of customer would be the most profitable specifically for the Indian factory?

Can Otto explain how the company decides which factory is used for the manufacturing of a customer’s products?

Do customers invest their own money in Incap’s factory, or does Incap operate solely on a “turnkey” basis? (One example of customer investments is, for instance, end-product testing systems, which are often the property of the customer companies but are operated by the EMS company’s employees.)

7 Likes

Thanks for the questions! The videos were just recorded, so unfortunately these didn’t make it in. However, let’s see what I can still find out (and if it remains unresolved, I’ll keep it in mind for the next quarterly video).

This has been touched upon many times in previous videos, so I believe the answer would emphasize a decentralized operating model and quick decision-making. Furthermore, my views on the question have been discussed in extensive reports.

Regarding this, I can answer without even asking: customers have invested in equipment specific to them, such as testing systems, as we were just discussing such equipment yesterday with Venkatesh, who is responsible for production and testing.

For a few other questions, I have strong hypotheses about the likely answers, but let’s not get ahead of ourselves now.

20 Likes

Here are Antti’s comments on the India factory visit. :slight_smile:

This week we visited Incap’s factories in Tumkur, India. Yesterday and today we familiarized ourselves with the production of all three factory units in Tumkur.

16 Likes

I couldn’t reach Otto anymore, but I discussed open questions with the local management in India. These are summaries of the answers, and I have not mixed my own views/interpretations into them:

Customers ordering the most demanding box build productions are the most interesting, because the service package for these types of customers is broader. Thus, more value can be created and also charged for. Fundamentally, customer relationships aiming for longer-term and more continuous cooperation are also more interesting than project deliveries.

In India, there are also some customers who, for example, want to manage material procurement and warehousing on their own behalf and only buy manufacturing work from a contract manufacturer. Incap does not take on these types of customers. Otherwise, Incap also analyzes potential new customers from the perspective of competitiveness and growth potential before starting cooperation, because the success of customers naturally affects the success of the contract manufacturer in the long run.

These are primarily customer decisions, as the contract manufacturer’s factory (incl. purchases, production, logistics) is integrated into the customer’s entire supply chain. Factories also do not automatically adapt to making each other’s products without changes, and for example, products from the Indian factory are not made in other Incap factories, at least under normal circumstances. Choices related to alternative delivery solutions are again customer decisions.

23 Likes

Alright then… Antti and @Otto_Pukk discussed Incap’s operations in India. :slight_smile:

Topics:

00:00 Introduction
00:47 History
02:56 Operating environment
04:16 US and India trade agreement
05:20 Distributed operating model
06:14 Investments
07:50 Developing markets
09:43 Investor misconceptions

16 Likes

Here are some more informal, scattered observations from my visit to India. The more official analyst comment (link here) was released last week, and the first of the videos has also been published (link above). We will release the rest in the coming days.

On the surface, the factory seemed somewhat similar to the European electronics factories I’ve had the chance to visit. Intuitively, there seemed to be somewhat more people in production, and the manufacturing of relatively simple product parts (such as cables, for example) was partly done manually, more so than in Europe. Also, at the tail end of the assembly phase, there were tasks that might already be handled by automation elsewhere, or at least will be in the foreseeable future, even though profitable automation for small and medium-sized box build production batches is not particularly easy. On the other hand, SMT lines were churning out circuit boards very similarly to more developed countries, and the product mix, like in Western factories, includes box build products requiring high expertise. The third factory, completed in 2023, is naturally modern in terms of technology, especially regarding its SMT lines. Overall, the technological capability seemed surprisingly good to a layman like me. Perhaps I, too, have overly assumed that Indian operations largely rely on low wage costs (Otto commented on this somewhat in the interview), although competitive personnel costs certainly don’t hurt profitability.

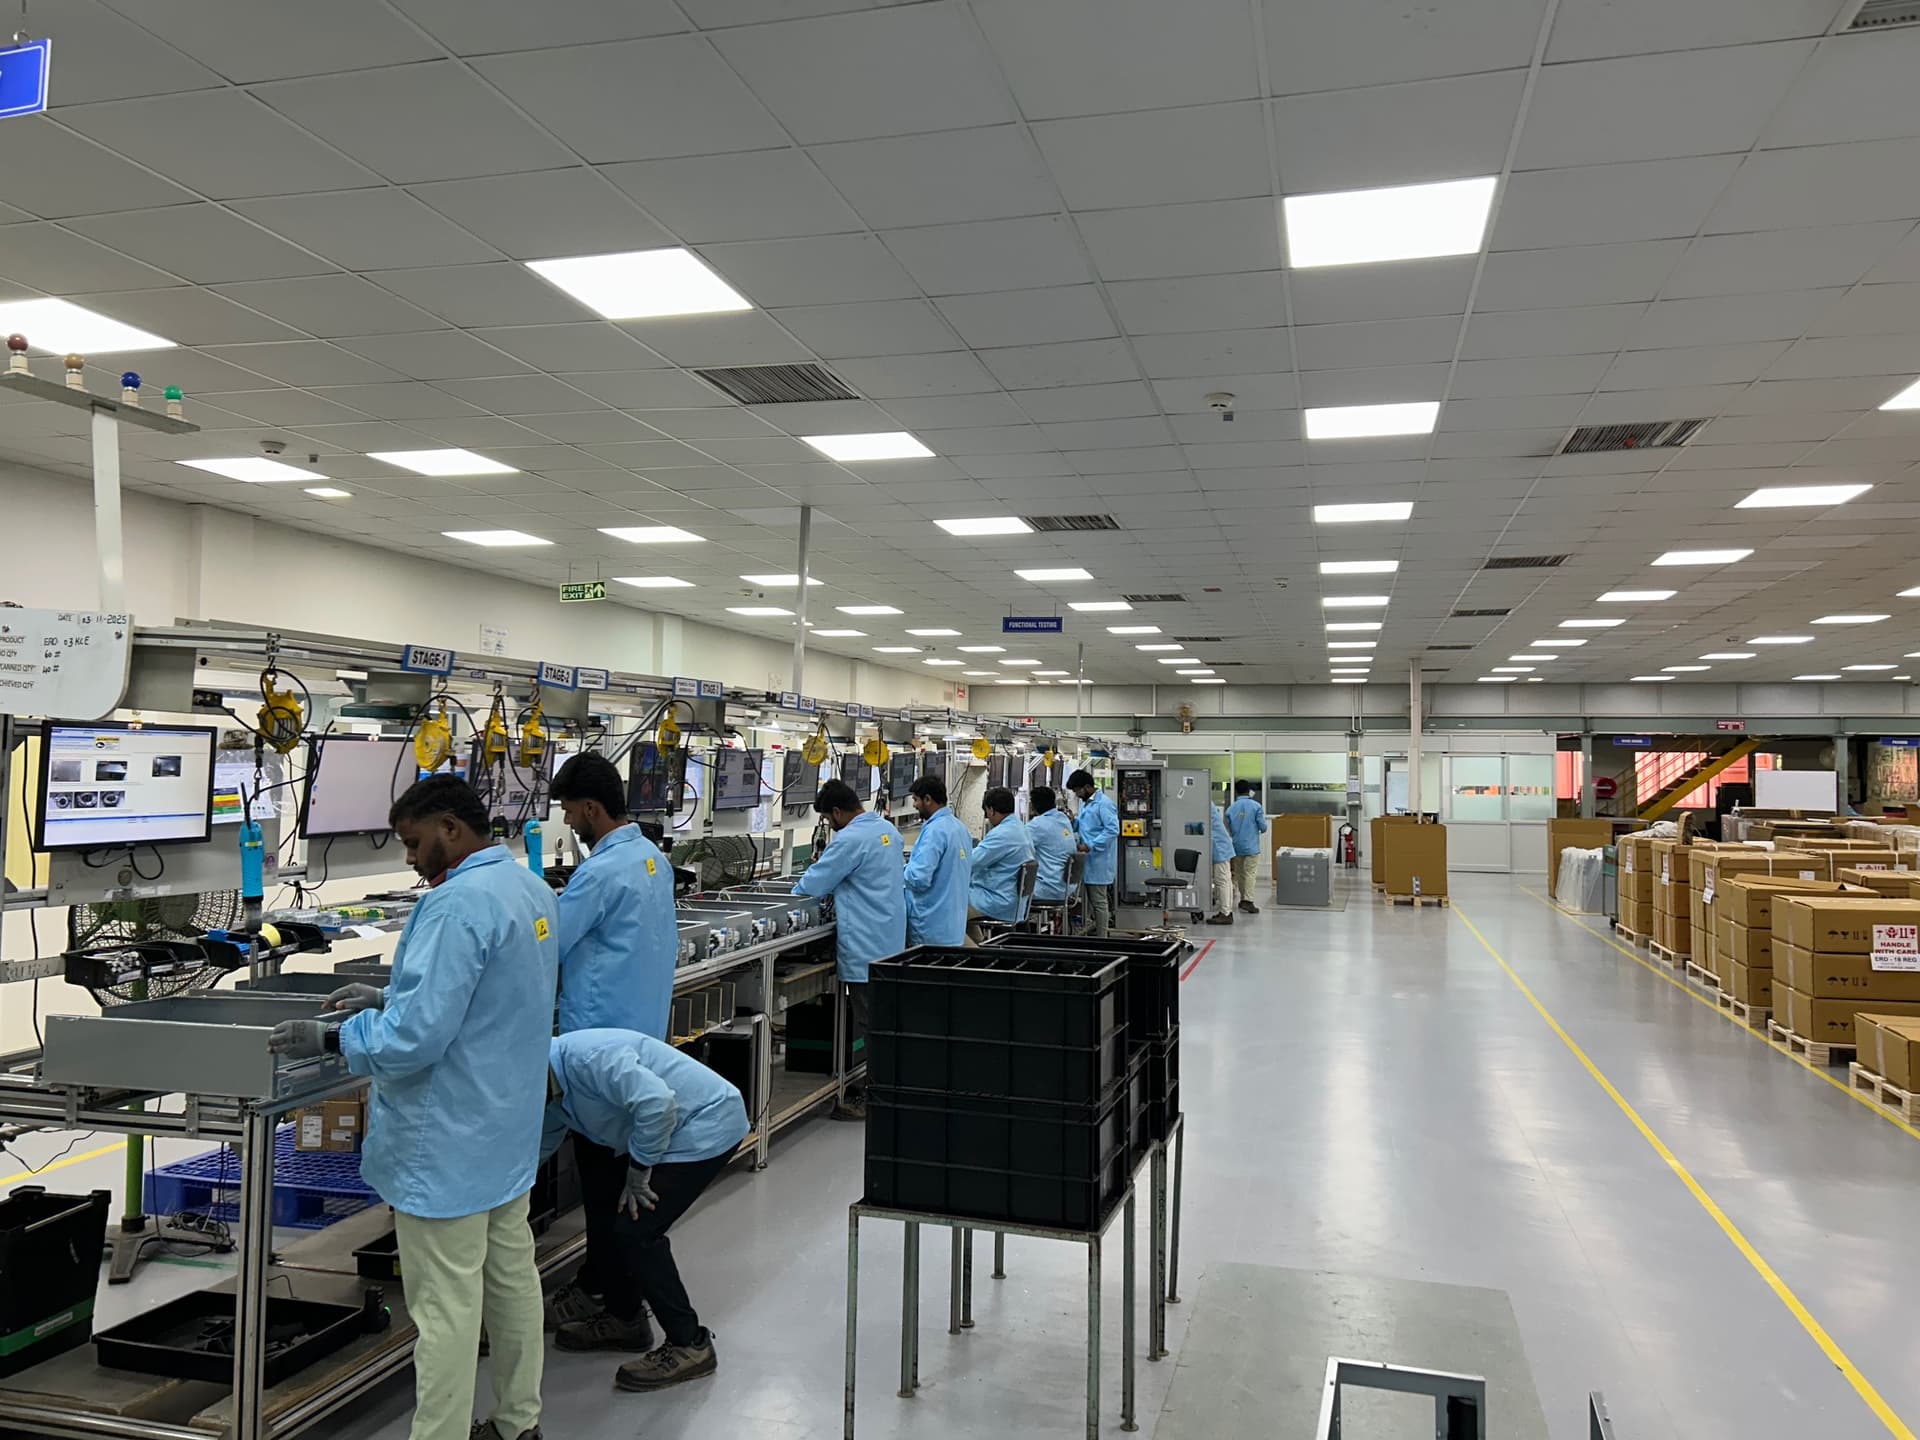
Testing work at the older export factory (No. 2)

The complex formed by the domestic factory and the older export factories seemed stretched to its limits, as the building has been expanded within the plot boundaries and also upwards, all the way to the third floor. In 2022, the old factory must also have been very cramped, as the largest customer’s volume at that time must have been significantly larger than it is now. Currently, all factories operate mainly in two 8-hour shifts, but three-shift operation is also possible if there were demand. This naturally provides flexibility in capacity (this must have been in use in 2022). The new third factory, of course, was clearly more spacious, and there is room for expansion both quickly (i.e., within the existing buildings) and with a slightly longer view (expanding the building). In addition, there is land for a fourth factory. Thus, it is possible to significantly expand the factory, but this would naturally require additional sales, especially to new customers. A relatively small local team was largely responsible for sales. As Otto mentioned in the interview, space was also earmarked for a new customer, so some sales successes have likely been achieved. It remains to be seen how and when these will start to appear in external reporting.

An additional wing for the third factory could be built here if new customer accounts take off

The ‘capacity potential’ of the third factory, likely to be put into use quite quickly

In India, a significant portion of the production staff is leased from a third party. Thus, personnel costs adjust quite quickly, as has been seen in practice during the demand fluctuations of the largest customer in recent years. Staffing agencies also move employees from one client to another (there are many other contract manufacturers in the Bangalore area), if work decreases at one. Therefore, losing a job is not necessarily a catastrophe for the employee either; on average, especially for those who had to leave Incap during 2023, work was found elsewhere. Some of these had also been enticed back after the inventory correction ended, which is important in itself, because in addition to basic industrial training, every employer has to train production workers for company-specific tasks. Thus, high turnover can also cause challenges, but overall the system seemed pleasantly flexible. Minimum wages in India are rising at a high single-digit or low double-digit pace year by year. The starting level is certainly low, but the rapid rate of increase naturally creates certain pressures for raising productivity (and pricing).

Engineers, on the other hand, were mostly on Incap’s payroll. Reportedly, a million engineers graduate in India each year. The level of engineering expertise was also praised, and engineers’ salaries are certainly reasonable. The good availability and high standard of skilled engineers (and certainly also low salaries) were also mentioned as root causes for why several international companies have recently established their product development units in the Bangalore area. Overall, the feeling was that developing countries are catching up fast (India is certainly not the only country of this type), and Western, or at least European, entities have work to do, considering their underlying structures, to succeed in global competition in the long run. This idea, of course, applies not only to Incap but more broadly to companies and the economy.

I also chatted with the local factory staff about the component situation. A significant portion of core components for products, in particular, come from China, which is likely still a very typical situation in the electronics industry more broadly. In this regard, the reins are in the customers’ hands, as product design is their responsibility, and contract manufacturers receive specifications from customers for product manufacturing. For core components, Incap follows the specifications to the letter. So, if the specification states that core component X is manufactured by producer Y, it is procured as such, even if producer Y’s only factory is in country Z. It also sounded like customers still had a considerable number of designs for one (Chinese) core component option, although no proportions were disclosed. I don’t know how easy it would be for customers to dismantle these dependencies, considering the prevailing techno-economic framework. However, China has large volumes for many products and the cost-efficiency enabled by them. The degrees of freedom for secondary components (e.g., plastic and metal parts) are wider, and Incap can propose alternative sourcing solutions to customers if available, if they reduce costs and/or shorten production lead times. Incap also increasingly sources these types of parts locally from the Bangalore area, where a subcontracting ecosystem (i.e., smaller local companies) serving the electronics industry has formed around it, somewhat similarly to some cases in Finland.

Traffic in India is, of course, a nightmare, but finished products were transported by road from Tumkur only to Bangalore, from where export products continued by train to Chennai and then by sea to the rest of the world. That sea leg also accounts for most of the delivery time. Regarding component logistics, I didn’t remember to ask how the stretch from the port to the factory is handled, but considering the typical 10-20 week delivery times for components, this is unlikely to be particularly significant. Correspondingly, the production lead time and the time taken for final product delivery are significantly shorter than this. Therefore, the majority of Incap’s (and other contract manufacturers’) inventory is tied up in components, and the clearest potential for improvement in terms of working capital efficiency would be in that area. Inventory efficiency was naturally the responsibility of local management, but given the starting points, significant and rapid improvements are unlikely to be achieved, and the focus was more on continuous improvement of operations in this regard as well.

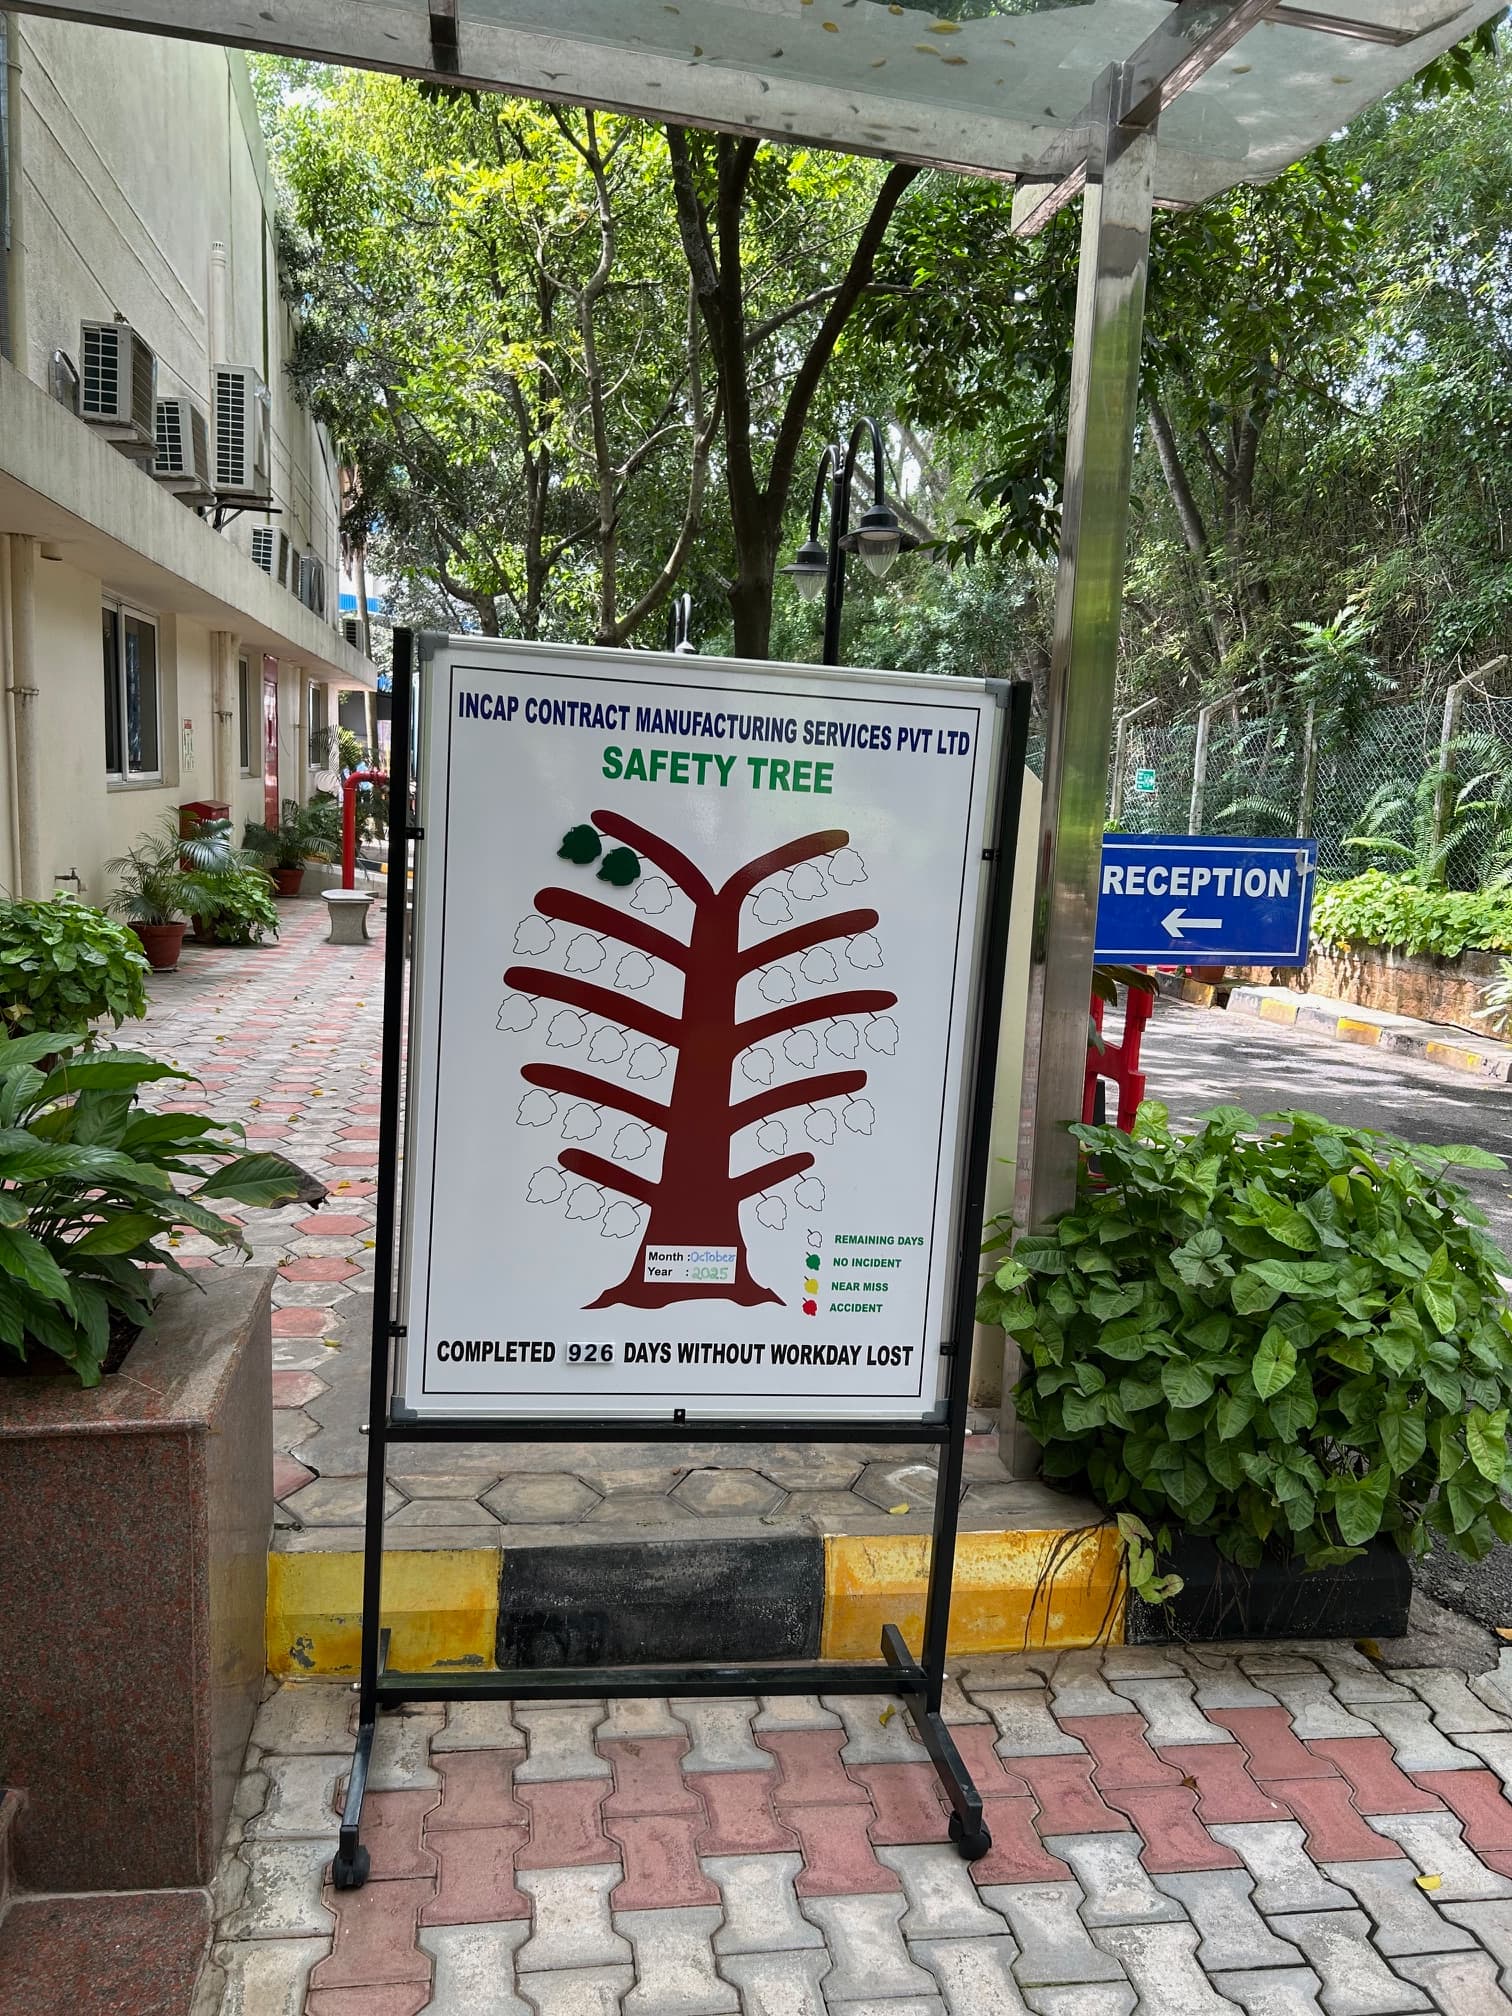
Over 900 days without an accident is a very good figure in industry, even in international comparisons, where safety statistics are generally considered one measure of process quality.

51 Likes

A short comment on the salaries of Indian engineers. I have several former colleagues (Indian) working as specialists in Finnish industrial listed companies. According to them, salaries in India have developed so rapidly in recent years that they would now receive almost the same salary in India as Finnish companies pay them. Their current salaries in Finland are between 4.5k€/month and 5.5k€/month.

Of course, the sample size is small, and the industries are different from Incap’s. I also believe that they are more capable than the average engineer.

Thanks to my background, I have a good understanding of engineer salary levels in several countries. I argue that Finland is relatively cost-effective in terms of salary levels, considering the engineers’ expertise. In this assertion, I am not taking a stance on the various employer-side costs that companies operating in Finland incur in addition to just the salary.

28 Likes

Inderes Model Portfolio added a slice of Incap. :backhand_index_pointing_down:

Today, we allocated approximately 2 percentage points from the Model Portfolio’s cash weighting to Incap, which increased the stock’s weight in the portfolio to just over 7%. We opened a position in Incap about a year ago, after which the trade war and currency headwinds have slowed the company’s short-term development compared to our expectations at the time. We still believe the company will achieve solid earnings growth in the coming years, which, combined with a low valuation, offers an attractive return expectation. The company’s strong balance sheet also enables value creation on the M&A front, where the company already has a proven track record. After the transaction, the Model Portfolio’s cash weighting is just under 17%, thus leaving ample room for new moves.

25 Likes