I have been wondering out of curiosity what Ilkka’s share price would be if the company distributed its Alma shares and only its own business remained. Right now, the market considers the value of its proprietary digital business to be heavily negative, which in itself is an achievement when even the most wretched IT consultants on the Helsinki Stock Exchange are worth tens of millions.
This mismatch shows that investors believe Ilkka destroys everything it touches. In acquisitions, the money has indeed been burning a hole in the pocket, and then they’ve gone on a digital-hype buying spree acquiring everything that sounds nice. The sellers have trimmed their companies’ financial metrics for sale and extracted a hefty price from a foolish buyer. Under the new owner, the positive development of these digital kiosks has stopped. Now, over €60M has been burned on businesses that yield nothing for the shareholders.
CEOs and boards have been fired for less. At Ilkka, everyone seems to have a comfortable sinecure.
Roni has published a new company report on Ilkka following their recent acquisition :)\n\n> With Ilkka’s acquisition of marketing technology company Custobar, the company has a strong historical track record of scalable growth, and we believe it fits well into Ilkka’s business portfolio. However, we consider the valuation of the transaction to be tight, and therefore we remain initially cautious about the deal.\n\nIlkka: Uusi kokonaistarjoomaa kasvattava palanen - Inderes
Hmm, Alma Media’s future is seen as reasonably good. But would it be better to buy Ilkka and get some other business operations at the same time? Right now, it seems the market is pricing Ilkka in such a way that the actual business operations are eating up Ilkka’s Alma and other assets?
That is what I thought too when the share classes were combined. But the challenge has been that administration and poorly profitable other operations eat up the earnings themselves… Alma’s assets and dividend are still significant, but everything else would need streamlining and more results-oriented management from the executive team and the board than what the past track record/implementation shows.
Still, dividends can probably be expected for quite a long time thanks to the Alma holdings, right? Another thing is that surely the owners (the board) won’t watch that kind of performance for very long.
If I calculated correctly, Ilkka has about €120 million in Alma holdings and a €103 million market cap. So it’s trading pretty much like a holding company? The core business has practically a negative valuation.
I agree regarding Alma. In Ilkka’s case, I believed this to be the way things were as well, but based on the evidence seen now, I am no longer so sure when Ilkka minus Alma will start to be managed the way a listed company should be managed.
It’s quite odd that pension companies and a life insurance company are among the owners there, and you’d think they would have some interest in at least making the business profitable too. But yeah, let’s buy a little bit of this. Probably won’t fall from very high. Though of course, their success isn’t written in stone either.
I was thinking the same thing a few years ago. Then I browsed the depths of the internet a bit and realized that the same thing had been preached for years without results. This is already a couple of years ago now, and nothing seems to have changed. After the latest acquisition, I wouldn’t touch Ilkka with a ten-foot pole anymore. Management is squandering owners’ money and engaging in so-called “empire building,” eating up Alma’s dividend income.
The day Ilkka distributes Alma’s shares to its owners would certainly be positive for the stock, but you are paying for every day that passes. In the end, you’ll find that a decade or two has already passed…
You also wondered why Ilkka doesn’t actually consider the owners’ best interests. The answer to this can be found in the board of directors and the SUPERVISORY BOARD (yes, Ilkka still lives in the era of casino economy, maintaining a two-tier bureaucracy). The answer is also found in the pride of Ostrobothnia and its owners toward the company.
The problem with the reforms, alongside the previous separate share classes, has been the voting power cap (äänivaltaleikkuri), which prevents major owners from exercising their voting power. It limits the voting power of an individual representative present at the general meeting to 5 percent (1/20) of all the votes represented at the meeting.
Keskisuomalainen has previously proposed reforms to Ilkka’s governance structure, but in the past, they were largely blocked due to these factors. Now, based on a single unified share class, such reform appears more probable.
Olli Pirhonen
CEO of Ilkka Oyj starting March 14, 2017 Previously served as:
CFO and Board Secretary of Ilkka Oyj 2014-2017 and Deputy CEO 2015-2017
So you’d think, but in practice, the exact same CEO has been in the house for ten years, and Alma’s dividends are being tossed here and there into various trash piles where you can see all the way to the moon that they are being overpaid for, and that any kind of sensible return on capital is just a pipe dream for the acquisition targets.
As for the interests of pension insurance companies, they are extremely passive and won’t raise a peep about anything unless the company is practically committing genocide; otherwise, companies can mess around however they please, especially since this joint is such a tiny grain of sand in any single pension company’s portfolio.
Ilkka looked cheap on a sum-of-the-parts basis five years ago when I had it in my own portfolio too, and it probably looked that way ten years ago as well. However, there is no prospect that the value will ever be unlocked for anyone other than the sellers of the acquisition targets, and when you hear once again how this deal too was approached with a “must buy something” mentality, it shows in the price once again.
If this were to be made a serious investment target, the first thing to change would be a CEO who has the slightest grasp of capital allocation, and along with that, the board.
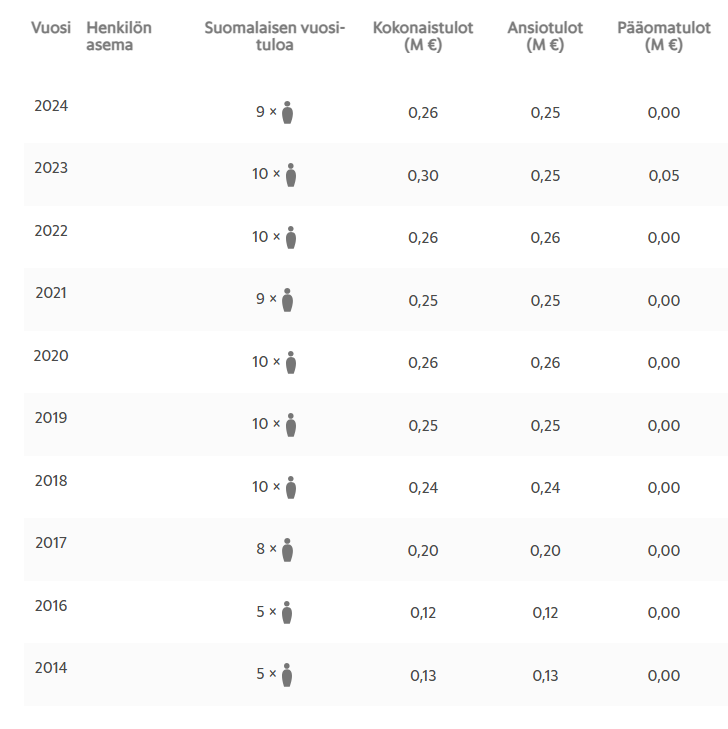
It also tells a lot that Olli doesn’t even believe in Ilkka himself as an investment target, given that his capital income is zero year after year, even though the joint is notoriously known for paying DIVIDENDS.
Pirhonen has been with the company for almost 10 years, and the stock’s return over that period is +85% without dividend reinvestments. Not great, not terrible.
Aha, I wouldn’t have guessed that a new tech company would appear in my equity savings account (OST) right when I dumped one just yesterday. Well, I suppose I can have a couple of these in my portfolio.
Tässä on Ronilta kommentit, kun Ilkka on nimittänyt Immo Salosen konserniin kuuluvien tytäryhtiöiden Lianan ja Profinderin uudeksi toimitusjohtajaksi marraskuun alusta alkaen
They might as well have let Pirhonen retire from his role as the group’s CEO.
Pirhonen’s track record of burning money on digital kiosks has been proven, and a somewhat cheaper man could just as well go to Alma & Kaleva’s annual general meetings to drink coffee.