Another quarter is behind us, and delivering the results was left dependent on external parties. Alma’s dividends, the sale of Arena Partners, the newspaper business under Kaleva’s wing…
One would hope that after all the money poured into acquisitions like Liana Technologies and Profinder, there would be some cash left over. It seems their operating profits are shrinking in Ilkka’s hands, and Ilkka’s management is dragging their own business into the red as well.
I completely agree. How much longer will this behavior and making of excuses be overlooked? Weren’t people from Ostrobothnia supposed to be honest and proactive..? The company definitely needs a swift shake-up in its management and board of directors.
They should sell off the non-core assets, distribute Alma (shares) as dividends, and then let whoever owns the remaining business make that part profitable.
As a comment on that Otava point, Otava has acquired shares of Alma Media before, triggering a mandatory takeover bid. Back then, there was practically no premium in the offer at all.
That is true, but at that time there really was no premium; the price was 9.10 euros, and Otava was likely aware that the major shareholders were not selling.
The last time Otava bought [shares] was early in the year at 14.52 euros and in the summer at 13.70 euros. Buying the entire stake now would be significantly more expensive, and many owners might seize the opportunity.
To buy the entire remaining stake in Alma Media, for example at a purchase price of 15 euros, they would need over 700 million euros, and the Otava Group does not have that kind of money, even though it is a solvent company.
Otava’s previous purchases were actually at the 9.1€ price point.
At the time of the last buyout offer, Otava would have been able to pay up to 50% with its cash reserves, and debt financing from major Finnish banks had been negotiated for the remaining amount, meaning they had around 150 million in cash available back then. Since then, Otava has likely made another 100 million euros, and even though Alma Media’s share price has risen—and thus the acquisition price required for the entire company has increased—Alma’s profitability has also improved, and I believe debt financing is still very much possible at, for example, a share price of 15€.
I watched Pirhonen’s interview. Wow, so tiresome. The same mantra about building one’s own business as before. His belief in his speech is strong, even though there are no signs of growth, let alone profits. More of the shareholders’ money should be shoveled into the pyre. Ilkka’s board and major shareholders are incomprehensibly patient.
South Ostrobothnia is the cradle of entrepreneurship in Finland. In my opinion, there is nothing strange about this activity. If you compare it to the development of VLP (now Loihde) back in the day, stakes and investments were definitely made in good faith for a long time. About a couple of decades ago, VLP shares were trading at almost 2,000 EUR. Today, as Loihde, it is worth 1,235 EUR (1 VLP = 100 Loihde shares). Of course, dividends—and quite a few of them—have been paid along the way. I personally see a somewhat similar development with Ilkka. It’s difficult to get all three “legs” (i.e., Alma, Kaleva, and their own operations) to be profitable at the same time.
Southern Ostrobothnia is the cradle of entrepreneurship in Finland. In my opinion, there is nothing unusual about these operations. If you compare it to the development of VLP (now Loihde) back in the day, stakes and investments were certainly made in good faith for a long time. About a couple of decades ago, VLP shares were trading at nearly 2000 EUR. Today, as Loihde, it is worth 1235 EUR (1 VLP = 100 Loihde shares). Of course, dividends—and quite a few of them—have been paid along the way. Personally, I see a somewhat similar development with Ilkka. It is difficult to get all three “legs” (i.e., Alma, Kaleva, and its own operations) to be profitable at the same time.
I am not familiar with the history of VLP/Loihde, but in light of the figures you presented, I don’t think it has been a real success story. Investments should yield more than the cost of the money used for them.
The starting point for Ilkka’s current business was at ground zero (albeit with pockets full of cash), from which it has been built up through acquisitions. There is no problem with that in itself. However, the track record of the acquisitions made is extremely poor. The digital kiosks acquired were quite pricey, and at least on paper, previously profitable businesses have turned loss-making under Ilkka’s ownership. The expected organic growth has also not materialized. The reason might be the unfortunate economic cycle, but Ilkka’s tendency to blame the geopolitical situation is just fairy-tale storytelling.
I consider myself quite patient, and that is precisely why I would like some signal of success regarding the chosen strategy before I start running full speed into a wall. It is possible that Ilkka’s management sees such a sign but is keeping it a secret. Given this evidence, the acceleration of investments scares me.
Roni has written a company report on Ilkka following Q2
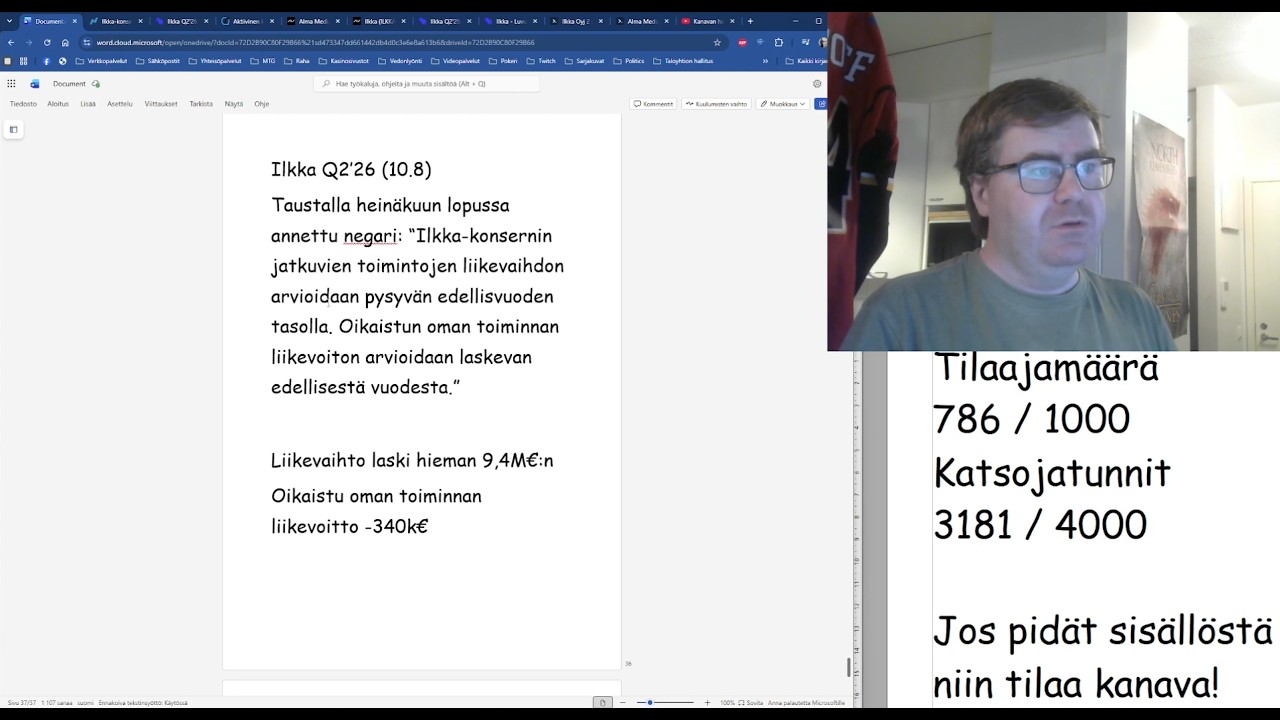
Ilkka’s own business performance in Q2 fell short of our forecasts, which had already been revised following their profit warning. The weak performance was offset by the company’s other holdings, which performed better (Alma Media, Kaleva Media, and the investment portfolio). With minor adjustments moving in different directions, our sum-of-the-parts valuation remains largely unchanged. We reiterate our target price of 4.0 euros and our “reduce” recommendation.
In my opinion, this expertise or its level is a bit of a double-edged sword. Ilkka has generally made good moves when it comes to larger companies that have been somewhat close to its own old core business. Of course, these small software and marketing companies have always been a bit difficult for me to understand as well. That Profinder could be quite excellent, but apparently, even that is no longer growing (?).
Ilkka was, at one time, the largest shareholder in VLP/Anvia/Viria/Loiste (might have been 5%). However, it sold its stake to Elisa in 2014, and if I recall correctly, at a good price. It had also managed to enjoy good dividends for quite a long time before the sale.
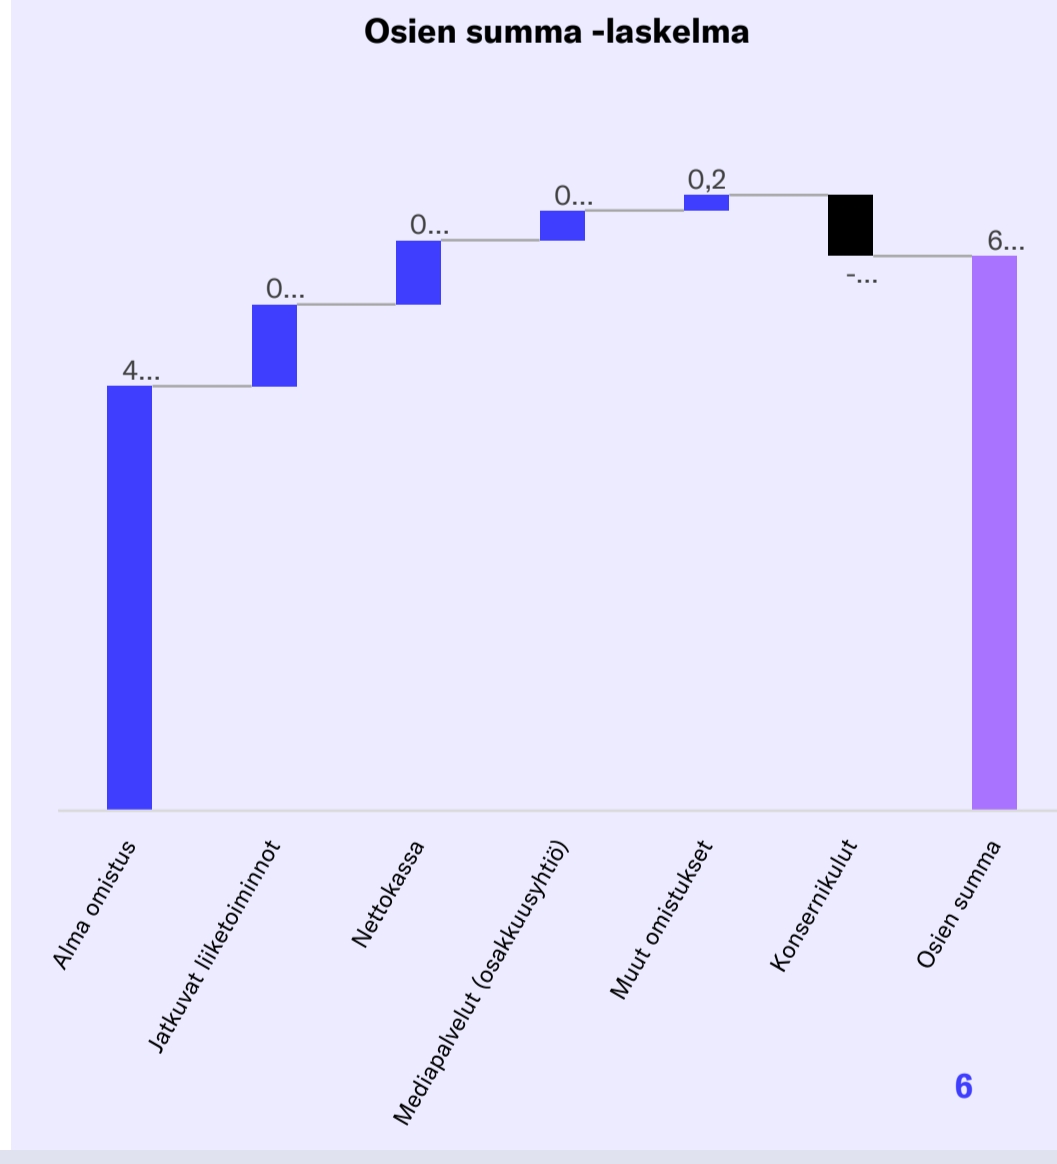
Sum of assets 6.0 EUR, of which Alma Media shares are worth 4.6 EUR.
If you look at that very roughly and critically, the value of the core business is nullified by group costs. The earnings from internal operations are consumed by group administration.
In that case, the company’s value consists of its holdings, i.e., Alma Media shares, net cash, the stake in Kaleva365 Oy (35%), and other holdings like Arena Partners Oy (minority stake 45%).
Positive:
-They have managed to move newspaper and printing operations into care / arrangements that generate money in a declining industry.
-Alma has been held. It would be time to distribute it to Ilkka’s owners for safekeeping now that it has risen well.
Super negative:
-Nothing really develops from the businesses kept in their own hands, just losses.
-The operating profit from their own businesses is consumed by administration.
The voting power issue is fortunately resolved; I can IMAGINE that it was done to make it possible to distribute Alma’s shares to owners, at least to a large extent, 75% or similar.
Or perhaps Alma’s major shareholder wants to make a strategic move.
I will try to be a bit positive again, even though my primary thought would be about changing the title: Ilkka – wallet emptied, fortunately there’s Alma.
The acquired Custobar has at least managed to grow further in H1, and its result has grown as well. The EV/EBITDA of the acquisition based on the “forecast” after H1 (H2 = H1) is approx. 15, and with the same forecast, growth would be around 20% on an annual basis.
EBITDA of approx. €0.8M would be 12.5%, but presumably this percentage should increase more as the headcount remains roughly the same and revenue grows.
Last year, the improvement in EBITDA and profit (EBITDA from 5.7% → 11.5% and profit from €55k → €388k) seems to have come largely through headcount reductions (26 → 19), despite the growth.
If that kind of +20% growth with an improving EBITDA margin were to continue in the future, the purchase would be quite good indeed.
Now I just doubt that the growth will continue like this, and I’m also a bit worried about how significant the key person risk might be. On the technical side of Custobar, there appears to be one founder and six employees. The founder just sold their entire stake, and apparently the whole payout was in cash. Will they be motivated to work flat out for this joint starting next Monday?
Let’s wait and wonder, and collect dividends, since I just raised my average price with small purchases at 3.8xE. Let’s enjoy the story.
Looks like typical M&A activity for Ilkka. In my calculations, 12 million euros turned into zero. A common thread among all of Ilkka’s digital kiosk acquisitions is that the target company’s profitability is weak, growth stalls after the deal, and they overpay relative to the aforementioned factors.
Let’s wait and see if history repeats itself with Custobar. Congratulations to Custobar’s owners, you certainly made an excellent deal!
I agree. How long will the company’s board and major owners bless this kind of amateurish tinkering? And at what point will results start to be demanded, like in normal listed companies? Hopefully, I’m just being too critical and the company’s management will prove our concerns wrong. Recent track records just don’t support this.
Luckily I didn’t succumb to buying any more Ilkka, even though the sum-of-the-parts calculation looked really attractive. Exactly the same outcome in my books, €12M just vanished into thin air, meaning close to €0.50 per share. Are they buying these shacks from their buddies?
Watching this tinkering from the sidelines is pretty awful. The media operations have been outsourced/sold, and now a bunch of amateurs are sitting on top of the money bag playing corporate executives. If only they would realize they should just liquidate all assets and distribute the money to the shareholders, while there is still something left of the capital accumulated over the century.
There goes the rest of the net cash, it seems. Soon we can change the thread title to “money squandered and core business is still struggling”.
Sure is painful to watch as a shareholder. Of course, one has hoped that the acquired operations would start turning a profit, but they’ve only brought pain and losses (tu(r)skaa). Bought at completely absurd valuations without any bigger plan, just with the mindset that we just have to digitalize.