Joni has written a comprehensive report on Gofore, and naturally, this extensive report is also available for everyone to read. 
Gofore’s track record of profitable growth in the public sector is undeniable. However, over the past couple of years, operations in the private sector’s growth areas have sputtered due to a challenging market. Now, the company has made two acquisitions to strengthen its offering in growth areas, and the outlook for weaker market segments has improved. The company’s focus is now on returning to a better organic growth trajectory, which will also make profitability management easier. We expect the company to continue growing faster and more profitably than the sector during the strategy period, but to fall slightly short of its own targets. From several perspectives, the valuation picture is very attractive.
Excerpt from the report:
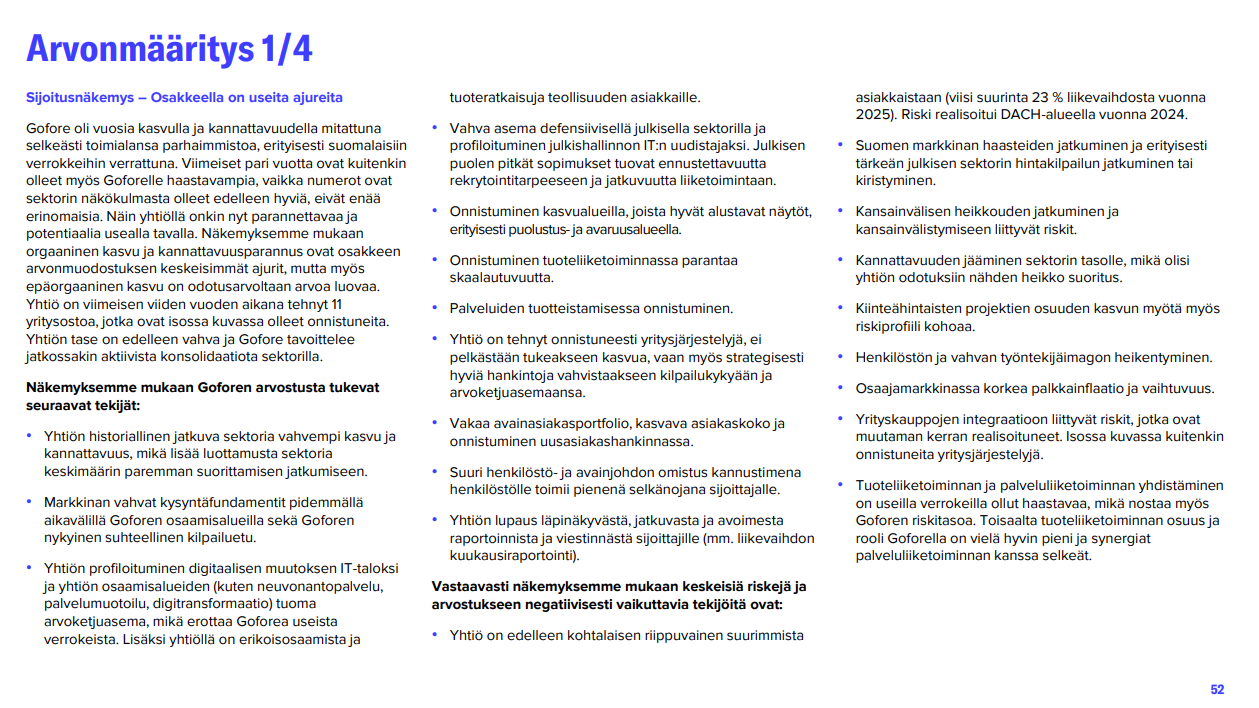
For years, Gofore was clearly among the best in its industry in terms of growth and profitability, especially compared to its Finnish peers. However, the past couple of years have been more challenging for Gofore as well; while the numbers have still been good from a sector perspective, they are no longer excellent. Thus, the company now has room for improvement and potential in several ways. In our view, organic growth and profitability improvement are the key drivers of the share’s value creation, but inorganic growth is also expected to be value-accretive. Over the past five years, the company has made 11 acquisitions, which in the big picture have been successful. The company’s balance sheet remains strong, and Gofore aims to continue active consolidation in the sector.