NOVO NORDISK
Novo is Denmark’s Nokia, but with the difference that Novo has better prerequisites to continue its brilliant performance and thus avoid Nokia’s miserable fate. I’ll keep the message fairly short so that everyone can manage to read it.
Novo is a pharmaceutical company founded in 1923, specializing especially in diabetes. As a doctor, this field is very close to my own area of expertise. From a pharmaceutical company’s perspective, diabetes is very attractive because, although the etiology of diabetes varies significantly, we can generalize that it is primarily a lifestyle disease. Specifically, as people globally live more “affluent” lives, diabetes becomes more common as a disease. TAM (Total Addressable Market) is therefore growing, and thanks to its long history and scale, Novo has clear competitive advantages specifically in the treatment portfolio for this disease. The pharmaceutical industry is a high-barrier business, as it requires significant capital for R&D and is also heavily regulated in all market regions.
Novo’s focus has been quite purely on diabetes treatment, but now also on the treatment of obesity, which is on everyone’s lips. In fact, these topics are essentially linked, as the effective “weight loss drugs” spoken of today were primarily developed as diabetes medications. It’s logical that the solution for weight management was found this way because, as I described at the beginning, the relationship between diabetes and obesity is close.
Novo’s sales breakdown shows quite clearly where the money comes from:
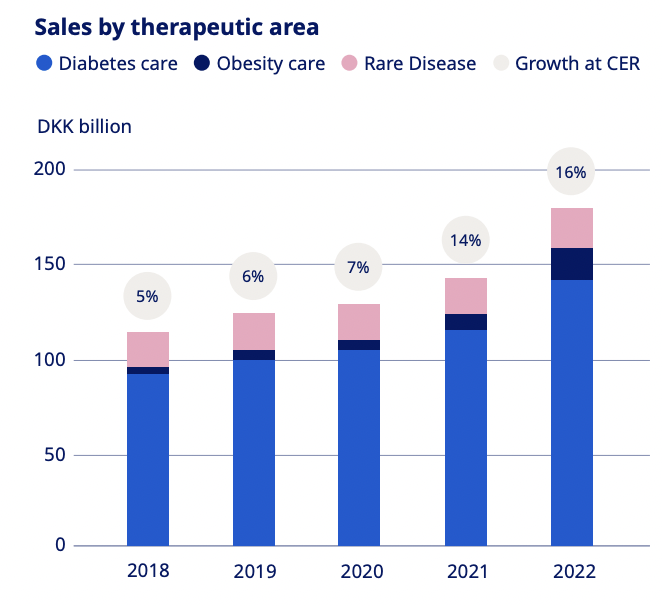
You can clearly see this focus in Novo’s pipeline:
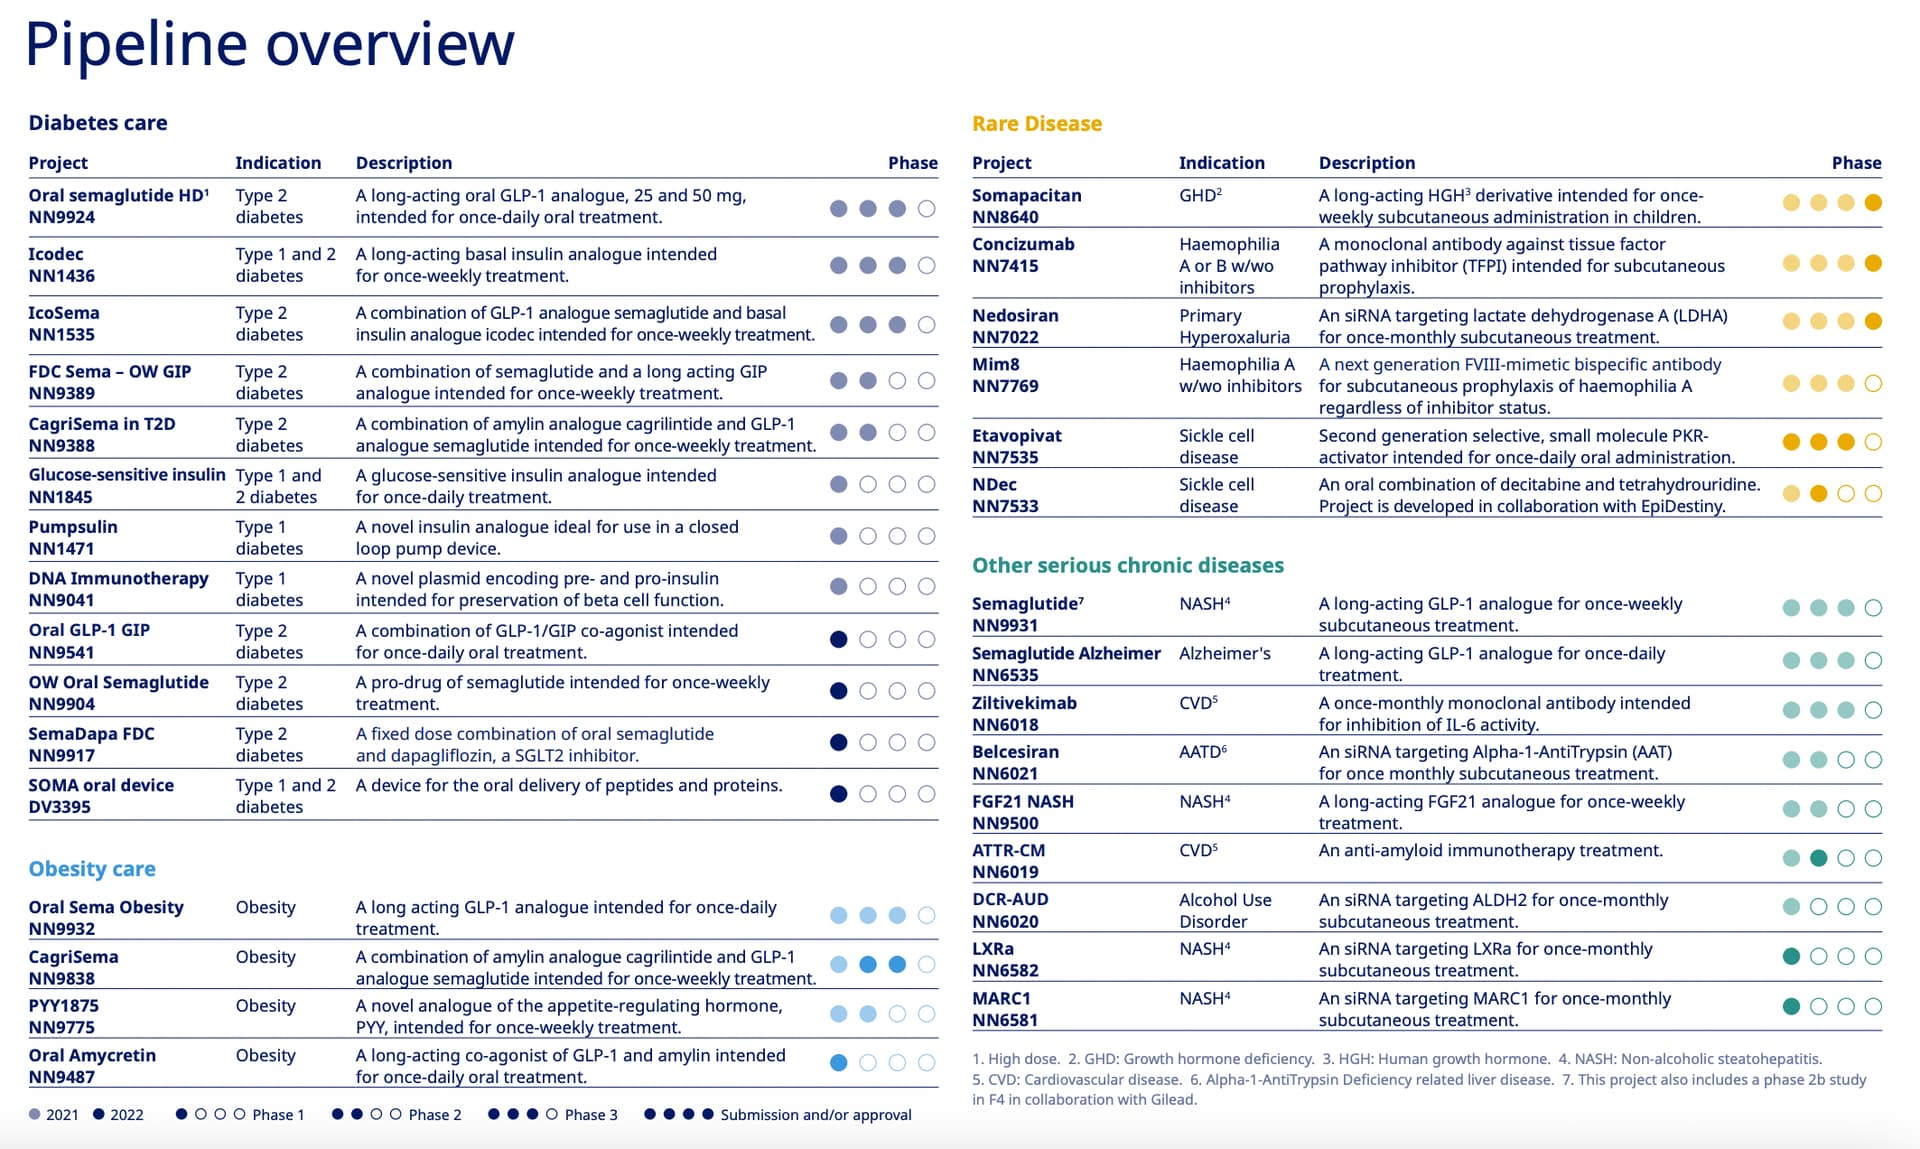
From this, we can clearly see that the strongest growth is now driven by obesity drugs, either with this indication or through “off-label” use.
Novo meets all the criteria of a high-quality company based on historical key figures:
- ROIC has varied greatly, but the > 15% criterion has been easily met.
- Revenue growth 2010 - H1/2023 is around 8.5% p.a.
- Net profit growth 2010 - H1/2023 is around 13% p.a.
- Net profit margin is > 30%
And we have every reason to believe that this will continue, briefly some points:
- High barriers to entry (regulation, capital needs, requires specific expertise in drug development, etc.)
- TAM keeps growing regarding diabetes
- Medical treatment of obesity is only in its infancy in terms of sales volumes
The most significant threat relates to this medical treatment of obesity. As seen from the valuation multiples, the market is pricing in significant profitable growth through obesity treatments. And it is arguably quite clear that in the coming years (e.g., 2024-2028), the company will almost certainly grow nicely in terms of both revenue and earnings.
However, there is also a risk here. While this thread is not meant for a detailed valuation discussion, it is good to understand that Novo’s market value relies heavily on the narrative of the triumph of obesity drugs. However, in the long run, there is a valid and significant threat that a clearly more effective medical treatment will be invented, displacing the current GLP-1 analogs. It could be, for example, completely outside Novo’s area of expertise, or a competitor’s products might simply be better. This change in narrative would be devastating for valuation multiples, as expertise in diabetes treatment alone would not justify anywhere near the current multiples.
@Santeri_Korpinen, I’m very interested in Sifter’s view on the following: Novo’s product for obesity treatment is semaglutide, which is purely a GLP-1 analog. Unfortunately, there is no significant improvement in sight in the pipeline (see image above). But if we look at the pipeline of the main competitor, Eli Lilly, it looks completely different. Tirzepatide has just entered the market, which is a dual agonist and, based on good evidence, is a MORE EFFECTIVE weight loss drug than semaglutide alone (at least among those with diabetes). Furthermore, Lilly has retatrutide in its development pipeline, which is a triple agonist, and its preliminary evidence is much better, even close to the efficacy of bariatric surgery. Of course, it will take years for this to reach the marketing stage, but Eli Lilly is certainly much better positioned specifically in the medical treatment of obesity.
How have you at Sifter approached this dilemma? Novo’s growth path even in the medium term is likely on track because the demand for medical treatment of obesity is so amazingly high that Novo’s products will still sell like hotcakes even though tirzepatide has already entered the market. But as an investor, you surely consider this current valuation and its sensitivity to a change in narrative. In the short and medium term, I don’t see very large threats to Novo’s business performance, but in the long term, they exist, specifically in this obesity segment. And unfortunately, at these valuation levels, that pretty much defines the success of a long-term investment.