Here’s one perspective on potential winners. I would personally also add Wärtsilä to the list.
7 Likes
There has been high-quality, fact-based discussion regarding Fortum’s stock valuation over the past few days.
It has become quite clear that one could easily justify a lower share price than the current one. For example, the P/E ratio is high compared to its history; the investment and growth outlook, including the construction of new nuclear power, is unclear; and while Fortum’s hydropower plants alone are massive value assets, selling them might be more of a theoretical possibility; the right of first refusal for Uniper’s Swedish hydro and nuclear assets is unlikely to materialize, etc.
On the other hand, it’s easy to see justifications for the current or even a significantly higher share price. The value of the hydropower assets alone is well over €20/share; even if Fortum doesn’t sell these crown jewels, as top-tier value infrastructure they provide shareholders with peace of mind. There are also interesting prospects and value drivers in the AI and clean green transitions—electricity is the oil of the future economy, etc.
My own view on how the winners will emerge in this struggle between bulls and bears:
-
Over time. By the end of this decade, we will see whether the AI and transition prospects materialize. This won’t happen by the next interim report or even within this year.
-
As decided by Mr. Market. If those transitions fizzle out in the coming years, he will slap a “laggard” (mörnijä) label on the company, and the share price will stagnate around €15-20. If these drivers accelerate with Fortum on board, the journey upward will continue.
Supplement: Last year was tough for Fortum, but Q1/2026 seems to be soothing the wounds. In the company’s other main market, Sweden, electricity prices at the start of the year have been 37–300% higher than last year.
6 Likes
It is, of course, always good to remember that electricity is mostly sold forward at fixed prices, and this is at a slightly lower level than last year. Granted, hydro and nuclear power can now be optimized to some extent for more favorable prices.
Interestingly, it’s worth noting that while the current year’s 42-euro hedging prices are mostly hedged at 41 EUR/MWh for this year, the 2027 hedges drop more sharply to the 39-euro level. The market does not seem to believe in a very rapid turnaround.
6 Likes
A new consensus was found fresh off the press from Vara’s website. I’ve plugged the figures into my table as usual.
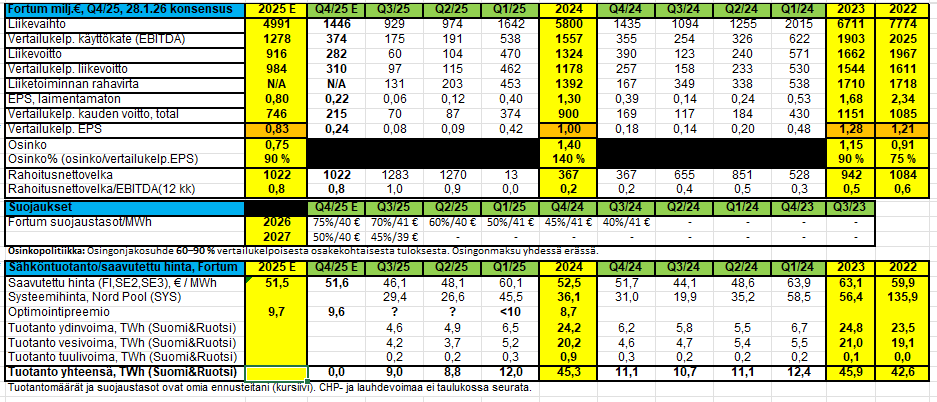
There is nothing surprising here for those following the stock. The share price reaction is unlikely to be significant in either direction.
Finns have been selling Fortum and foreigners have been buying. It’s great that Fortum is now classified as an AI stock.
35 Likes
I would need a video explanation on how to read that image. I’m currently missing a lot of information.
2 Likes
Dividend with a lightened model this spring, but otherwise this doesn’t look bad at all 
”In our opinion, the most essential thing for the investment case is that the price of electricity has turned upwards in Finland, especially in the 2026 futures. We have not made significant changes to our forecasts in connection with the earnings preview, but the rise in electricity prices creates upward pressure on the forecasts for the coming years”
12 Likes
Fortum is facilitating a data center in Rauma. The operator will be announced in late winter at the earliest (negotiations are ongoing). Initially, consumption will be 50 MW, and it could rise up to a maximum of 1000 MW.
13 Likes
With a strong balance sheet and low investments, combined with the main owner’s chronic shortage of cash, we could see a dividend bomb this spring as well. Not much else to it. Let’s keep our bags open and let the money flow in!
17 Likes
Yeah, it’ll likely pay generous dividends. In addition to its own dividends, the state receives tax revenue from the dividends of other shareholders too. That’s the reason why the majority owner doesn’t even consider share buybacks.
17 Likes
Check there to see who has been snapping up the shares. It seems foreign investors are the ones accumulating them.
10 Likes
I’m not particularly interested in the full-year results being announced tomorrow. I believe the results will be in line with expectations.
My main interest lies in how the media and the public will whine and complain about the “unreasonable exploitation by a major state-owned company,” as the results are released on the same day that spot electricity prices are at their highest in a long time. You can also be absolutely sure that politicians won’t miss the chance to score some easy points tomorrow.
If only Fortum’s board would also propose the same kind of stock option plan tomorrow that caused such an uproar 20 years ago, we’d have entertainment for the rest of the week.
14 Likes
The power charge limit rose from 5 kW to 8 kW. If the dividend is actually 75 or 80 cents and the earnings don’t significantly exceed that, then the stock will drop. Interesting times again. The power charge is pure greed.
14 Likes
One shouldn’t forget Fortum’s power plants in Russia that were left there for free. It’s unlikely we’ll get anything back for them.
I’ve been following electricity prices, though, and these high prices are also lining Fortum’s pockets. I don’t know why this country isn’t building capacity that is actually weather-independent. We could be selling this expensive electricity to others instead of having to buy it ourselves.
They’re always talking about how we’re self-sufficient in electricity, which of course is total rubbish. The average might look okay because it’s windy and sunny during other seasons, but in winter, the situation is truly pathetic. I don’t know how future data centers will be powered if they actually move here. Most likely, the public will be paying even higher prices for their electricity in winter because the capacity simply isn’t sufficient to produce enough for the domestic market.
Shouldn’t the government, parliament, and even Fortum wake up and set up, say, a couple of smaller nuclear power plants? It won’t help with the problems immediately, but it would be good to start somewhere before the shit hits the fan.
12 Likes
Winter is on average the windiest season, and in fact, statistically January and February are the windiest months. Of course, there are occasional low-wind periods, as has happened in recent weeks (green represents wind power - screenshot from Fingrid’s website: Sähköjärjestelmän tila - Fingrid ).
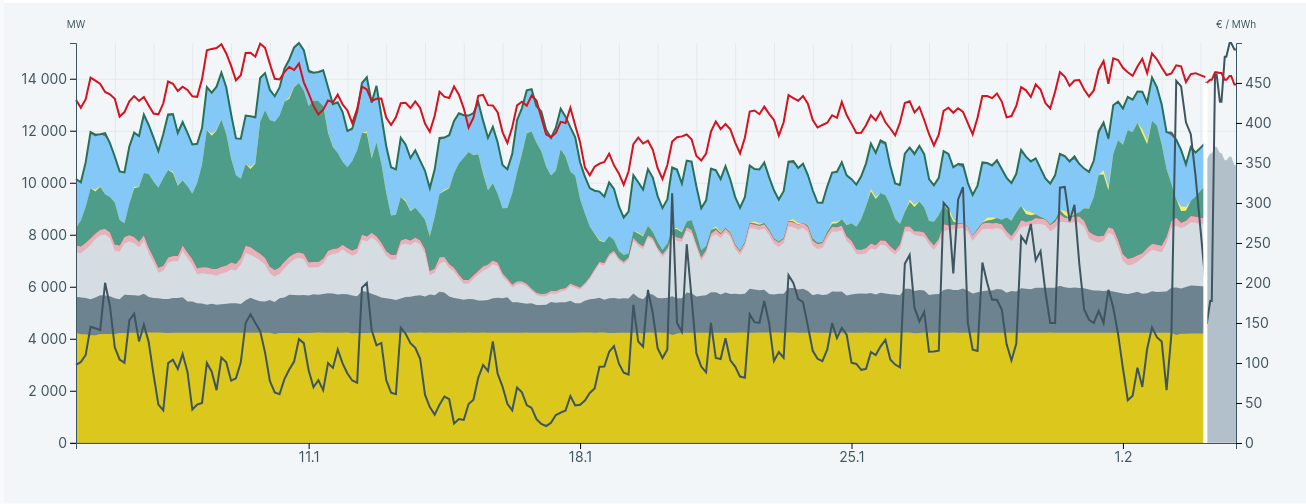
The fact that in some winters (note: not even every winter) there are periods of a few days when electricity is expensive does not justify additional nuclear power, because then during other seasons there would be a constant oversupply of electricity and prices would remain poor from the producer’s point of view. Therefore, economically viable additional construction of nuclear power requires a continuous growth in demand.
Balancing power is better suited for responding to occasional demand and price peaks, e.g., pumped-storage plants, battery storage, or even natural gas plants, as well as indirectly, district heating thermal storage.
38 Likes
October-December 2025
- Comparable EBITDA was EUR 336 (355) million.
- Comparable operating profit was EUR 251 (257) million as a result of lower production volumes.
- Operating profit was EUR 305 (390) million.
- Comparable earnings per share was EUR 0.23 (0.18).
- Earnings per share was EUR 0.27 (0.39).
- Net cash from operating activities was EUR 53 (167) million.
January-December 2025
- Comparable EBITDA was EUR 1,240 (1,556) million.
- Comparable operating profit was EUR 924 (1,178) million, mainly as a result of lower production volumes and electricity prices.
- Operating profit was EUR 939 (1,325) million.
- Comparable earnings per share was EUR 0.82 (1.00).
- Earnings per share was EUR 0.85 (1.30).
- Net cash from operating activities was EUR 840 (1,392) million.
- The optimization margin included in the achieved power price for total generation in wholesale sales was EUR 9.7/MWh in 2025.
- Fortum’s Board of Directors proposes a dividend of EUR 0.74 (1.40) per share and that the dividend be paid in the second quarter.
24 Likes
Hi everyone,
The Q4 result was a bit weaker than expected; at a quick glance, the achieved power price in the Generation segment and the underlying optimization premium in particular were lower than my own forecasts in Q4.
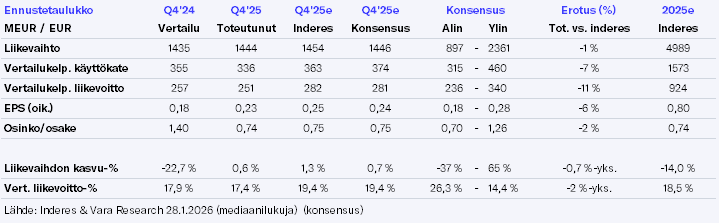
The dividend, which is what everyone is interested in, was at a perfectly normal level; there was no “dividend bomb” that some were apparently expecting. When you add the weak cash flow to that, it wasn’t a particularly strong Q4. Of course, the whole year 2025 was lackluster in terms of results, but it hasn’t hindered the share price.
There doesn’t seem to be much drama in the outlook; at first glance, hedging levels have risen quite quickly. As I said in the preview, 2026 electricity futures have risen nicely early in the year, which is likely the biggest factor behind the forecast changes. Of course, 75% of the 2026 production is already locked in at a price of €41/MWh, so it won’t be directly reflected in the results.
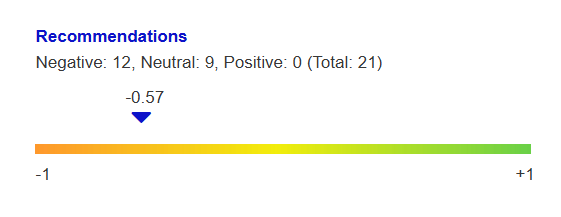
By the way, I noticed in connection with the preview that not a single analyst was positive on Fortum’s stock. I think it’s an exceptional situation. I’ve been one of the “least wrong,” but still completely off the mark with my reduce recommendation  You can find the consensus here: https://vara-services.com/fortum/consensus-analystoverview/
Just a little info package for the morning, and then back to thinking about the future.
53 Likes
The dividend was small considering the main owner’s need for cash. However, I think this is healthy. The political side also came to mind. After all, a state-owned power company can’t really pay out an excessive dividend when the common folk are suffering from electricity prices of 80c/kWh. That would be robbery and politically unsustainable. 
14 Likes
EPS 0.82 and dividend 0.74, meaning they are paying out almost their entire result as dividends. At the same time, there is a line like this:
Financial net debt at the end of the period 1,479(2025) 367(2024)
So they are taking on significantly more debt, and there are investment needs as well:
- In 2026-2030, Fortum’s investment commitments are expected to be approximately EUR 2.0 billion excluding acquisitions. This includes a total of approximately EUR 750 million in growth investments and approximately EUR 250 million in maintenance investments per year. Total committed investments excluding acquisitions are expected to be approximately EUR 550 million in 2026.
27 Likes
For once, the headline says it all. Rauramo interviewed by Iikka regarding the results:
31 Likes
The share price reaction is a surprise because there was nothing surprising in the results. A slight miss compared to consensus, but very little.
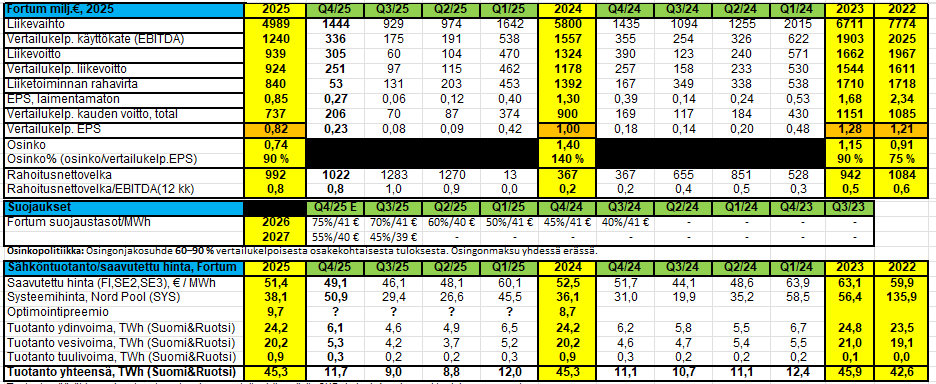
Usually, the price achieved by Fortum has been above the system price, but not now. Discreetly, it isn’t mentioned anywhere as it usually is, so I had to calculate it myself.
Money doesn’t automatically rain into AI-Fortum’s coffers; instead, they require heavy investments. If and when they happen, the dividend will be halved from this 74 cents.
EDIT:
I may have expressed myself unclearly, as I meant the system price (NordPool, average October–December)
33 Likes