Fodelia - Pioneer of the Food Industry

Greetings, this is a very relevant discussion, so I’ll comment on this whole with a few thoughts. First, to Pita Factory. This business was acquired during Fodelia’s original strategy in the midst of the pandemic, when it was decided that the group needed a business focused on retail trade. The foodservice market was completely frozen (schools closed, lunch spots closed, etc.). Pita breads came as part of the Perniön Liha / Helsingin Makkaratehdas deals, albeit as a separate company. The companies had cross-production, which is why the whole consisted of two different companies.

In connection with Fodelia’s strategy change, it was decided to focus on Feelia’s and Oikia’s businesses as a food industry player. A brokerage assignment was given for other businesses. As a result, the Perniö Liha and Helsingin Makkaratehdas businesses were sold to two different buyers (Uusi Perniön Liha and Tapola). In this context, for example, the filling of pita breads (which was a much larger business than making the breads themselves) was sold to Tapola. Fodelia recorded a sales profit from this deal. Only the pita bread factory in Jokioinen remained. The broker offered the target widely, but the bread factory alone did not sell under any conditions. Fodelia had the option of closing the factory or selling the target to a related party, who was interested in seeing if the company could be made profitable in any way. It should be noted that the Jokioinen factory property had years of lease liability, as well as installment debts for machinery and equipment. If no successor had been found for the factory, these would have fallen to Fodelia. The financial responsibility for these was hundreds of thousands of euros at the time of the sale.

After just over a year, one can ask whether the deal was in the company’s best interests or not. I am still absolutely of the opinion that the deal was in the best interests of Fodelia’s shareholders. The idea that the deal should have been rejected on the basis of related party status would not, in my opinion, have been in the company’s best interests. And from a responsibility perspective, it’s quite peculiar – to close down a factory and lay off staff simply because someone might be offended by a possible related party transaction. I myself did not participate in the negotiations for this deal or in the decision-making process.

The online store has been part of the group since the COVID years. During the online store boom of the COVID era, it was a very sensible business. Unfortunately, since then, growth has not been achieved despite heavy investments. The business has been unprofitable by hundreds of thousands of euros. For the past while, one person has worked in the online store. After various alternatives, either closing the store and disposing of inventory and packaging materials, etc., or finding a successor remained. The executive management negotiated with related parties about continuing the business, and the board, taking into account conflict of interest issues, decided to sell the businesses to the successors. For Feelia, the essential thing is that the successor will continue to act as a reseller for Feelia’s small packages. This enables sufficient volumes for sensible industrial production of small packages, as these same products are also delivered to small customers in Feelia’s normal supply chain. For example, the Oikiaruoka brand was not transferred in the deal, but the new company will build its own online store brand after a transition period. This is not really a business sale in the traditional sense, but more of a resale agreement. If someone else wants to be a reseller of Feelia’s products, they can, for example, start selling on the Shopify platform even next week. The executive management has negotiated this whole, and the board has made decisions taking into account conflict of interest issues.

It has been criticized in public that the announcement did not mention related party transactions. In retrospect, it would have been wise to mention the matter. Whether the aforementioned transactions have caused reputational damage to the company or shareholders remains to be seen. However, I can sincerely say that Fodelia’s best interest has been the most important interest in these matters. If this had not been the case, the executive management would not have presented these deals to the board, nor would the board have approved them.

Fodelia’s strategy of focusing on core businesses continues – it will benefit all Fodelia owners and customers in both the short and longer term.

55 Likes

First, thank you for clarifying these matters. I would always hope for such transparency immediately when informing about events. When it comes to related-party issues, it’s better to disclose too much and promptly than to leave question marks. The underlying reason is that other current and potential owners DO NOT know what you know internally, and in investing, knowledge is crucial, and any uncertainty is toxic. It’s not about someone “being offended.” If I, as an investor, put money into a company and thus own a piece of it, I don’t get offended (that actually sounds quite unpleasant), but rather I start to hesitate and price uncertainty into what I consider a fair value, and of course, also wonder if the investment is worth the uncertainty. It’s about trust and potential conflicts of interest, and no investor wants to smell the latter in their companies. There’s nothing personal against you in that. Even though the aftermath might certainly feel that way. The stock market has seen many examples where the interests of investors and management or major owners have not been clearly aligned, and in such cases, investors lose not only trust but also their fingers and money. That’s why every single publicly listed company must continuously earn trust. Even if you know that everything is above board and done to serve the interests of all shareholders, it is immensely important to communicate this to investors – as they don’t have the visibility you have. Hopefully, lessons are learned, and in the future, communication will be proactive and presented from the perspective of an external investor.

25 Likes

Tommi and Pauli are warming up as Fodelia reports its Q1 results on Wednesday, April 29. :slight_smile:

We forecast strong 13% revenue growth for the group, driven by Feelia. We estimate that the adjusted EBITA operating profit has clearly strengthened year-on-year, supported by the rapid growth of the more profitable Feelia.

5 Likes

Summary of January–March 2026

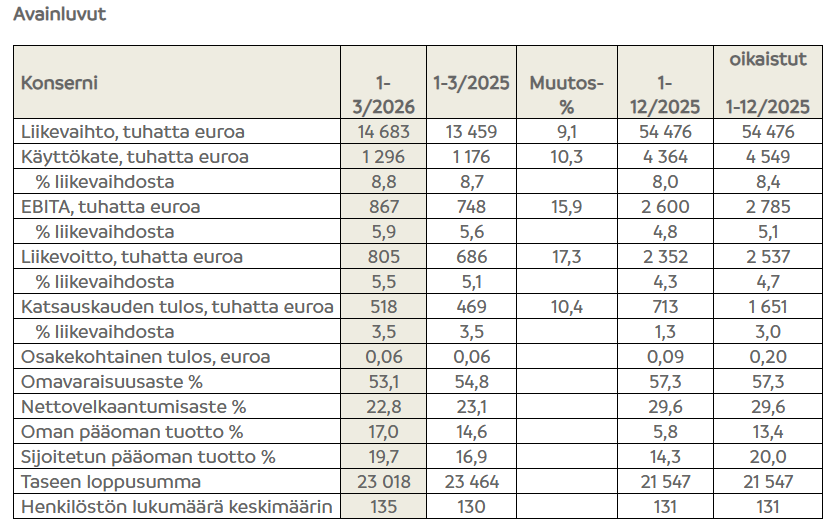
  • Revenue for the review period was EUR 14.7 million (13.5), revenue increased by 9.1%
  • EBITA for the review period was EUR 0.9 million (0.7) and 5.9% of revenue (5.6)
  • Operating profit for the review period was EUR 0.8 million (EUR 0.7 million) and 5.5% of revenue (5.1)

Guidance for 2026

Fodelia Group’s revenue in 2026 is estimated to be approximately EUR 59–65 million. Operating profit is expected to improve significantly in 2026 compared to the previous year.

highlights

several new food product customers with significant volumes started in March, which are expected to support growth in the coming months as well.

Feelia’s revenue saw strong growth of nearly 16%, in line with the company’s targets, while Oikia’s revenue fell by over 16% compared to the corresponding period last year. Within Feelia, revenue from Delimax products in particular grew significantly, following a flatter phase in 2025.

14 Likes

Highlight:

“Feelia’s profitability was challenged in the first quarter by film issues that began late last year and were only fully resolved in March. Now the root causes have been identified and fixed in a way that prevents a similar situation from occurring in the future. Production is also being actively developed all the time, which we expect to be reflected in improving profitability during the coming quarters.”

Bullish :rocket:

11 Likes

Here are Tommi’s quick comments on Fodelia’s Q1 result. :slight_smile:

Fodelia’s first quarter of 2026 was slightly softer than our expectations, as revenue and profitability fell slightly short of our forecasts. Feelia, acting as the group’s engine, continued its strong growth path supported by new customer accounts, but profitability fell short of our expectations, burdened by production issues. Meanwhile, the drop in Oikia’s revenue weighed on the group’s revenue growth. The company’s full-year guidance remained unchanged. Due to Oikia’s sluggish revenue development, our forecasts for this segment are subject to downward pressure according to a preliminary assessment, but Feelia’s strong growth outlook, which is central to the investment story and shareholder value, appears to remain intact in light of the report.

4 Likes

Tommi interviewed Fodelia CEO Riikka Wulff regarding Q1 :slight_smile:

Topics:

00:00 Introduction
00:14 Q1 summary
01:21 Feelia
02:58 Profitability improved at Oikia
03:48 Oikia’s outlook
04:52 Fodbar
06:12 Changes in the company
09:45 Feelia’s competitive advantages?
11:27 FERP ERP system
13:07 Guidance remains unchanged

4 Likes

I recall that in connection with Q3/2025, it was already said in a positive tone that the film problems had been mostly resolved and were no longer an issue in production. Feel free to challenge my comment :backhand_index_pointing_right: investors were given a slightly polished picture of the “film situation” in the autumn…
14 Likes

Tommi has written a new company report on Fodelia :slight_smile:

Q1’26 headline figures were slightly below our forecasts, mainly due to sluggish revenue from Oikia and what we estimate to be temporary production film issues at Feelia. The disappointment was mitigated by the rapid organic growth (+16% y/y) of Feelia’s revenue, which is central to the investment story and met our expectations. Forecast changes remained minor after the report. In our estimation, the strong earnings growth outlook for the coming years remains intact, which, together with the low valuation, makes the risk-reward ratio attractive. We reiterate our Buy rating and keep our target price of EUR 5.50 unchanged.

4 Likes

Let’s activate the Fodelia thread a bit in honor of the fact that the Parliament’s Commerce Committee has approved the report on the reform of the Procurement Act this afternoon, and thus the processing of the matter will naturally continue in the plenary session.

There aren’t many weeks left in the Parliament’s spring term; the most enthusiastic can follow here to see when the proposal hits the plenary session schedules. The report itself (and especially the dissenting opinions :slight_smile:) also provides good insight into the market regarding the number and value of meals, as well as in-house meal service companies.

The proposal has faced harsh criticism, but I personally believe it will pass thanks to strict party discipline; Minister Marttinen has even described the reform as the most important project of his ministerial term.

13 Likes

Today, the plenary session schedule for the Procurement Act was confirmed: the first reading will be on Tuesday, June 2, and the second reading a week later on Tuesday, June 9.

6 Likes

Over 3 million euro block trade with Fodelia share | Kauppalehti

“The company’s three largest shareholders held at least a large block’s worth of shares at the turn of the month. These were Mikko Tahkola, LBO Asset Management GmbH, and Jukka Ojala.”

9 Likes

Jukka Ojala, the former CEO of Fodelia, has been on the sell side for quite a while now. I wonder who bought. Well, that will be revealed in due time.

8 Likes

Didn’t have to wait long: Tahkola, Wulff, and the Germans

Fodelia’s second-largest shareholder, the German investment company LBO Asset Management GmbH, has increased its holding in Fodelia from 825,000 shares to 1,200,000 shares, which corresponds to 14.7% of the company’s shares and votes. Additionally, Axxion, a fund of the German investment company Discover Capital, purchased 330,000 shares, raising the number of shares under Discover Capital’s control from 150,000 shares to 505,000 shares, now representing 6.2%.

In connection with the arrangement, Plusvalia Oy, an investment company controlled by Mikko Tahkola, Chairman of the Board of Fodelia Plc, and CEO Riikka Wulff have also increased their holdings in the company. Riikka Wulff’s ownership rose from 31,538 shares to 51,358 shares (0.6%), and the ownership of Plusvalia Oy, controlled by Mikko Tahkola, rose from 4,100 shares to 51,100 shares (0.6%). Furthermore, Mikko Tahkola’s personal holding is 1,642,086 shares, bringing his total controlled ownership to 1,693,186 shares (20.8%).

The seller in all these transactions was Jukka Ojala, the former CEO of Feelia Oy and a shareholder of Fodelia, who is divesting his ownership in Fodelia.

20 Likes

I think this is a good sign. Strong anchor owners and Feelia has been moving in the right direction the whole time. Hopefully, this marks the beginning of a multi-year uptrend.

21 Likes

Here are Pauli’s pre-game thoughts ahead of Fodelia’s earnings report on August 5th. :slight_smile:

We expect the group’s revenue to have continued double-digit growth, supported by Feelia’s strong momentum. On the earnings lines, we forecast a clear improvement compared to the comparison period, assuming that Feelia has resolved its Q1 production issues and that Oikia has improved its margin level through better-priced private label agreements. However, there is uncertainty regarding the forecast earnings growth, given the recent challenges.

3 Likes

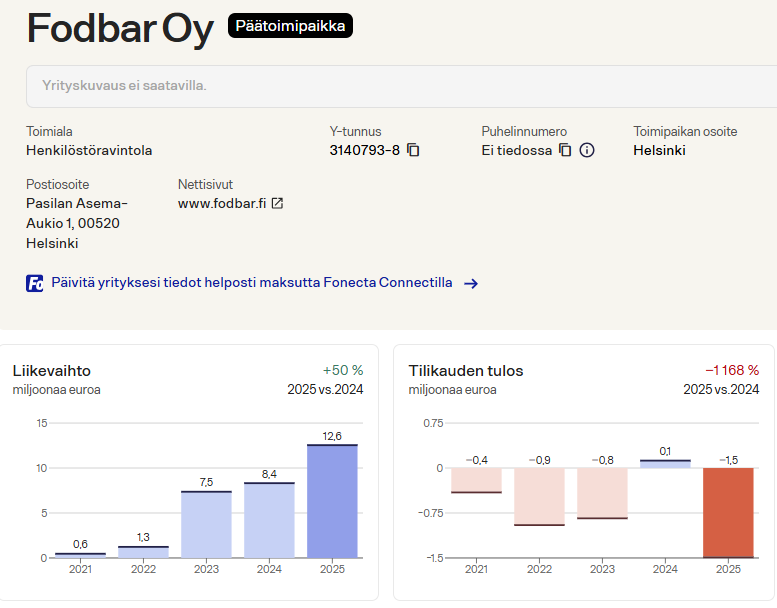
Fodbar’s numbers for last year have finally been released. Strong growth, but there were also heavy losses. It would be nice to hear Fodelia’s comments on this and what the future looks like.

19 Likes

During the reporting period, the group completed a business divestment in which the e-commerce business was transferred to a new owner. The review presents adjusted figures from which non-recurring items resulting from the business divestment (EUR 0.1 million) have been removed. In addition, the share of the loss of the associate company (EUR 0.8 million), which corresponds to the capital loan granted in Q2/2026, has been adjusted from financial expenses. For the comparison period, the adjusted figures include a total of EUR 0.2 million in costs related to reorganization.

Summary of April–June 2026

  • Revenue for the reporting period was EUR 14.2 million (EUR 13.5 million). Revenue grew by 5.0%
  • Operating profit (EBITA) was EUR 0.6 million (EUR 0.4 million) and 4.2% of revenue (2.6%)
  • Adjusted operating profit (EBITA) was EUR 0.7 million (EUR 0.5 million) and 4.8% of revenue (3.9%)
  • Operating profit for the reporting period was EUR 0.5 million (EUR 0.3 million) and 3.8% of revenue (2.1%)
  • Adjusted operating profit for the reporting period was EUR 0.6 million (EUR 0.5 million) and 4.4% of revenue (3.4%)

Summary of January–June 2026

  • Revenue for the reporting period was EUR 28.9 million (EUR 27.0 million). Revenue grew by 7.0%

  • Operating profit (EBITA) was EUR 1.5 million (EUR 1.1 million) and 5.1% of revenue (4.1%)

  • Adjusted operating profit (EBITA) was EUR 1.6 million (EUR 1.3 million) and 5.4% of revenue (4.7%)

  • Operating profit for the reporting period was EUR 1.3 million (EUR 1.0 million) and 4.7% of revenue (3.6%)

  • Adjusted operating profit for the reporting period was EUR 1.4 million (EUR 1.2 million) and 4.9% of revenue (4.3%)

Guidance for 2026

Fodelia Group’s revenue for 2026 is estimated to be approximately EUR 59–65 million. Operating profit is estimated to improve significantly in 2026 compared to the previous year.

At least they have had to pump €0.8M in financing into that.

Non-recurring items resulting from the business divestment (EUR 0.1 million) have been removed from the adjusted figures for the reporting period (both Q2/2026 and H1/2026). In addition, the share of the loss of the associate company, which corresponds to the capital loan granted in Q2/2026 (EUR 0.8 million), has been adjusted from financial expenses. EUR 0.2 million in non-recurring reorganization costs have been removed from the adjusted figures for the comparison period 2025 (Q2/2025, H1/2025, and 1–12/2025).

6 Likes

If the CEO is interviewed after the earnings release, it would be interesting to hear their views on the impact of the reform of the Public Procurement Act on the municipal sector. Has the restriction on the use of in-house companies already started to proactively stimulate demand in Feelia’s market, and can we finally expect real growth in public sector contracts?

4 Likes

Here are the quick comments from Pauli on Fodelia’s Q2 results.

Fodelia published its Q2 report today, which was weaker than expected based on the headline figures. Feelia’s lower-than-expected sales and profitability were due to, among other things, a single events-sector customer and the temporary impacts of production efficiency measures. Oikia, on the other hand, performed better than anticipated. In our view, the risk regarding the guidance has increased, even though the company expects growth to strengthen in the second half of the year, supported by the market entry into Sweden, among other factors.

5 Likes