Cambi doesn’t seem to be sparking much discussion. I don’t own the company myself, but it seems interesting. The firm feels like it’s flying under the radar.
Cambi’s primary business is thermal hydrolysis. The company’s thermal hydrolysis process is used in the treatment of sewage sludge and biodegradable waste, which in practice means wastewater treatment and food waste co-digestion projects. Through the process, the material becomes a valuable resource. For example, waste from agriculture and incineration plants can yield electricity and biogas, which can be used as fuel, through the digestion process. The technology is used in water treatment plants, and the purified water can be returned to nature.
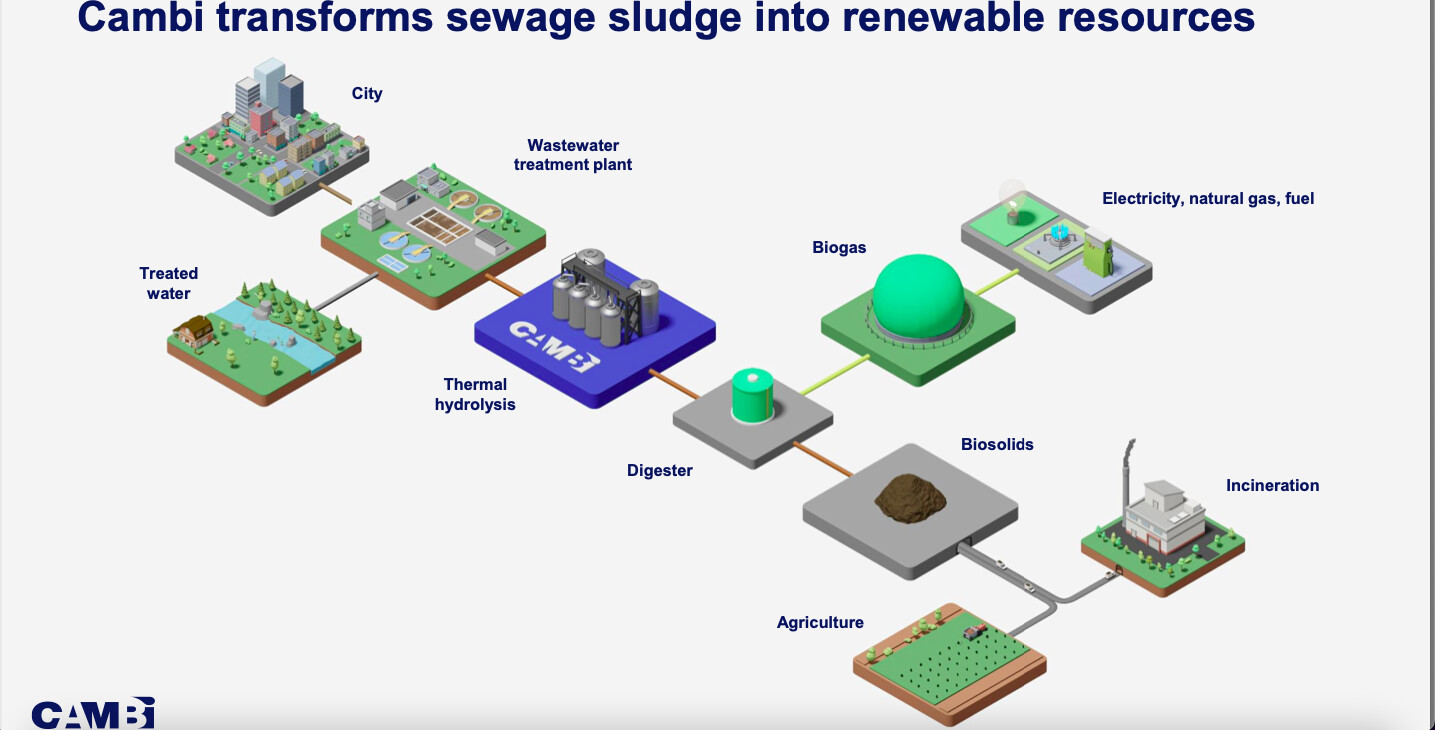
Video of Cambi’s value chain:
https://vimeo.com/870276237/a86dffdad3
A Capital Markets Day was held in September; here is the presentation:
https://www.cambi.com/media/2694/cambi-cmu-2023-presentation.pdf
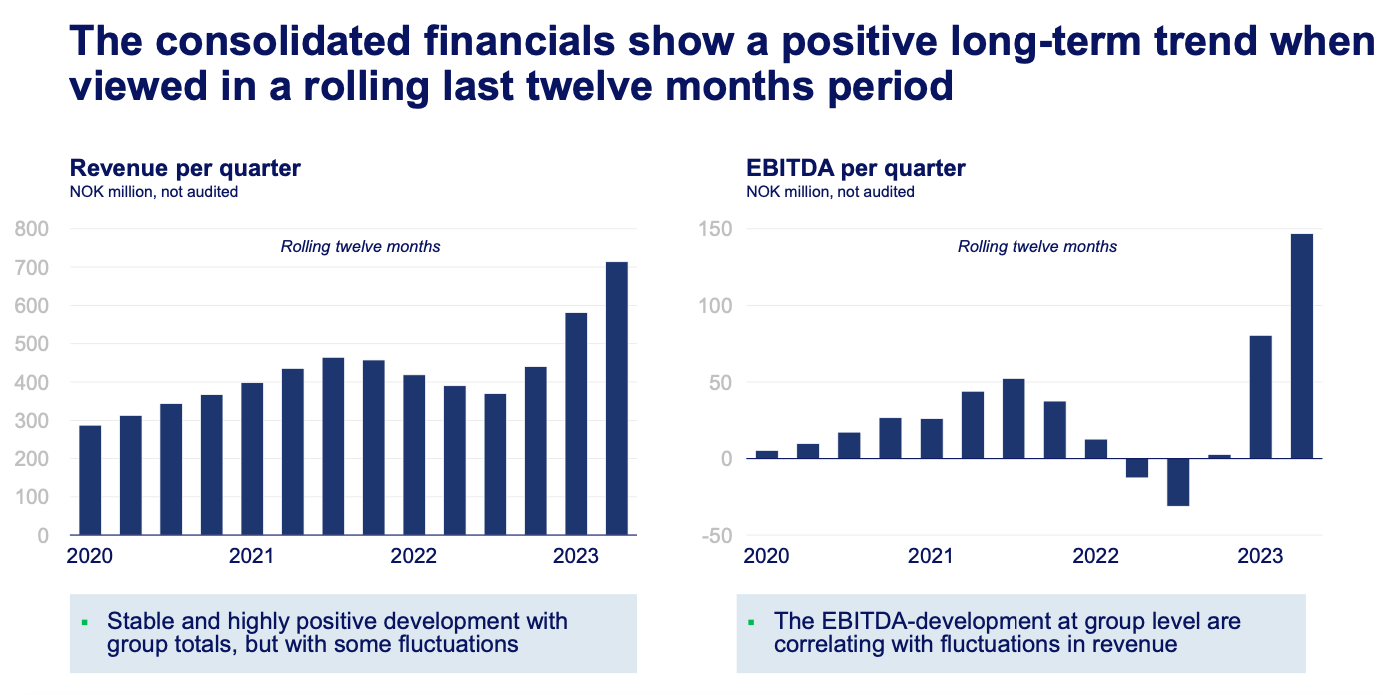
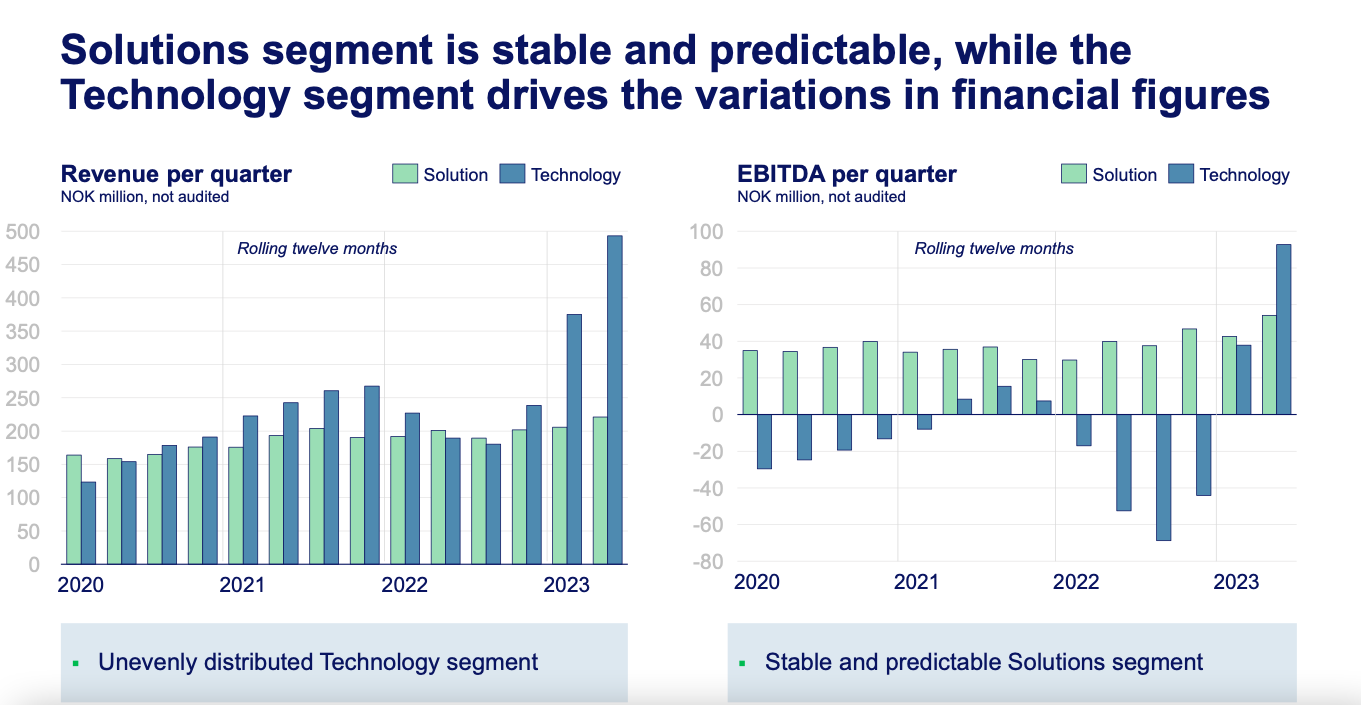
Cash flow depends on project delivery schedules. The company receives milestone payments as the project is delivered. The final payments arrive approximately 1.5 years after the start.
The company has also started paying dividends. For 2023, an ordinary dividend of 0.15 NOK was paid, and in October, an extraordinary dividend of 0.60 NOK. A relatively small share buyback program was also carried out during the summer. Dividend payments will continue next year, and the intention is to pay out 60-80% of net profit as dividends next year.
Q3’23: revenue grew by 115% to 235 million. EBITDA was 70 million NOK and operating cash flow was 115 million. New orders worth 983 million were received, and the order backlog stands at 1,791 million. Orders were also received from new markets, New Zealand and Israel. The business is already quite global today, with operations on every continent.
Of that 1,791 million order backlog, 13% will be delivered during the remainder of 2023, 40% next year, 30% in 2025, and the rest in 2026 or later.
Cambi also receives (monthly) cash flow from the maintenance of existing plants. The number of installed plants grows annually. The plants are long-lasting, and the first plant installed in 1996 is still operational.
Q3 profit was 70.1 million, or 0.44 NOK per share, and the result for the first 9 months was 1.07 NOK. The strong order backlog provides good visibility for the next two years.
The share price is currently around 15 NOK, so the valuation doesn’t seem very expensive.
Capex is quite low, about 1-2% of annual revenue. The company is net debt-free. Cash flow is strong, and based on analyst forecasts, the cash flow yield will be around 8% p.a. for the next couple of years.
Does the company spark any thoughts for anyone?