Digital Workforce - Automation and Software Robotics Service Company

@Joni_Gronqvist and Frans have given their quick comments on this morning’s result. :slight_smile:

Software robotics utilizing IT automation service company Digital Workforce published a slightly weaker Q3 report this morning than we expected. Revenue was at the previous year’s level and fell short of our expectations due to weaker development in continuous services. Adjusted profit clearly improved from the comparison period, supported by cost savings and a better sales margin, but was slightly below our forecast. The company is behind last year in its guidance for the beginning of the year, but the rather good outlook for the end of the year and the acquisition will, in our estimation, raise Q4’s profit and revenue significantly higher than last year.

5 Likes

In my eyes, the credibility of the management and financial targets was now definitively lost. There has been a strong sales pipeline for several quarters already, but it simply doesn’t show in the figures, and the management isn’t even interested in the stock.

4 Likes

Digital Workforce CEO Jussi Vasama was interviewed by Iikka. :slight_smile:

Topics

00:00 Introduction
00:15 Q3 highlights
01:27 Development of expert services
02:51 Recurring revenue was declining
03:46 Impact of cost savings on profitability
05:17 Development in different markets
08:50 Outlook for the rest of the year

3 Likes

Joni and Frans have prepared a new company report following Digital Workforce’s Q3. :slight_smile:

We reiterate our ‘add’ recommendation for the share and lower the target price to 3.7 euros (previously 4.30 €), reflecting reduced forecasts. Digital Workforce’s Q3 was slightly softer than our expectations. The turnaround in results has encountered some bumps this year and progressed slower than we anticipated. However, we expect the company to grow organically better than the IT service market in the coming years, and for this growth to scale into profitability. We find the share’s valuation (2026e EV/EBIT 11x, sum of parts 4.6 €) attractive.

5 Likes

The market remains difficult. Public administration has retreated into a “roach mode” (ruutanamoodi), which is reflected in the gloom of several IT consultants. Next year doesn’t look better, but not worse either, because demand is already so low.

Regarding agents, buyers have an abundance of choice. Various solutions are trendily marketed as “agents,” which tends to confuse potential buyers. The situation was like a taxi stand at the main railway station at its worst, to put it a bit hyperbolically. Promises are overly ambitious, but when it comes to replicable concepts, it’s quieter.

It’s easiest for those in the Microsoft camp to adopt one of the Copilot technologies, and other US giants offer similar plugin solutions for those who have chosen their ecosystems. A difficult David vs. Goliath situation for DWF.

So, I’m not putting on my buying pants yet. Some patient operator dreaming of cross-selling might buy DWF, but it’s difficult to justify purchases based on that card.

7 Likes

e18 Innovation (e18), part of the Digital Workforce Services (DWF) group, is delighted to announce a new partnership with NHS Humber Health Partnership (HHP), one of the largest healthcare providers in the NHS. Under this exciting new automation programme, e18 will deliver an ambitious outpatient transformation plan designed to free up more than 26,000 hours of staff time each year, and generate circa £1m of tangible financial savings over the three year contract.

4 Likes

Announcement:

Digital Workforce Gets Three-Year Contract Extension

IT service company Digital Workforce announces it has extended its agreement with Portsmouth Hospital University NHS Trust by three years. Under the agreement, the company will continue to deliver and expand automation services in cooperation with the Trust and another partner, PSTG.

The existing agreement will be expanded with business process management, orchestration, intelligent document processing, and a 24/7 incident management service.

According to Digital Workforce’s press release, the UK’s NHS, or National Health Service, is one of Europe’s largest healthcare systems in terms of scale and scope, covering services for 56 million people.

The value of the agreement was not disclosed in the press release.

6 Likes

A smaller renewal contract was announced last week. I don’t think it was here yet.

3 Likes

It has been quite quiet on the press release front from DWF. Finland’s social and healthcare sector has been a significant client, but for known reasons, even “drastic” budget cuts are mercilessly slashing consulting demand. It’s also sad how image-boosting efforts go down the same drain as automation projects that bring savings.

In press releases, they gladly lead with AI/agent initiatives, but it seems harder to convert that into revenue. So, things are going pretty much as expected.

The share price has steadily fallen towards the turn of the year, and this stock also seems to be one of those being sold off due to tax-loss selling. With thin trading volume, sales quickly impact the share price.

Already in Inderes’ stock comparison, the difference to the target price is worth a silver medal on the Finland list (+38 percent).

5 Likes

Joni has prepared a new comprehensive report on Digital Workforce, and as usual, this extensive report is available for everyone to read. :slight_smile:

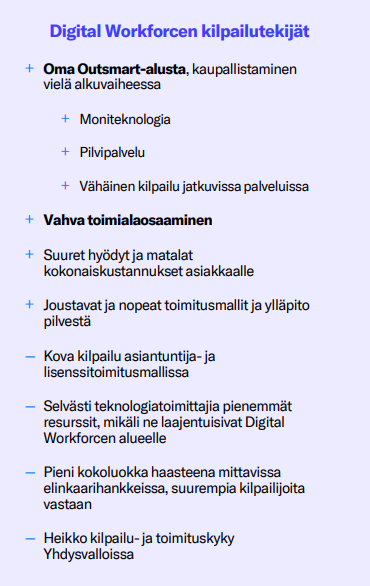
Digital Workforce automates clients’ knowledge work processes by utilizing software robotics and artificial intelligence. In recent years, the strategy’s focus has reasonably narrowed down to selected industries, chosen growth markets, and its own platform. The strategy resonates but still requires evidence of a breakthrough. Now, the company must demonstrate a return to better organic growth and its scalability to profitability. The stock’s valuation picture is, from several perspectives, at least attractive. We reiterate our ‘add’ recommendation for the stock and lower the target price to 3.2 euros (previously 3.7) reflecting a decrease in medium-term forecasts.

Quoted from the report:

Our forecast reflects better long-term growth and profitability than the IT services sector. Better growth is due to stronger underlying growth than the IT services market. Better profitability, in turn, stems from a more scalable business structure. However, the company still lacks evidence of stronger growth and especially profitability with the new strategy and structure in the 2020s.

image
image

3 Likes

“Digital Workforce launches insurance industry AI agents that independently perform claims processing tasks, from First Notice of Loss (FNOL) to the settlement decision, by reading claims-related documents, applying insurance terms and conditions, identifying potential fraud, and working across different insurance systems.”

Agent Workforce is available on Microsoft Marketplace.

“Digital Workforce customers can now find and deploy Agent Workforce through Microsoft Marketplace, streamlining integration with the customer’s Microsoft Azure and other Microsoft products.”

“With Agent Workforce, insurance companies can deploy AI agents alongside their existing Microsoft services, achieving measurable business benefits while meeting the level of security and traceability required by large enterprises.”

There is competition in the insurance sector, but it is presumably a good addition for a regulated industry:

11 Likes

The project announced in the fall with the City of Helsinki was worth 2.4M, making it a fairly juicy deal.

Hilma

13 Likes

DWF reorganized its management team – a couple of new appointments with the fancy “Chief Growth Officer” title, and a few were dropped.

Growth is exactly what DWF, which profiled itself as a growth company during its IPO, needs. For this year, revenue should reach 50 MEUR (2025: ~29 MEUR). The growth target has been clearly lowered, but it remains overoptimistic without a substantial acquisition – from Inderes’ comprehensive report:

The target is now 50 MEUR in revenue by the end of 2026 (at the IPO, the target was 100 MEUR in 2026 and at the end of 2022, 50 MEUR by 2025). The target is still split into 40 MEUR organically and 10 MEUR through acquisitions. The organic growth target is ambitious and, in our view, nearly impossible.

Share buybacks are underway, but management’s wallets remain tightly shut. The lack of buying could be due to various reasons, including insider information, but as the share price continues its trend-like slide closer to the two-euro mark (rather than three), one would have thought there were buying opportunities. If the company’s own shares are intended to be used as currency in an acquisition, a falling share price is poison as dilution increases. (Large payments cannot be made with already acquired treasury shares.)

DWF has not, however, squandered its money on forced growth, so unlike many “growth rockets” from the same IPO cycle, DWF does not need to conduct directed share issues hat-in-hand just to keep the lights on. Let alone for growth. That would be a good foundation to build growth on…

Preparation for new strategy work will begin during the current year, and the management shake-up is likely related to that. The central question is the aforementioned growth dilemma. Is DWF at risk of remaining a laggard at a time when, technologically speaking, the moon and stars should be aligned in its favor?

You can always play the Trump or Russia card, but there is something wrong with your own execution if organic growth grinds almost to a halt for several years.

4 Likes

The Capman fund that owns DWF is expected to exit its holding this year. At least according to the original schedule. Will the ownership be transferred to a newer Growth fund? Pension companies and funds selling the stock like crazy certainly aren’t making matters any easier…

4 Likes

Interesting release this morning! The agreement is evidence of the company’s Agent strategy moving into production. While the scale of the agreement is likely relatively small (press release), it certainly supports forecasts and especially the progress of the strategy. Keep them coming :slight_smile:

20 Likes

Quite a big trade :sweat_smile:

6 Likes

That came as a press release, in the Inderes feed it looked like the correct figure starting with an M was there in the release :smiley:

2 Likes

Perhaps there’s plenty of work to be done there for DWF:

The organization is internationally respected, and its scale is exceptional from a European perspective, as its operational revenue is close to the same magnitude as the total public healthcare expenditure of Finland,” describes Jussi Vasama, CEO of Digital Workforce

Who knows how much of that is suitable work for Digital Workforce, but it’s a quite nice reference (especially from the USA) and it will likely contribute something to the bottom line, too.

7 Likes

Here is Joni’s preview ahead of Digital Workforce’s results release on Wednesday, February 18. :slight_smile:

We forecast strong revenue growth driven by acquisitions and also solid organic growth. Additionally, we expect profitability to be strong, fueled by efficiency measures and growth in higher-margin recurring revenue. In the report, our attention will be focused particularly on the 2026 guidance and comments on the organic growth outlook in light of the recent major US contract. Our comprehensive report on the company, published in December and still very relevant, can be read here.

3 Likes

Financial statement report released, we got close to Joni’s forecasts. Outlook shows at least 15% growth for 2026, and the dividend proposal is a hefty €0.09. This looks good to me.

It also occurs to me that the categorically low valuations of IT service companies will likely lead to DWF being bought out of the stock market in the near future. Capman’s fund ownership is also already overdue; the fund has a slice of just over 15% of the company.

13 Likes