A comment is also available, pretty much in line with expectations
8 Likes
In my opinion, Anora’s financial statement confirms the idea that this is a so-called eternal promise. Earnings per share consistently look very poor. Next year is always supposed to be better, but it never is. For this reason, I’m staying away. Admittedly, you have to respect the dividend. I’d rather continue the struggle with companies 100–1000 times larger. There are plenty of challenges with those as well.
5 Likes
Daniel interviewed Anora’s CEO Kirsi Puntila regarding Q4. 
Topics:
00:00 Introduction
00:19 Summary of Q4 and the full year
02:09 Positive profitability development
02:53 Focus areas in the Wine segment under new management
04:27 Personnel changes and other structural improvements
05:52 Guidance for improving profitability and the drivers behind it
4 Likes
Rauli has published a company report right after the Q4 results
Anora’s Q4 result was in line with our forecasts. The midpoint of the 2026 guidance indicates an earnings improvement of just over EUR 5 million, in line with the company’s medium-term targets. We slightly raised our 2026-27 forecasts and expect this year’s adj. EBITDA to be EUR 75 million. Due to a lower debt level, we raised our DCF value as well as our target price to EUR 4.0 (prev. EUR 3.8). We reiterate our Reduce recommendation, as we believe the stock’s valuation is neutral (e.g., 2026 P/E 10x) and growth potential is limited.
6 Likes
Picked up from Puntila’s interview. Anora is entering the energy drink market in some way with its own alcohol-spiked energy drink:
6 Likes
Chairman of the Board shopping, 12,000 shares Anora Group Oyj: Johdon liiketoimet - Atle Vidar Nagel Johansen | Kauppalehti
10 Likes
Board member buying, 5,610 shares: Anora Group Oyj: Johdon liiketoimet - Rebecca Tallmark | Kauppalehti
You can track management holdings here: Johdon omistukset | Anora
7 Likes
The Alcohol Act may change in a significant way. Perhaps this is a positive thing for Anora.
“The manufacturer would not necessarily have to distill the alcohol for the drinks themselves in all cases, as long as a characteristic part of the production for the drink takes place at the production site from which the spirits are sold.”
Apparently, a small distillery would not be required to distill the ethanol themselves.
3 Likes
Enjoy the read with a good drink (not a recommendation to use alcoholic beverages, ed. note): Anoran vuosikertomus vuodelta 2025 on julkaistu | Kauppalehti
6 Likes
Alko’s quarterly sales statistics for Q1 were released today. The trend remains negative for Anora, with wines down 6% and spirits down 5%. Easter fell at the turn of March and April this year, whereas last year it was in late April, so the Q1 figures should have received a small boost from the timing of Easter compared to the reference period. A decline of this magnitude is, of course, also within Anora’s current expectations, so efficiency measures should be able to tackle it. Especially in spirits, Finland is an important market for Anora, as it contributed 40% of the Spirits segment’s EBITDA in 2024.
It is worth mentioning at the same time that in Norway, for January-February, the market is down slightly by 1%.
6 Likes
Rauli has prepared a new comprehensive report on Anora, and like other comprehensive reports, it is available for everyone to read.
We slightly lowered our forecasts due to the likely acceleration of inflation, but we still believe the company will gradually improve its results in 2026-28. We reiterate our “reduce” recommendation and a target price of 4.0 euros, as we believe the share valuation is neutral (e.g., 2026 P/E 11x) and the growth potential is low.
Quoted from the report:
Valuation Summary
Anora’s earnings expectation for the coming years consists of both dividend yield and earnings growth, as the margin level gradually improves from a weak starting point. The share’s valuation level for 2025 is not yet attractive based on earnings multiples, considering the modest organic growth potential. However, looking at other valuation methods and earnings multiples for the coming years, the overall valuation picture appears neutral.
We see the total return expectation for the share consisting of dividend yield and earnings growth driven by improved profitability, offset by an expected decrease in multiples. Based on different valuation methods, our fair value range for Anora is 3.3-4.5 euros.

4 Likes
Anora’s view indeed remains unchanged. The strategy and financial targets sections have been updated to reflect the company’s updates from late last year, with other sections receiving more standard updates. I slightly revised the forecasts downwards due to nascent cost inflation. The company offers a reasonable cash flow and dividend stream, but the lack of market growth makes earnings growth difficult in the coming years as well as in the longer term.
5 Likes
Hey Rauno! I’m going to chime in on this thread and analysis to ask the following:
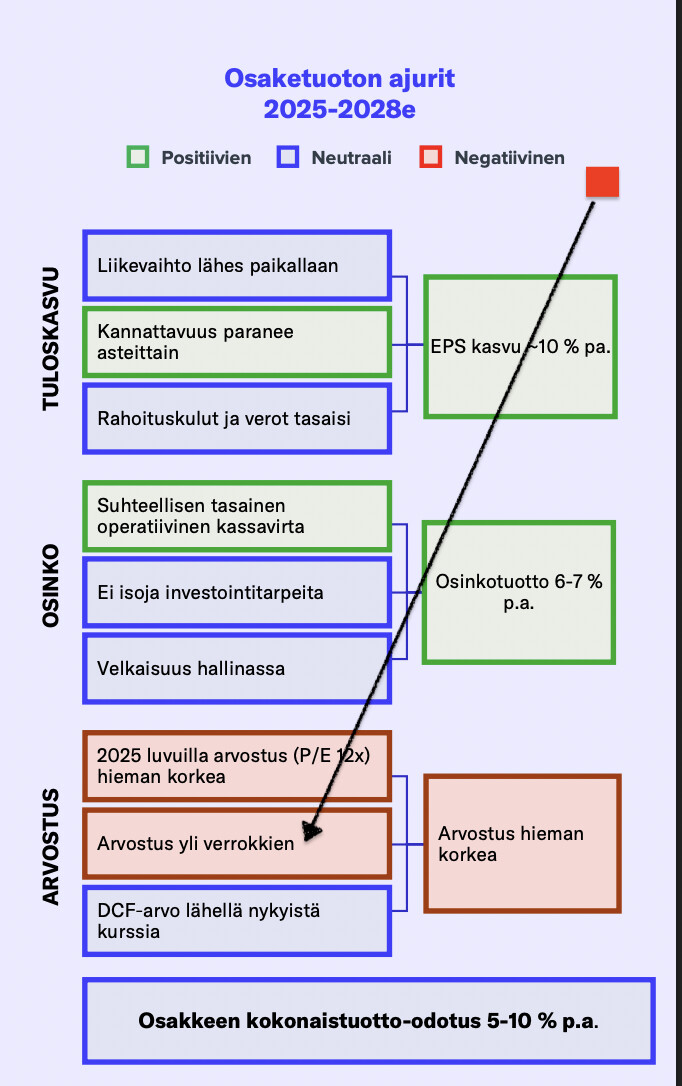
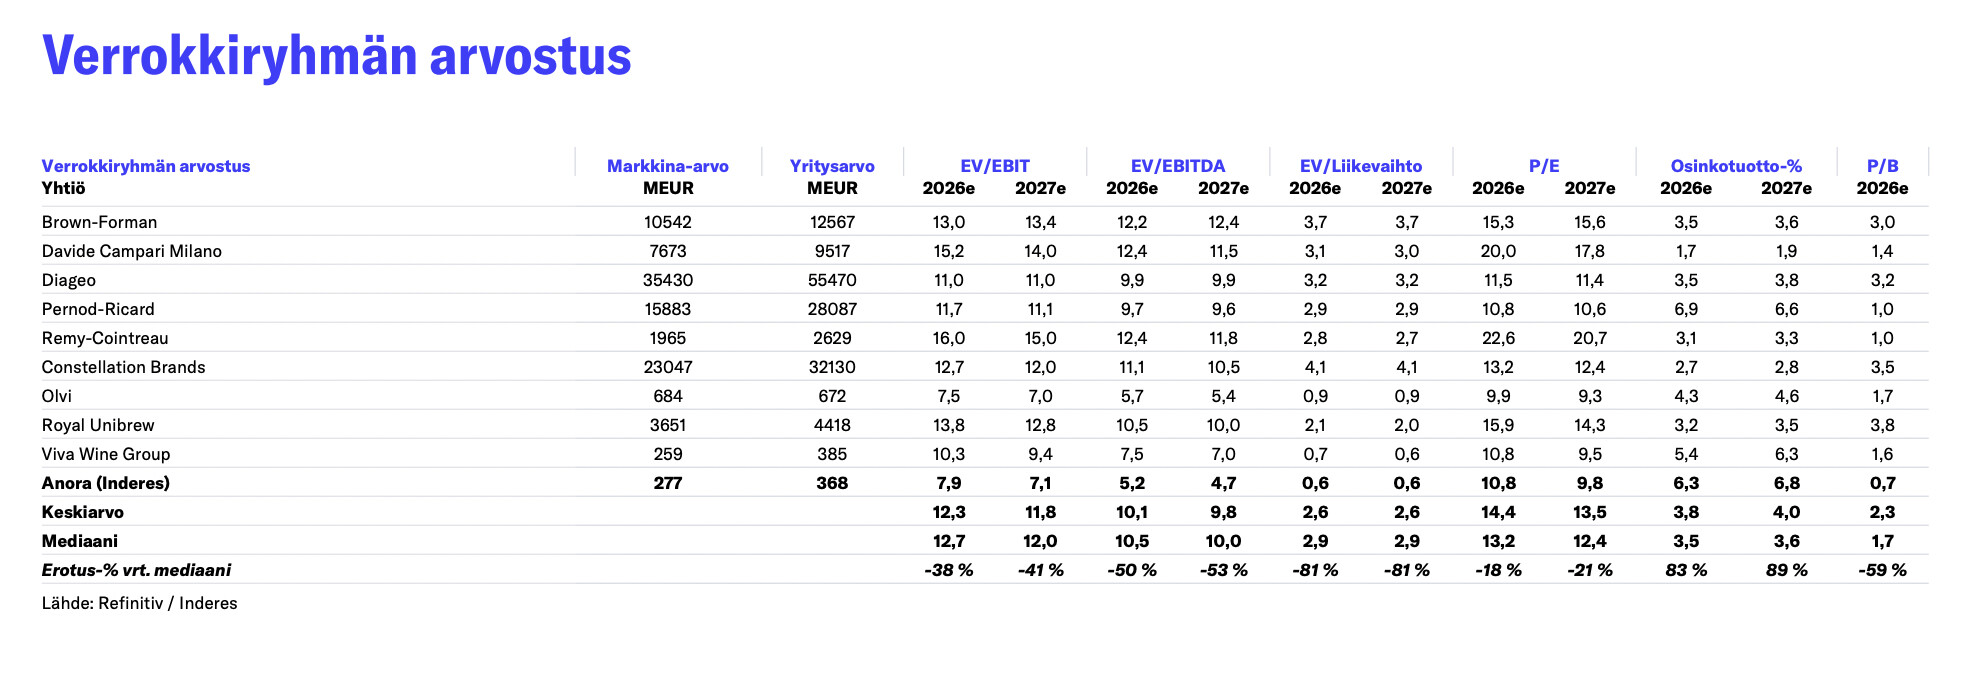
Why is Anora’s valuation in the analysis both above and below the valuation of its peers? The peer group clearly shows that Anora’s valuation is below. The drivers of shareholder return, however, claim it is above. Is there some logic we’re missing here?
1 Like
There’s no logic at all, just my own mess-up  It is below, but as the text explains, I don’t consider comparing it to the peer group very relevant. It should be a blue, i.e., neutral, box that says “valuation below peers”. I’ll correct that, thanks for noticing

According to Bloomberg, Brown-Forman and Pernod Ricard are considering a possible merger. The news came out over a week ago, but let’s put it here too.
In a structurally declining market, it would be good to optimize structures.
You can read some kind of summary from Yahoo Finance: Ihre Datenschutzeinstellungen
5 Likes
On Friday, there were also rumors that Sazerac had approached Brown-Forman with some kind of deal.
5 Likes
Rauli and Tomi discussed Anora.
Topics:
00:00 Today’s youth consume less alcohol
02:16 Expanding the product offering
04:27 Inflationary pressures are rearing their head
06:35 Prerequisites for profitability improvement
3 Likes
Maybe a bit off-topic, but I’ll post it here anyway.
The Finnish Long Drink, a Finnish long drink company, was sold for 275 million euros. I think that’s a pretty good price, considering Anora’s market cap is 273.6 million.
16 Likes
CEO and CFO review from last week’s Annual General Meeting! 
6 Likes
Today, Q1 market figures were received from Sweden (the quote above refers to the previously published Finnish figures): Spirits +1.5% and wines -1.5%. According to Systembolaget, the timing of Easter supported the figures by about 2 percentage points (this applies to the total volume, i.e., including beers, so the impact on spirits and wines may be even greater), meaning that adjusted for this, consumption is sliding downwards.
In Norway, March saw very brisk growth (~20%), and thus Q1 ended at +7% for wines and +5% for spirits. However, in Norway too, the Easter-adjusted Q1 development was down about 1.5% according to Vinmonopolet’s estimate. Apparently, more is consumed in Norway during Easter than in Sweden, as the impact is larger; it seems many people there have a habit of vacationing for the whole week, and there are more public holidays 
A declining market and the timing of Easter have certainly been known, but in Norway the impact was perhaps surprisingly strong, while in Finland the market was miserable despite Easter. I still need to check the figures for Anora before the results, but for Q1 we have a fairly clear earnings improvement, and Q2 is roughly at the level of the comparison period, largely due to the timing of Easter.
8 Likes