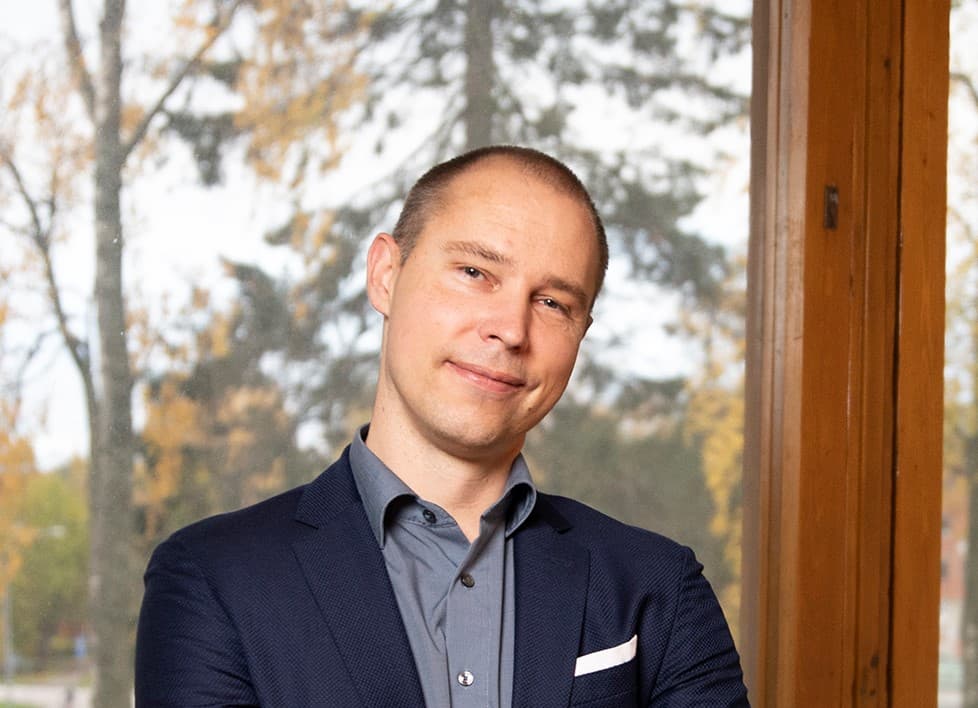
128. Peter Nyberg
Peter Nyberg is an analytical, versatile, and deeply knowledgeable expert who examines the markets systematically and critically. His background as a professor of finance, combined with his experience in researching and developing investment strategies, makes him a rare blend of academic expertise and practical market understanding.
He truly has the ability to make complex financial theories understandable, for instance, and knows how to talk about things in an engaging way. Peter does not hesitate to challenge conventional wisdom, and he avoids unnecessary fluff or black-and-white generalizations—which are just a few of the reasons why his posts are so interesting to read.
Reading his thoughts gives you the feeling that, in a way, things aren’t as complicated as one might think. He writes in a pragmatic sense and in a manner that gets the reader thinking for themselves, which is naturally fantastic.
1. Tell us who you are in fifty words.
I am Peter Nyberg, a Professor of Finance at Aalto University School of Business. I research stock markets, the magnitude and variation of expected returns on investments and investment strategies, quantitative investment strategies, and financial market topics in general. I also teach investment science as well as theoretical and empirical asset pricing at both undergraduate and doctoral levels. Additionally, I have consulted for international mutual funds employing active strategies, which is one way to bring the latest research directly to asset managers.
2. Tell us three things few people in public know about you.
I am still a bit like a ten-year-old boy, at least in the sense that I often get what I think are funny whims and can’t always restrain myself when they hit. For instance, in meetings, I am naturally always professional and pertinent, but at some point, I can no longer resist the temptation and toss out a comment inspired by the topic at hand, seasoned with my own peculiar humor. This happens even more frequently when I teach or give presentations. Usually, it’s received with laughter, but occasionally—thankfully rarely—it is followed only by awkward silence.
I also once studied philosophy at the University of Helsinki, but I never graduated.
I used to collect movies and owned over 1,000 DVDs, which were the standard format back then. I was proud of my collection. However, my cohabiting partner at the time was less thrilled with a bulky disc collection taking up space. I agreed to store the movies in the basement until we moved into a larger apartment. I have moved a couple of times since, and the movies have simply migrated from one storage locker to another, where they still remain today.
3. What interests and hobbies do you have besides investing?
I hit the gym quite regularly and cycle a lot as well. When I was younger, around the turn of the millennium, I took bodybuilding really seriously, which is why I still don’t know how to work out at anything less than full intensity. I also read a lot of literature and slip into a sort of trance whenever I can listen to music in peace. Philosophy and history also interest me immensely.
4. What does a typical weekday look like for you?
I wake up between 5:00 and 7:00 in the morning, depending on whether I’m going to the gym. Sometimes, especially in the mornings, I work remotely from home, but most days I am at my office in Otaniemi. The content of my workdays varies greatly. Occasionally, I manage to dedicate at least part of the day to research and data analysis, but most often, I am answering emails, attending administrative meetings and academic seminars, teaching, designing presentations, peer-reviewing other researchers’ papers, and supervising master’s and doctoral theses. And much more. One might think a professor’s job is monotonous, but it is anything but, and it often feels like there isn’t enough time. However, I love my work and couldn’t imagine doing anything else.
5. What kind of investor are you?
I am probably a fairly boring investor, and I don’t usually get excited about stock tips or what others are doing. Unless I see a sufficiently high probability of generating alpha (excess return), I will not overweight an asset in my portfolio. “Boring” investing isn’t necessarily a bad thing. As George Soros put it: “If investing is entertaining, if you’re having fun, you’re probably not making any money. Good investing is boring.”
6. What is your investment history like?
I made my first investment right after graduating from high school. Looking back, it was also an educational experience that proved very useful. At the time, Finland was at the dawn of the Nokia boom. Everyone had a Nokia 5110 mobile phone (the snake game!), and the company’s stock price had roughly doubled in a year. So, I took the money accumulated from my graduation gifts, marched into a bank branch, and made my very first investment in Nokia stock. As I recall, the share price was around 7.5 euros. Two years later, the price had risen to 65 euros, meaning my investment had increased ninefold. The joy didn’t last long, as everyone knows. If nothing else, it gave me a great anecdote to use in my lectures.
7. What is your portfolio like? If you were forced to hold two stocks currently in your portfolio for at least five years, which would you hold and why?
When speaking of equity investments (other asset classes do exist, of course), about 80% of my portfolio consists of geographically and sector-diversified passive investments, where I have aimed to minimize investment-related costs. Around 20% of my portfolio is capital to which I apply a more active investment strategy.
I don’t really pick individual companies for my portfolio; rather, I prefer to think of them as individual stocks that possess specific financial ratios, price histories, a certain level of profitability, a certain volatility, and so on. Nor do I invest in just one stock that meets my criteria for these characteristics; instead, I invest in multiple similar companies to reduce company-specific risk in my portfolio. In this sense, individual companies essentially “disappear from my portfolio,” and the portfolio is constructed around certain average company- and stock-level characteristics rather than the companies themselves.
8. Does studying finance (at least when motivated) provide the tools to become a better investor and manage one’s personal finances?
Yes, assuming, of course, that the student internalizes what they learn and knows how to apply it across different situations. A degree in finance will not make anyone a master stock picker—no field of study can guarantee that. Regarding stock picking, however, a finance graduate will certainly know how to read a company’s financial statements and balance sheet, understand the mechanics of business economics and the markets, and be able to make a relevant assessment of a company’s share value to compare against its market price.
I would say studying finance is even more beneficial for professional asset management, as the education—especially at the doctoral level—provides skills applicable to everything from equity funds to hedge funds, and from passive investment strategies to active alpha hunting. These skills include, among others:
- A solid understanding of the potential causal relationships and systematic patterns uncovered in stock return data by academic research
- The factors driving expected stock returns
- Modeling return expectations and creating new models
- The ability to separate signals of expected returns from all the noise in equity return data
- Developing and critically testing active strategies
- Minimizing transaction costs and ensuring adequate liquidity
- Risk management
- Performance attribution (identifying the factors behind a portfolio’s excess or under-performance)
The list could go on indefinitely. While not everything can be taught within the scope of a single degree, studying finance up to the master’s level lays a foundation upon which one can easily build this expertise throughout their career.
9. How should an individual investor who engages in stock picking take seasonal patterns into account in their investment decisions?
You’re probably referring to phenomena like the January effect, “sell in May,” and so forth. It is uncertain whether these phenomena genuinely exist or if they are merely historical flukes—meaning that average returns just happened to be higher for small-cap stocks in January. By definition, pure chance doesn’t tend to repeat itself systematically in the future.
For example, the January effect associated with small caps seems to have vanished from international return data over the past twenty years. On the other hand, the “sell in May” phenomenon (i.e., that returns are, on average, lower from May to October) has received somewhat more support in recent studies, suggesting the effect might not have been purely a fluke after all.
In my view, an individual investor who buys and sells stocks without building complex positions does not need to worry too much about these phenomena. Any small potential benefit one could extract from seasonal patterns is easily wiped out if the investor waits too long before deploying capital. The expected return in the stock market remains positive even during the period you spend waiting for a specific month—and you miss out on that return in the meantime.
10. Should investors switch to certain low-cost index funds, given that 95 percent of retail investors underperform the index and only a tiny fraction ever make an “hourly wage” from picking their own stocks?
It is true that the vast majority of retail stock pickers lose to the index, especially over the longer term. There are multiple reasons for this, but let’s not delve into them right now.
We are all individuals. We draw enjoyment from different things, have different goals, and perhaps reasonably choose the investment style that suits us best. No one can tell another person that they should switch their investment style. The prerequisite here, however, is that the investor is aware of the odds and understands that, in terms of expected value, they would perform better over the long run as an index investor.
11. You have researched that corporate sustainability (e.g., ESG) does not necessarily have a direct link to stock returns. Do you have any thoughts on how investing could make the planet a more responsible and happier place… or is this just futile contemplation?
That is by no means futile contemplation. I haven’t conducted research on this exact topic myself, but in my commentary, I have referenced several studies concluding that companies with high ESG ratings do not generate excess returns. It is important that the perspective presented is not based solely on a single study, but rather on the broad body of academic literature that has addressed the subject.
A company’s shareholders own the business and therefore hold decision-making power over its operations. This simple fact is often forgotten in the discussion. If a large group of investors views a company’s current practices as harmful, the solution is not for these critical investors to refuse to buy the company’s shares. On the contrary—shouldn’t they buy as large a stake in the company as possible to make their voices heard? If, for example, the capital flowing into ESG funds were used to purchase shares of irresponsible companies, responsible investors could genuinely steer corporate actions in a more sustainable direction through so-called “shareholder democracy.”
12. It is often assumed that corporate share buybacks automatically enhance shareholder value. Could you explain why this isn’t always the case, and what an average investor should keep in mind?
This holds true only if the market price is too low relative to the company’s “true” value (i.e., the stock is undervalued by the market). Consider, for instance, that the market price is 8 euros, while the “true” value of the share ought to be 10 euros. In this scenario, the company could repurchase its own shares “too cheaply”—paying the exiting shareholders the market price of 8 euros, which is below the share’s intrinsic value of 10 euros. The surplus value not reflected in the price paid would, in this case, accrue to the remaining shareholders and their shares (2 euros multiplied by the number of repurchased shares). However, that is not yet visible in the market price of the remaining shares. Only when the market “realizes” the undervaluation does the share price rise, and the remaining shareholders capture both the 2-euro additional value per existing share and the surplus value given up by the selling shareholders who sold to the company too cheaply.
In public discourse, however, people rarely refer to the scenario described above. Instead, there seems to be a misconception that because earnings per share (EPS) increases, the remaining shares automatically become more valuable—regardless of whether the market price of the stock is fair, overvalued, or undervalued. That is indeed an intriguing hypothesis: a company should simply keep buying back its own shares indefinitely, as the remaining shares would become increasingly valuable until the single remaining share was worth substantially more than the entire company’s current market cap! You could call this a money-printing machine that makes the remaining shareholders enormously wealthy. Unfortunately, no such machine has been invented yet—at least not in the stock market.
The arguments for why a stock’s intrinsic value does not inherently change as a result of buybacks can be found in any introductory corporate finance textbook. I won’t rehash them here. Readers interested in the topic can review the research papers I have linked below. In the first one, it is well worth reading the section titled “Myth 4.” If theory doesn’t interest you, the second link leads to an empirical study examining all share buybacks executed in the United States and their effect on the value and future returns of remaining shares (the takeaway in a nutshell: they had no impact).
(I have often heard the counterargument: “that may be true in theory, but in real life, things are completely different.” I don’t quite understand this objection, given that the vast majority of financial research is empirical—meaning it studies observations drawn from the very “real life” these counterarguments refer to. Empirical research on share buybacks and related phenomena simply happens to show, at least on this topic, that real life unfolds exactly as theory predicts.)
https://papers.ssrn.com/sol3/papers.cfm?abstract_id=4149796
13. Thinking seriously from the perspective of a regular, hardworking stock picker: do dividends make any sense at all? You pay taxes on wealth accumulation every year and reinvest the proceeds… what sense does this make for an ordinary investor?
It really depends on what one intends to do with the dividend. If it is used for consumption (and without the dividend, the investor would lack sufficient cash flow for consumption), then the dividend serves a purpose. If, however, one pays tax on the dividend and simply reinvests it back into the same company, it certainly does not make the investor any wealthier—from their perspective, it would have been better had the dividend not been paid. Here, one must keep in mind, though, that paying that dividend might have been optimal for the company (= a lack of sufficiently profitable investment opportunities), since retaining the capital within the business would have destroyed shareholder value. It’s not entirely that simple. 
The main point, however, is that a dividend in itself does not grow an investor’s wealth, nor do I consider it a way to “reward” shareholders. This is an important concept to grasp. A high dividend yield is not, in and of itself, a reason to buy a company’s stock—unless, of course, the investor has good reason to believe the high dividend yield is a symptom of market undervaluation.
14. Why do you invest?
Perhaps because investing is one way to create a safe haven where one can take shelter when needed from the challenges brought by an uncertain and unknown future. It is also a way to build capital to leave behind for future generations. Plus, investing is naturally an entertaining pastime.
15. If you had to warn Alokas about one beginner’s investing pitfall, what would you warn against and why?
Don’t hit the panic button. It usually leads to ruin.
16. What would you like to thank the Finnish investing community for?
Thank you for the engaging discussions! Unfortunately, I don’t have the time to participate actively due to my schedule, but I gladly follow along whenever possible.
Thank you very much for the answers, Peter!
I think it’s fantastic how engagingly and intelligently he writes. Anyone reading his insights with a genuine desire to learn is sure to gain lasting “tools” for their own investing journey.
It is vital to possess theoretical knowledge alongside practical market understanding, both of which Peter clearly has—topped off with the ability to write about these topics in such an accessible way.
Thank you, and have a great weekend! 