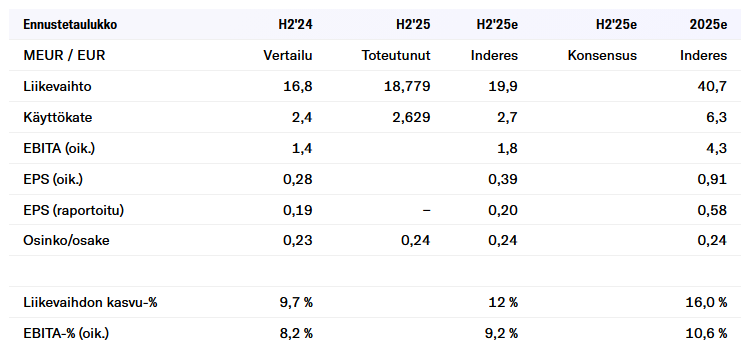
Here is Atte’s preview as Aallon Group reports its H2 results on Thursday, February 12, 2026
We expect the company’s H2 revenue to have grown strongly, driven by acquisitions, but organic growth to have remained slightly negative as the Finnish economy stayed sluggish. Regarding the results, interest is focused especially on the profitability of the end of the year, which has been affected by the ongoing organizational restructuring and related one-off costs. Adjusted for one-off items, we expect Aallon Group’s result to have grown, supported by the acquisitions made. The reforms carried out this year should gradually begin to bring more efficiency to the company’s operations.
At times, I’ve wondered the same thing—that the market hasn’t really appreciated this performance. Of course, that period included a pretty massive repricing of stocks as the interest rate environment changed drastically after the long zero-interest-rate era. Followed by the misery of the Finnish economy and a proper small-cap bear market, it’s no wonder the share price isn’t going anywhere despite the good performance
However, it makes me wonder if the market might be farsighted, already discounting a drying up of the acquisition pipeline or some other deterioration of the process. In Aallon’s sector, suitable targets aren’t necessarily available indefinitely in the domestic market alone, and the industry is being consolidated from many directions simultaneously. Furthermore, the industry is relatively people-driven, which brings its own risks regarding the continuity of the acquired companies—something that has already been discussed at length in this thread.
Also, the low share ownership of the management team and the board bothers me; I’d like to see more of it, given that the investment case relies heavily on successful capital allocation—meaning, in practice, success in acquisitions. Granted, they have succeeded quite well in that historically.
Or is this actually the exact moment when one should get excited about these Helsinki small-caps, and my skepticism is just caused by this lengthy small-cap bear market and the misery of the Finnish economy? Of course, at the current valuation, Aallon could be a decent investment for the next Finnish economic upturn (will there even be one anymore? ), even if it doesn’t turn out to be a value-creating “compounder” fueled by acquisitions for decades to come.
By the way, tomorrow, for the first time ever, Aallon Group’s earnings briefing can also be followed via Teams. Up until now, I’ve usually been the only one there in person
If you’re interested in joining the briefing at 10:00 AM, please pre-register via this invitation:
The numbers were quite sour. Revenue grew by about 4.5 mEUR year-on-year, but none of it trickled down to the profit. Also curious is the EBITDA, which is behaving exceptionally compared to the other figures, albeit positively. Looking forward to hearing Keronen’s explanations.
Well, so they’ve gone and started their own software development now. It’s true, as Keronen says, that AI has lowered development costs, but I wonder if it’s sensible to invest in proprietary software at this stage. The expectation is that software will be even cheaper in the future, and it seems that as competition between accounting software providers intensifies, it would be relatively cost-effective to operate using third-party software in the future.
This also explains why Talenom’s (and many other software companies’) share price is heading downhill. The millions poured into software development in past years now look like quite expensive projects in the current light.
Yeah, no. Not good. Of course, it would be interesting if they vibe-code a brilliant accounting software. It’ll be a good example of how small companies can use AI to break away from software produced by others. In principle, the company has valuable customer relationships, and if software development becomes commoditized, the value of those customer relationships grows relative to technological expertise. Still… why build it yourself when cutthroat competition among third parties in the aforementioned scenario will likely significantly drive down software prices. And the software that wins that competition will presumably be really good.
I thought I saw this development coming already 1.5 years ago when Ari got the boot, and now this horror scenario is coming true.
I immediately had to do a quick check (a sophisticated investor would probably think ahead) on how this compares to Talenom. They’ve probably poured closer to 100 million into system development over the last 10 years.
Surprisingly, it seems that Aallon Group is in exactly the same situation as Talenom was when they started software development. Revenue for both is around the 40 million level. In the early days, Talenom seemed to develop with fairly moderate investments (a few million per year). You can probably crunch this into a reasonable ROI in Excel if profitability could rise following Talenom’s example. Hopefully, Atte or someone wiser could make a detailed outline, based on Talenom’s data, on whether this makes sense for the owners. I’m a bit terrified regarding the cash flow, but knowing Talenom’s management, I am more confident in Aallon’s ability to make profitable investments.
A major positive observation from the financial statements was that the organizational reform + the implementation of the ERP system did not cause profitability to collapse as I had feared. Employee satisfaction was also excellent despite the changes. If no customers have been lost to direct competitors despite the drop in organic revenue, then the core business is rolling along well.
Personally, I don’t believe that software prices are on a permanent downward trend. At least no historical development points to that.
Atte interviewed Aallon Group CEO Tuija Keronen regarding H2
Topics:
00:00 Start
00:12 Key highlights of the second half and full year
00:58 Progress of the acquisition strategy
02:54 Organic growth
04:22 Consolidation of property management agencies
04:57 Profitability development
05:49 Cash flow
06:23 Organizational restructuring
07:31 The role of AI in the daily work of accountants
08:47 Aallon Portti & proprietary accounting software
11:07 Outlook for 2026
The costs from external software houses can be 15% of the revenue of accounting firms after resale commissions. Of course, these are passed on to the customers. But if we consider that Aallon’s revenue is 40 million euros, this cash flow leaking outside could be 6 million euros per year. Over 5 years, that’s more than 30 million euros, assuming the business grows. With its own software, there would be an opportunity to tap into this potential of tens of millions of euros, which comes solely from its own customer base.
I agree with BoomDriver that software prices are not declining, at least in the short term. This is a Finnish oligopoly where players have not shied away from even substantial price hikes.
It is no wonder that this business case interests AG. If the software project is managed with common sense, the payback period could be very attractive.
I don’t really know for sure, but judging by the number of accounting software options, the industry might not be particularly challenging. Maybe some savings could be achieved?
The challenge is transforming into a software house, as software is so much more than just programming. That’s the easy part.
It’s hard to make that Aallon Port modern, but it can probably be done if enough money is thrown at it. Integrating accounting into it is no walk in the park, either. That ERP system (Koho) is not new; apparently, they just merged the company’s many Kohos into one.
Atte has written a new company report on Aallon Group after the H2 results were released.
We are lowering Aallon Group’s target price to EUR 10.5 (prev. EUR 13.0) along with forecast changes and lowering the recommendation to Reduce (prev. Buy). We still believe the company is well-positioned to grow its earnings through acquisitions and operational efficiency improvements, for which the completed organizational reform now opens up opportunities. However, we have taken a more cautious stance than before regarding the company’s short- and long-term organic growth outlook. Consequently, we no longer expect the stock’s seemingly moderate valuation (2026e P/E 11x, EV/EBIT 9.3x) to correct significantly upwards over the next 12 months.
Quoted from the report:
We still see the company’s acquisition strategy creating value and its consistent implementation gradually increasing the company’s fair value in the coming years. The track record from recent years is good in this regard, and the company has found a working recipe for acquiring small and medium-sized accounting firms with moderate valuation multiples. These arrangements have also been reflected in the company’s figures in the form of earnings growth. The company’s earnings also convert to free cash flow at a good ratio, which can be allocated to making new transactions and paying dividends.
AG’s Q4 didn’t go quite as planned this time, in a way that an owner could have just glanced at the interim report and gone back to sleep. (Which would have been fine).
The figures themselves were reasonable enough. In my (and probably many others’) books, AI has been the thing that is a difficult-to-grasp question mark in the long run for an average Joe like me. Something you have to ponder occasionally—how to view it and on what timeframe it might affect the company. Otherwise, this is very defensive business.
Now, a new question entered the equation: accounting software development. What it costs, how long it takes, etc. At the same time, the analyst reported that their uncertainty regarding the long-term outlook for the company (and the industry) has increased (e.g., that AI), and the stock is rated ‘reduce’ at a price of 10.10.
This raised a question for me: if AG was already quite unpopular (and therefore so cheap), is it sliding even deeper into the bargain bin, where investors are only willing to pay very low multiples? For these low-volume and sparsely followed stocks, the limited analysis available often impacts the trend more than with large companies. Of course, the company has the opportunity over time to prove that it can still grow organically and that AI won’t take the bread off the table. One thesis for this stock has been the unwinding of the undervaluation. Its realization took a setback, to say the least.
Summa summarum: a boring company saw way too many exciting twists.
Well put, that “too many exciting twists at once for a boring company.” I decided for myself that I won’t stay to watch this action movie brought by software development, as I didn’t originally buy a software firm but 100% deadly boring accounting. I hope, of course, that Aallon Group succeeds on its chosen path.
I find the initiative of In-house Software Development interesting. Assuming the company currently spends roughly 5/10% of its revenue on external software (2/3M??), developing its own tools for a few million euros (leveraging existing assets, new software development tools and accounting expertise) could offer a very quick payback. More importantly it can grant them the strategic freedom to deploy new automation/AI tools to optimize long-term operations. But it’s true that the management must have a much clearer communication and share it’s long term vision on this.
In my view, accounting firms could be “net beneficiaries” of AI. They can significantly slash operational costs while maintaining their primary moat : client trust. Throughout 2025, many articles highlighted the trend of VCs targeting accounting roll-ups driven by AI automation. Venture Firms Target Accounting Roll-Ups with AI Automation Play
These challenges reinforce the ongoing consolidation in the industry. Aallon benefits from this, initially as an acquirer, and maybe as a takeover target in the medium/long term.
The main headwind remains the weak organic growth and the Finnish macro environment. However, I believe the current valuation already reflects these risks.
I largely agree with MattFR. Except for the fact that the share of systems in revenue is clearly more than 5%, and as a result, proprietary software is of interest to larger players.
Modern firms benefit from AI by shifting pricing from hourly billing to fixed fees and increasing labor productivity with AI. This way, the majority of the benefits of AI remain with the firm. Some of the efficiency gains can be passed on to customers, but there isn’t huge pressure to do so because competition isn’t particularly intense.
I suspect that revenue development in the sector in Finland will be moderate, but with AI, it is possible to achieve significantly better profitability than at present.
Inderes’ forecast is very pessimistic. Revenue growth of 0.6% in 2027 and 1.0% in 2028. Based on the forecast, operations are shrinking when price increases are taken into account.
Growth from 2019–2025 has averaged over 15%. If growth were to continue, the 2028 revenue should be €60m; in the forecast, it’s €42.3m. Even with a 5-10% forecast, the figures are completely different. Earnings performance has been okay, but could be a bit better. I don’t really understand such a cautious forecast. AI risks are difficult to assess, but perhaps they will reflect positively on potential acquisition targets.